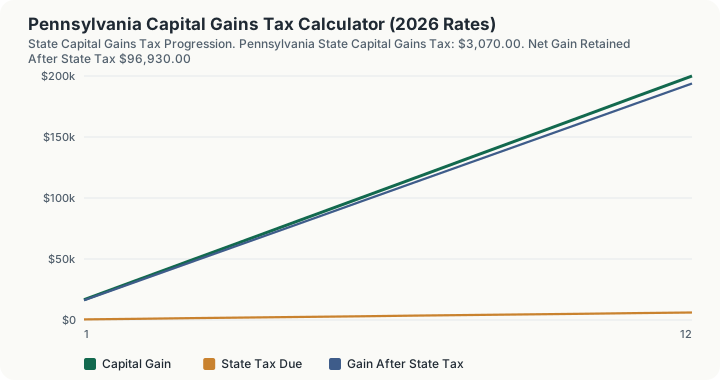
Quick Answer: On a $100,000 capital gain, Pennsylvania's flat 3.07% state tax adds $3,070.00 to your bill, leaving $96,930.00 after state tax.
A Flat 3.07%, And No Loss Carryforward
Pennsylvania taxes capital gains as ordinary income at a flat statutory individual income tax rate of 3.07%, applying uniformly across all realized investment profits regardless of holding period or total taxable income.
Capital gains from stock sales, business equity, real estate, and digital assets simply get added to gross income and taxed at the state's uniform statutory rate of 3.07%, since Pennsylvania runs a flat income tax structure. No preferential rate distinction exists between short-term and long-term gains at the state level.
Understanding state-level capital gains taxation is essential for high-net-worth individuals, portfolio managers, corporate executives, and real estate investors. State income taxes significantly affect net internal rates of return (IRR) on capital dispositions, 1031 exchange planning, installment sale structuring, and equity compensation exercises (ISOs, NSOs, and RSUs).
In institutional wealth management and private equity underwriting, capital gains calculations must account for both statutory tax rates and multi-jurisdictional residency rules. Whether disposing of publicly traded securities, privately held business interests, real property, or digital assets, evaluating state-level tax exposure is a critical component of pre-liquidity tax modeling and post-sale wealth preservation.
Proper capital asset planning in Pennsylvania requires tracking taxable events across federal and state reporting cycles. Because timing and holding structure dictate net after-tax proceeds, investors must rigorously analyze the interaction between federal adjusted gross income (AGI) baselines and state modifications before closing substantial transactions.
How This Is Calculated
Pennsylvania taxes net gains on the disposition of property at a flat 3.07%, and it is unusually strict about what may offset them: Pennsylvania does not allow capital losses to be carried forward to another year, so a loss that goes unused in the year it is realized is gone. This calculator takes the net gain you enter as final and does not model that carryforward difference.
That makes the state computation a single multiplication, with the effective rate falling straight out of it.
The full sequence:
- Start with the net gain. Capital losses and loss carryforwards are netted first; what you enter is the net figure.
- No preferential rate. Pennsylvania has no separate capital gains rate and no long-term holding-period break, so the gain is taxed exactly as wages would be.
- Apply the rate. Multiply the net gain by 3.07%. Because the schedule is flat, your other income does not push the gain into a higher band, and the calculator does not need to stack the two.
- Effective rate. Total tax divided by realized gain, which on a flat schedule returns 3.07% at every gain size. Effective and marginal rates are the same number here.
- Net proceeds. Subtract the state tax from the gain to get what you keep before federal tax.
Worked Example
Consider an investor in Pennsylvania who realizes $100,000 in capital gains from a single asset sale during the year.
- Identify the gain. The full $100,000 capital gain is added to gross income, since Pennsylvania taxes capital gains at the same statutory rate as wages and other ordinary income, with no separate preferential rate for long-term holdings.
- Apply the flat rate. Pennsylvania's statutory individual income tax rate is a uniform 3.07%, applied to the entire gain regardless of the investor's total income or how long the asset was held.
- Compute the tax due. $100,000 × 3.07% = $3,070.00, the state tax liability on this sale.
- Net proceeds. Subtracting the $3,070.00 state tax from the $100,000 gain leaves the investor with $96,930.00 in state after-tax proceeds, before any federal capital gains tax is applied separately.
Because Pennsylvania applies one flat rate to every dollar of gain, the effective state tax rate here equals the statutory rate itself: 3.07%.
Pricing A Pennsylvania Gain, And The Two Errors People Make
Pennsylvania's rate is constitutionally uniform, so this page has no bracket edge. What it has instead is a rule about losses that changes the answer more than any bracket would.
The marginal cost of the next unit. Raising the gain from $100,000 to $101,000 moves Pennsylvania's tax from $3,070.00 to $3,100.70. Every additional $1,000 of gain costs exactly $30.70, at every gain size. The twelve-row schedule confirms it: $16,666.67 more gain and $511.67 more tax on every row, from row one through row twelve.
Other income changes nothing. The engine returns $3,070.00 on a $100,000 gain whether the other-income field holds $75,000 or $0. There is no stacking, because 3.07% applies to the first dollar of gain and to the last.
The reverse question: how large a gain fits a tax budget? Divide by 0.0307. A $500,000 gain produces $15,350.00; a $10,000 Pennsylvania tax bill corresponds to $325,732.90 of gain. The relationship is exactly linear, so spreading a sale across tax years saves nothing at the state level in Pennsylvania.
Right method against wrong method, first error. Assuming Pennsylvania mirrors the federal long-term preference. It does not: there is no reduced rate, no holding-period break and no zero bracket. A filer expecting the federal 0% long-term bracket to apply to a $100,000 gain budgets nothing and owes $3,070.00.
Right method against wrong method, second error, and this one is specific to Pennsylvania. Pennsylvania does not permit capital losses to be carried forward to another tax year. A filer who realises a $100,000 loss in one year and a $100,000 gain in the next nets them to zero on a federal return and owes nothing; in Pennsylvania the loss is gone and the gain costs the full $3,070.00. This calculator takes the net gain you enter as final and models no carryforward in either direction, so it will happily accept a federally netted figure that Pennsylvania would not recognise.
What else is not modelled. No Pennsylvania standard deduction or personal exemption exists to apply, and none is applied. Philadelphia's School Income Tax, which reaches certain investment income for city residents, is computed nowhere on this page, and neither is the state's separate treatment of gain on the sale of a principal residence, which Pennsylvania exempts under its own rules rather than the federal ones.
What This Does Not Account For
While this calculator provides penny-exact state statutory modeling, additional federal and transactional complexities warrant supplementary review: - Federal Capital Gains Taxes: Federal long-term brackets (0%, 15%, 20%) and short-term ordinary rates up to 37% under IRC § 1. - Net Investment Income Tax (NIIT): The 3.8% surtax on net investment income under IRC § 1411 for single filers over $200,000 (married joint over $250,000). - Alternative Minimum Tax (AMT): Federal AMT calculations under IRC § 55 impacting incentive stock option (ISO) exercise spread. - Section 1031 Like-Kind Exchanges: Tax deferral mechanisms for real property held for productive use in trade, business, or investment. - Qualified Small Business Stock (QSBS): Federal Section 1202 gain exclusions where state conformity varies significantly.
Common Pitfalls
- Assuming Federal Rate Parity: Most states do not offer preferential long-term capital gains rates; gains are taxed at standard ordinary income rates.
- Failing to Track Holding Periods: Short-term gains (assets held ≤1 year) generate higher federal tax liabilities even if state rates treat both holding periods identically.
- Underestimating Multi-State Apportionment: Selling real estate or business assets located in other jurisdictions triggers multi-state non-resident return filing obligations.
- Neglecting Underpayment Penalties: Substantial one-time liquidity events require prompt estimated tax payments within the quarter of sale to avoid statutory penalties.
- Mismatched Cost Basis Records: Failure to document reinvested dividends, stock splits, or structural return-of-capital distributions leads to inflated taxable gain calculations.
Frequently Asked Questions
Does Pennsylvania have a state capital gains tax?
How are short-term and long-term capital gains taxed in Pennsylvania?
Are retirement account distributions subject to capital gains tax in Pennsylvania?
Can capital losses offset capital gains in Pennsylvania?
When are estimated state tax payments required on capital gains?
Sources
- Pennsylvania Department of Revenue: 2026 Statutory Individual Income Tax Rate Schedules. revenue.pa.gov
- Internal Revenue Service (IRS): Publication 544 (Sales and Other Dispositions of Assets) and Publication 550 (Investment Income and Expenses). irs.gov/publications/p544