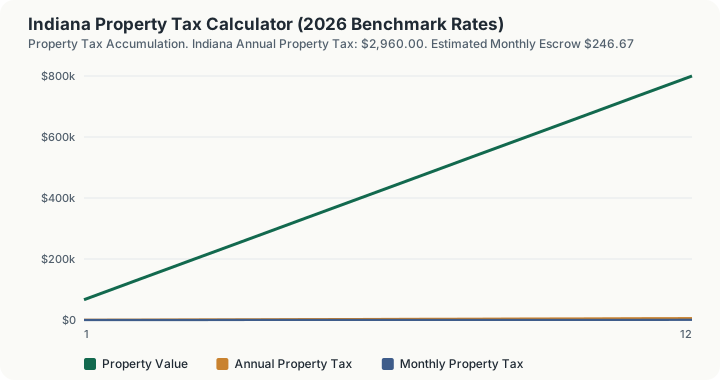
Quick Answer: A $400,000 home in Indiana carries an estimated $2,960.00 in annual property tax at the state's 0.74% effective rate, or about $246.67 a month.
A Below-Average Rate, and What the Number Actually Contains
Ranked #28 out of 50 states at an average effective rate of 0.74%, Indiana lands below the national median. That is noticeably below the national average of roughly 1.0%, based on the average effective rate across all 50 states. Compared with the rest of the Midwest, which averages roughly 1.35%, Indiana lands well below its neighbors.
As in most of the Midwest, property tax revenue in Indiana funds local school districts, county services, and municipal budgets rather than flowing through a state-level general fund, so the rate is effectively set locally even though the average is reported statewide.
Assessments are handled at the county level in Indiana, where local appraisers periodically revalue residential and commercial parcels and apply the applicable millage rates; homestead exemptions and formal appeals remain the main levers available to individual owners looking to manage the bill, alongside any local bond measures voters approve along the way.
How This Is Calculated
Indiana wrote its property tax ceiling into the state constitution. Circuit breaker caps limit the bill to 1% of gross assessed value on a homestead, 2% on other residential and farm ground, and 3% on commercial property, so once a bill hits the cap, further increases in local rates simply do not reach the taxpayer.
None of that detail is asked for here. This calculator works one level up, applying Indiana's average effective property tax rate of 0.74% to the value you enter. That rate is the ratio of property taxes actually paid to home value across the state, so the assessment ratios, caps, and exemptions described above are already baked into it.
Read steps 1 and 2 as background on how an Indiana bill is built, not as operations in this engine. The calculator holds no assessed value, no deduction schedule and no circuit breaker cap. Steps 3 to 5 are what the code does.
- Start from gross assessed value. Assessors use market-based valuation with annual trending adjustments.
- Take off deductions. The standard homestead deduction and the supplemental homestead deduction come off before rates apply, and only then is the circuit breaker cap tested.
- Multiply by the effective rate. At 0.74%, a $400,000 home in Indiana comes to $2,960 a year before any exemption you enter above.
- Divide by twelve for escrow. That same home works out to $246.67 a month set aside in a mortgage escrow account.
- Compare it against your own bill. In high-rate areas the cap, not the rate, determines the bill, and the shortfall is absorbed by the local units rather than billed elsewhere. Your county's number is the one that governs; this figure tells you whether it is roughly where an Indiana home of that value ought to land.
Worked Example
Using this calculator's baseline inputs: a $400,000 home in Indiana, taxed at the state's 0.74% average effective rate (rank #28 of 50 states).
- Start with the assessed value. The home is assessed at its full $400,000.00 market value, with no homestead exemption applied in this baseline scenario.
- Apply the effective rate. $400,000.00 × 0.74% = $2,960.00 in annual property tax, Indiana's statewide average effective rate.
- Convert to a monthly escrow. Lenders typically collect property tax in twelve equal installments alongside principal and interest: $2,960.00 ÷ 12 = $246.67 per month.
- Project a five-year hold. At a flat rate, five years of ownership totals $2,960.00 × 5 = $14,800.00, before any reassessment, exemption change, or millage increase.
At 0.74%, Indiana lands roughly in the middle nationally, ranking #28 of 50 states: a moderate but still material carrying cost for homeowners.
Walking the Twelve-Row Value Table
Start with the disagreement, because it catches people first. Enter Indiana's standard homestead deduction of $45,000 against the $400,000 default and the headline drops from $2,960.00 to $2,627.00. Every row of the table below stays put: the $400,000 row still reads $2,960.00. That is not a bug to work around, it is what the table is. compute applies the deduction to the headline value and then builds all twelve schedule rows from the value you typed, so the table answers "what would this house cost at other prices", not "what would my bill be after deductions".
The sweep itself. Value runs $66,666.67 to $800,000.00 and annual tax runs $493.33 to $5,920.00, with $2,960.00 at the $400,000 row and a monthly escrow figure of $246.67 beside it. Each row divides to 0.74%.
There is no rate step in here at any value. Indiana's constitutional circuit breaker caps a homestead bill at 1% of gross assessed value, and that cap is nowhere in this code: calculateStatePropertyTax reads Indiana's 0.74% statewide effective rate and multiplies, with no cap test, no gross assessed value and no property class. In a high-levy township where the cap actually binds, the real bill is set by the cap rather than by any rate, and this page cannot tell you that it is happening.
Marginal cost of the next unit. Each $10,000 of additional value costs $74.00 a year, and each $100,000 costs $740.00. Raise the entry from $400,000 to $410,000 and the annual figure goes from $2,960.00 to $3,034.00.
The reverse question. A $250 monthly escrow line supports an Indiana home worth $405,405, which the calculator returns as $3,000.00 a year and $250.00 a month. The same $250 in Illinois, at 1.92%, carries $156,250 of house. On a $400,000 purchase the two states differ by $4,720.00 a year, which is roughly the difference the sweep's own first and last rows span.
Where the number gets built wrong. The recurring error is multiplying a township's posted rate by market value. Indiana's 0.74% here is the ratio of tax actually paid to home value statewide, already net of the standard and supplemental homestead deductions and of the circuit breaker. A nominal rate applied to full market value double-counts relief the average already contains. The number to compare this against is your own bill divided by what the house would sell for.
What This Does Not Account For
- Specific hyper-local county and municipal millage district variations within Indiana.
- Barrett Law assessments. Some Indiana cities, including Indianapolis, use this state law to bill property owners a separate assessment for sewer, sidewalk, or street improvements, repayable in installments over up to 30 years and layered on top of the base county and township rate.
- Commercial vs residential assessment classification differentials.
- Property tax appeal reductions or localized board of equalization adjustments.
Common Pitfalls
- Confusing Market Fair Value with Assessed Basis: Some jurisdictions assess property at fractional ratios rather than 100% of market value.
- Failing to File Homestead Paperwork: Homestead exemptions are rarely automatic; homeowners must file timely paperwork with the county appraisal district.
- Underestimating Post-Sale Supplemental Assessments: Purchasing a newly constructed or reassessed property often triggers catch-up supplemental tax bills.
- Ignoring Property Tax Appeal Windows: Missing the annual 30-to-60 day statutory protest window forfeits the right to challenge over-assessed property values for that tax year.
Frequently Asked Questions
How high are property taxes in Indiana?
When are property taxes due in Indiana?
How can I lower my property taxes in Indiana?
Does purchasing a home trigger a property tax reassessment?
Sources
- U.S. Census Bureau: American Community Survey (ACS) Real Estate Assessment Benchmark Data. census.gov/programs-surveys/acs
Also consulted: Indiana Department of Local Government Finance: Property Tax Assessment Guidance.