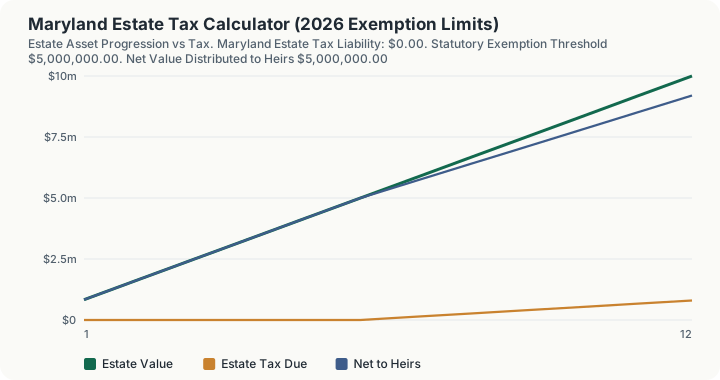
Quick Answer: Maryland's state estate tax exemption is $5,000,000, so a $5,000,000 estate falls entirely below the threshold and owes $0 in Maryland estate tax; only value above $5,000,000 would be taxed, up to 16.0%.
Two State Death Taxes, One Modelled Here
Maryland is the only state in the country that imposes both a state-level estate tax and a separate inheritance tax on the same estate, a distinction none of the other eleven states with an estate tax, and none of the four states with only an inheritance tax, can claim.
The estate tax applies above a $5,000,000 exemption, and every dollar above that line is taxed at a flat 16% rather than through a graduated ladder, calculated independently of whatever the estate additionally owes under Maryland's inheritance tax, which is assessed separately based on a beneficiary's relationship to the decedent.
That double layer means a single Maryland death can generate two distinct state tax bills: one calculated against the gross taxable estate before distribution, and another calculated against what specific beneficiaries actually receive.
For families with property or beneficiaries in neighboring Virginia or West Virginia, neither of which taxes estates or inheritances, the contrast can be stark: identical wealth transferred just across the Potomac produces a materially different state tax outcome depending on where the decedent was domiciled.
How This Is Calculated
The calculator starts from two numbers you enter: the gross estate at fair market value, and the marital, charitable, and administrative deductions the estate can claim. It subtracts the second from the first to get the net estate, then applies Maryland's own schedule to that figure. Nothing else feeds the result.
Maryland runs no bracket ladder. Once the net estate clears $5,000,000, every dollar above that line is taxed at the same 16%, so the marginal rate and the top rate are the same number.
- Value the gross estate. Fair market value at the date of death of all real property, business interests, securities, cash, and life insurance proceeds the decedent owned.
- Subtract allowable deductions. Debts, administrative expenses, qualifying charitable bequests, and the unlimited marital deduction come off the gross figure.
- Subtract the $5,000,000 exemption from what remains. A negative result is treated as zero, and the tax is $0.
- Multiply by 16%. There is no second bracket to reach and no graduated ramp, which is why the effective rate on the whole estate rises smoothly toward 16% as the estate grows rather than stepping up.
- Subtract the tax from the net estate to get what beneficiaries receive.
Maryland Form MET-1 caps the gross liability at the lesser of 16% of the excess over the $5,000,000 exclusion and the pre-2001 federal state-death-tax credit table applied to the whole estate. Because the exclusion is so much larger than that table's own $60,000 adjustment, the 16% cap is always the smaller of the two, which is why a single flat rate is the correct answer at every estate size. Maryland also levies a separate inheritance tax on certain beneficiaries; that is a different tax, computed per beneficiary, and this calculator does not include it.
That is the entire computation. The calculator does not carry over a deceased spouse's unused exemption, add back lifetime taxable gifts, apply the generation-skipping transfer tax, discount closely held interests, or figure the separate federal return. Those sit under "What This Does Not Account For" below, not in the math above.
Worked Example
- Start with the gross estate. This example uses a $5,000,000 gross estate: the fair market value of all property, business interests, equities, cash, and life insurance the decedent owned at death, before deductions.
- Compare against Maryland's exemption. Maryland taxes estates only above $5,000,000; the $5,000,000 estate sits at or below that threshold, so none of it is taxable.
- Taxable estate above exemption. $5,000,000 minus the $5,000,000 exemption leaves nothing above the line, so the taxable estate above the exemption is $0.
- Compute the tax due. With nothing above the exemption, the calculator returns $0.00 in Maryland estate tax, even though Maryland's top bracket reaches 16.0% above the threshold.
- Distribute the net estate. The full $5,000,000.00 gross estate passes to beneficiaries undiminished.
- What this leaves out. This is Maryland's state-level result only; federal estate tax is assessed separately under IRC § 2010.
Standing at $5,000,000: What the First Dollar Over the Line Costs
Maryland's schedule is the simplest in this family and its single edge is also the sharpest, because the rate above the exemption does not ramp. It starts at 16% and stays there.
The threshold walk. At a net estate of $5,000,000 the engine returns $0.00 of Maryland estate tax and passes the full $5,000,000.00 to heirs. At $5,001,000, one thousand dollars later, it returns $160.00. At $5,100,000 it returns $16,000.00. There is no graduated entry band: the very first dollar above the exemption is taxed at the same 16% as the millionth, which is what distinguishes Maryland's flat-above-exemption structure from Minnesota's 13%-to-16% ramp or Massachusetts's credit table. An estate at $4,900,000 owes $0.00, identical to one at exactly $5,000,000.
The marginal cost of the next unit. Every additional $1,000 of net estate above the exemption costs $160.00, at every size. The engine returns $800,000.00 on a $10,000,000 estate and $1,600,000.00 on $15,000,000, both exactly 16% of the excess. The effective rate climbs from 0.31% at $5,100,000 to 8.00% at $10,000,000 and 10.67% at $15,000,000, approaching but never reaching the 16% marginal figure.
The reverse question. How much can pass before Maryland takes anything? Exactly $5,000,000 of net estate, and the engine confirms $0.00 there. Deductions move that ceiling dollar for dollar, because the calculator subtracts them from the gross before the exemption test. A $6,000,000 gross estate with $1,000,000 of allowable marital or charitable deductions computes against a $5,000,000 net estate and owes $0.00; the same $5,000,000 gross estate with $1,000,000 of deductions also owes $0.00, with $4,000,000.00 shown as distributed.
Right method against wrong method, priced. The error worth pricing is applying 16% to the whole estate rather than to the excess. On a $15,000,000 estate that gives $2,400,000 against the engine's $1,600,000.00, an overstatement of $800,000.00. On the $10,000,000 estate it overstates by $800,000.00 as well, since the exemption's value in tax terms is a constant $800,000 at any size above the line.
The other Maryland death tax is not in this calculation at all. Maryland is the only state levying both an estate tax and an inheritance tax, and this calculator computes the estate tax only. The inheritance tax falls on collateral beneficiaries at 10% of the clear value passing to them, and no code path here applies it. A $4,000,000 estate passing entirely to nieces and nephews owes $0.00 by this calculator and a substantial inheritance tax in fact. The two are computed on different bases against different payers, so the figure on this page is a floor rather than the whole state bill.
What This Does Not Account For
- Portability of a deceased spouse's unused exemption. Most states with an estate tax, including this one, do not allow it at the state level, and the calculator does not apply it in either direction.
- Lifetime taxable gifts added back into the taxable estate, and any QTIP election, credit shelter trust, or state QTIP decoupling that would change what the taxable estate actually is.
- Valuation discounts for minority or non-marketable interests in closely held entities. Enter the discounted value yourself if the appraisal supports one.
- Federal generation-skipping transfer (GST) tax under IRC Chapter 13.
- Ancillary probate requirements for real property situated in other jurisdictions.
- Complex liquidity discounts for minority non-voting family business entities.
- State-specific inheritance taxes levied directly on beneficiaries (e.g. PA, NJ, MD, KY, NE).
Common Pitfalls
- Assuming State Exemption Matches Federal: Forgetting that states like Oregon ($1.0M) and Massachusetts ($2.0M) tax estates far below the federal threshold.
- The "Cliff" Effect in Specific States: Failing to recognize that states like New York eliminate the exemption entirely if the estate exceeds 105% of the threshold.
- Out-of-State Real Property Exposure: Holding real estate in states with active estate taxes exposes non-resident estates to proportional state estate taxes.
- Failing to Fund Revocable Living Trusts: Assets held outside trust structures are subjected to public probate proceedings and statutory executor fees.
Frequently Asked Questions
Does Maryland have a state estate tax?
Does Maryland have an inheritance tax?
When is state estate tax due?
What assets are included in the taxable estate?
Sources
- Comptroller of Maryland: Estate Tax Guidance (2026). marylandtaxes.gov