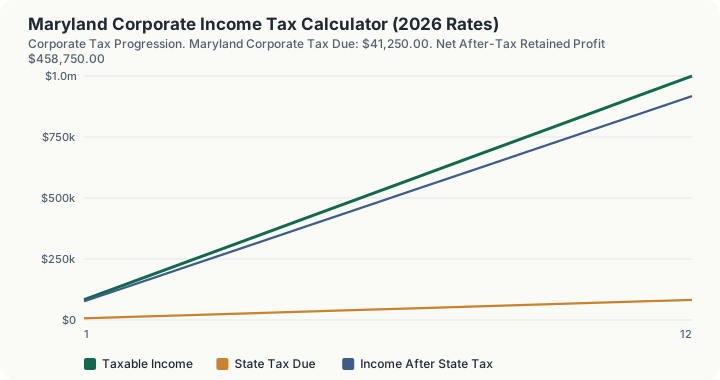
Quick Answer: On $500,000 of pre-apportioned taxable income, Maryland's flat 8.25% corporate income tax rate produces $41,250.00 in state tax due and $458,750.00 in net after-tax profit.
Maryland at a Flat 8.25%
8.25%: Maryland's flat corporate income tax rate sits firmly in the upper third of states that tax corporate income, higher than neighboring Virginia's 6.00% and West Virginia's 6.5%, though still below Delaware's 8.70% just across the state line.
Maryland applies its 8.25% rate uniformly to all apportioned C-corporation income, with no bracket thresholds, so the marginal and effective rates are identical regardless of company size. For a Mid-Atlantic corporation weighing Maryland against its immediate neighbors, the rate differential between Virginia and Maryland alone (6.00% versus 8.25%) can meaningfully affect where income gets sourced when apportionment factors allow some flexibility.
Maryland's 8.25% rate turns the calculator's $500,000 example into $41,250.00 of state tax, well above the $30,000.00 the identical income would generate in neighboring Virginia at its 6.00% rate, an $11,250.00 difference on the same $500,000 base.
How This Is Calculated
Maryland's 8.25% flat rate is among the highest on the East Coast, and Maryland is one of the few large states that still does not require unitary combined reporting, filing instead on a separate-entity basis. That single structural choice, more than the rate, is what shapes Maryland planning for multi-entity groups.
- Read the income field as the taxable base. The single income input is taken as Maryland taxable corporate income exactly as typed. The code applies no modification, allocation or deduction to it before the rate stage; it is the base.
- Apply the single statutory rate. Maryland's 8.25% rate is multiplied against that figure with no bracket lookup, because the schedule has one band running from the first dollar: $500,000 x 8.25% = $41,250.00.
- Subtract credits and floor the result at zero. The credits field is subtracted from the step-2 figure and the difference is clamped at $0.00, so no credit entry can drive the liability negative. With the field at its $0 default the $41,250.00 stands; enter $17,000 of credits and the page returns $24,250.00, a reduction of exactly the credit entered because the subtraction is a straight one.
- Derive the reported rates from those two numbers. The effective rate is the tax divided by the income entered, 8.25% here, and the top statutory bracket is reported separately as 8.25%. Net after-tax retained profit is the income less the tax, $458,750.00. Those four outputs are the whole of what the engine produces.
Worked Example
Using this calculator's baseline scenario: a corporation with $500,000 in taxable income apportioned to Maryland.
- Start with apportioned taxable income. The corporation has already apportioned $500,000 of its total taxable income to Maryland using the state's statutory apportionment formula, before any state-level tax is applied.
- Apply Maryland's flat statutory rate. Maryland taxes all C-corporation income at a single flat rate of 8.25%, regardless of income size, so no bracket lookup is required: $500,000 × 8.25% = $41,250.00.
- Maryland corporate tax due: $41,250.00.
- Net retained profit. Subtracting the state tax liability from taxable income leaves $500,000 − $41,250.00 = $458,750.00 in after-tax profit retained by the corporation, before any separate federal tax liability is applied.
Because Maryland uses a single flat rate rather than graduated brackets, the 8.25% effective rate is identical to the marginal rate at every income level: a corporation earning $50,000 and one earning $50 million both face the same 8.25% state rate on their apportioned income.
Credits Against Rate: What a Dollar of Each Is Actually Worth
Maryland's flat rate means the income sweep has no edge in it, so the lever the calculator actually exposes is the credit field, and the arithmetic there is not the same as the arithmetic of a deduction.
The marginal cost of the next unit. Each additional $1,000 of Maryland apportioned taxable income costs $82.50. The engine returns $41,250.00 at $500,000 and $41,332.50 at $501,000, and $40,425.00 at $490,000. The proportion holds at every scale: $8,250.00 at $100,000, $82,500.00 at $1,000,000 and $412,500.00 at the $5,000,000 enterprise scenario. Effective rate and marginal rate are both 8.25% at all of those, which is the practical definition of a flat schedule.
Right method against wrong method, priced. A $10,000 credit and $10,000 of extra deductible expense are not equivalent, and the gap is the whole reason credits are negotiated rather than deductions. Entering $10,000 in the credit field against $500,000 of income takes the engine's output from $41,250.00 to $31,250.00, a saving of exactly $10,000.00, and the reported effective rate falls from 8.25% to 6.25% while the marginal rate stays at 8.25%. Reducing taxable income by $10,000 instead, to $490,000, takes the tax to $40,425.00, a saving of only $825.00. The credit is worth 12.1 times the deduction at Maryland's rate.
The reverse question. How much income can be earned before Maryland tax reaches a target? A $41,250.00 bill corresponds to exactly $500,000 of apportioned income, and each further $10,000 of tax tolerance corresponds to $121,212 of income. Working the other way, a corporation holding $41,250.00 of credits pays $0.00 on $500,000 of income.
Where the credit field stops behaving. The engine computes net tax as the greater of zero and tax less credits, so credits in excess of the liability simply vanish from the calculation. A corporation entering $50,000 of credits against $500,000 of income sees $0.00 of tax rather than a $8,750 carryforward or refund, and the effective rate output reads 0.00%. Maryland's actual credit statutes differ in whether a credit is refundable, carried forward, or lost, and none of that logic exists in this code path.
Two things the flat rate does not include. The engine applies one rate to whatever apportioned figure is entered; it performs no apportionment itself, so the single most consequential number in a multistate Maryland filing is an input rather than a computation. It also has no representation of Maryland's separate pass-through entity tax election, which is a different rate on a different base and is not what the $41,250.00 above measures.
What This Does Not Account For
- Federal Taxable Income Starting Point. Net corporate earnings are determined under IRC § 63 before Maryland modifications. This calculator starts one step later: the income box is read as the finished Maryland taxable figure and nothing is derived from a federal return.
- Maryland Additions & Subtractions. The Maryland tax deducted federally is added back, and Maryland applies decoupling modifications for federal depreciation and expensing provisions it has not adopted. No addback and no subtraction is computed anywhere in this page's code path, so enter an income figure that already reflects them.
- Apportionment Factor Allocation. Maryland apportions on a single sales factor for most taxpayers, following a phase-in completed in recent years; worldwide headquartered companies may elect a three-factor formula. The engine performs no apportionment of any kind. The word does not appear in the primitive this page binds to; the figure you type is taken as the Maryland figure and multiplied by the rate as it stands.
- Net Operating Loss (NOL) Deductions. Allowable Maryland NOL carryforwards reduce the base before the rate is applied. No loss deduction is applied by this calculator. If a carryforward is available, subtract it yourself before entering the income.
- Separate-Entity Filing Verification. Because Maryland files separate-entity returns, each member of a group computes its own Maryland liability, and intercompany transactions are tested against the state's addback rules rather than eliminated. No group, election or filing-method test is applied here. The code reads one income figure and one credit figure and nothing else.
- Federal corporate income tax (21% under IRC § 11).
- Specialized gross receipts taxes (e.g. Ohio CAT, Washington B&O, Texas Franchise Tax) where applicable.
- Minimum entity franchise tax fees or annual report filing charges.
- Base Erosion and Anti-Abuse Tax (BEAT) or Global Intangible Low-Taxed Income (GILTI) provisions.
- Local municipal corporate earnings taxes (e.g. NYC General Corporation Tax).
Common Pitfalls
- Mistaking the Flat Rate for the Final Bill: Assuming Maryland's 8.25% rate applies directly to book income rather than to apportioned taxable income after state additions, subtractions, and NOL adjustments.
- Improper Apportionment Sourcing: Applying market-based sourcing vs cost-of-performance rules incorrectly for service revenue apportioned to Maryland.
- Ignoring Unitary Group Combined Reporting: Failing to account for Maryland's mandatory combined return requirements across related entities.
- Neglecting State NOL Carryforward Caps: Overlooking Maryland's annual percentage limitations on net operating loss deductions, which carry outsized weight given the 8.25% rate applied to whatever base survives them.
Frequently Asked Questions
Does Maryland have a corporate income tax?
When are Maryland corporate tax returns due?
Does Maryland tax S-corporations and LLCs?
How is multi-state corporate income apportioned to Maryland?
Sources
- Comptroller of Maryland: Corporate Tax Statutes and Guidance (2026). marylandtaxes.gov
- Multistate Tax Commission (MTC): Uniform Apportionment and Allocation Guidelines. mtc.gov