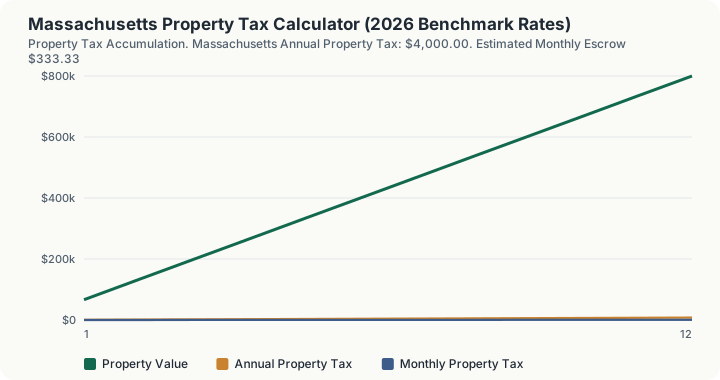
Quick Answer: A $400,000 home in Massachusetts carries an estimated $4,000.00 in annual property tax at the state's 1.00% effective rate, or about $333.33 a month.
Massachusetts at 1.00% and Rank #19
Massachusetts's average effective property tax rate of 1.00% works out to a #19 national ranking, above the national median. Measured against the roughly 1.0% average effective rate nationwide, Massachusetts's number lines up almost exactly with the national average. Within the Northeast, where the average effective rate runs near 1.61%, Massachusetts sits well below the regional norm.
For buyers and investors evaluating Massachusetts real estate, that rate is not just a sticker number: it funds the local school district, county services, and municipal budget that shape a property's long-run carrying cost and its resale economics.
County assessors in Massachusetts carry out the periodic valuations that feed into the millage calculation, and the exemption and appeal process outlined further down this page is the practical way an individual owner can influence the final number on next year's bill rather than simply accepting the county's first estimate.
How This Is Calculated
Proposition 2½ governs Massachusetts property tax from the town's side rather than the parcel's. A municipality's total levy cannot exceed 2.5% of the assessed value of all taxable property in it, and the levy cannot grow more than 2.5% a year without a voter override. The rate falls out of that ceiling.
None of that detail is asked for here. This calculator works one level up, applying Massachusetts's average effective property tax rate of 1.00% to the value you enter. That rate is the ratio of property taxes actually paid to home value across the state, so the assessment ratios, caps, and exemptions described above are already baked into it.
Working through it in order:
- Start from full and fair cash value. Assessors value at 100% of market value and certify values every five years.
- Account for classification and exemptions. Communities may shift part of the levy onto commercial and industrial property, and residential exemptions apply where adopted.
- Multiply by the effective rate. At 1.00%, a $400,000 home in Massachusetts comes to $4,000 a year before any exemption you enter above.
- Divide by twelve for escrow. That same home works out to $333.33 a month set aside in a mortgage escrow account.
- Compare it against your own bill. Because the town's total levy is capped, a rising market pushes the tax rate down rather than every bill up. Your county's number is the one that governs; this figure tells you whether it is roughly where a Massachusetts home of that value ought to land.
Worked Example
Using this calculator's baseline inputs: a $400,000 home in Massachusetts, taxed at the state's 1.00% average effective rate (rank #19 of 50 states).
- Start with the assessed value. The home is assessed at its full $400,000.00 market value, with no homestead exemption applied in this baseline scenario.
- Apply the effective rate. $400,000.00 × 1.00% = $4,000.00 in annual property tax, Massachusetts's statewide average effective rate.
- Convert to a monthly escrow. Lenders typically collect property tax in twelve equal installments alongside principal and interest: $4,000.00 ÷ 12 = $333.33 per month.
- Project a five-year hold. At a flat rate, five years of ownership totals $4,000.00 × 5 = $20,000.00, before any reassessment, exemption change, or millage increase.
At 1.00%, Massachusetts lands roughly in the middle nationally, ranking #19 of 50 states. That is a moderate but still material carrying cost for homeowners.
What $25,000 of Exemption Buys, and Where the Sweep Ignores It
The engine multiplies taxable value by a single effective rate of 1.00%, so the twelve-row value sweep is a straight line with no threshold in it. The three questions it can answer are what the exemption is worth, what a change in value costs, and what value hits a target escrow figure.
Pricing the exemption. On the baseline $400,000 home the engine returns $4,000.00 a year with no exemption, or $333.33 a month. Apply the calculator's $25,000 homestead scenario and it returns $3,750.00 a year, or $312.50 a month. The exemption is therefore worth exactly $250.00 a year in Massachusetts, which is $25,000 multiplied by the 1.00% rate. That figure scales with the exemption and not with the home: a $25,000 exemption saves $250.00 on a $300,000 home and on a $3,000,000 home alike.
The marginal cost of the next unit. Each additional $10,000 of assessed value costs $100.00 a year. The engine returns $4,000.00 at $400,000 and $4,100.00 at $410,000. At $300,000 the annual bill is $3,000.00 and the monthly escrow $250.00; at $500,000 they are $5,000.00 and $416.67. There is no bracket anywhere in the sweep, so the cost per $10,000 is identical at the bottom and the top of the range.
The reverse question. Buyers usually work from an escrow ceiling rather than a tax figure. Holding the monthly Massachusetts escrow to $250.00 a month, or $3,600 a year, means an assessed value of $360,000.00, which the engine confirms exactly. Every further $100 a month of escrow tolerance corresponds to about $120,000 of additional assessed value.
Where the sweep table and the headline disagree. The twelve-row schedule steps assessed value from one sixth to two times the value entered, but it computes each row from the raw value, not from the value after the homestead exemption. Set the exemption to $25,000 and the headline drops to $3,750.00 while row 6 of the table, which sits at the entered $400,000, still reads $4,000.00. The gap is the $250.00 the exemption is worth, and it appears in every row of the table. The table is the correct answer to "what would this cost with no exemption at each value"; it is not a projection of the exempted bill.
A Massachusetts-specific caution about the exemption field. The Massachusetts Homestead Declaration under M.G.L. c. 188 is creditor protection and reduces no tax at all, so entering it here would credit a saving that does not exist. What does reduce a bill is the local-option Residential Exemption offered by roughly seventeen municipalities including Boston, Cambridge and Somerville, and the Senior Circuit Breaker, a refundable state income tax credit rather than a property tax reduction. The engine models none of these mechanisms; it subtracts whatever dollar figure is entered, which is why the $250.00 above should be read as an illustration of scale rather than as any named programme.
What the single rate cannot express. 1.00% is a statewide average effective rate, and Massachusetts sets millage locally, so no individual parcel is taxed at exactly this figure. The engine holds one number per state, has no field for county or municipality, and applies no reassessment schedule of any kind. The rank of #19 of 50 is likewise a stored figure rather than something recomputed from the other 49 states inside this page.
What This Does Not Account For
- Specific hyper-local county and municipal millage district variations within Massachusetts.
- Betterment assessments. Massachusetts cities and towns can levy a one-time betterment assessment under M.G.L. Chapter 80 on properties whose value is improved by a new public sewer or road, payable in a lump sum or amortized over up to 20 years on top of the regular tax bill.
- Commercial vs residential assessment classification differentials.
- Property tax appeal reductions or localized board of equalization adjustments.
Common Pitfalls
- Confusing Market Fair Value with Assessed Basis: Some jurisdictions assess property at fractional ratios rather than 100% of market value.
- Failing to File Homestead Paperwork: Homestead exemptions are rarely automatic; homeowners must file timely paperwork with the county appraisal district.
- Underestimating Post-Sale Supplemental Assessments: Purchasing a newly constructed or reassessed property often triggers catch-up supplemental tax bills.
- Ignoring Property Tax Appeal Windows: Missing the annual 30-to-60 day statutory protest window forfeits the right to challenge over-assessed property values for that tax year.
Frequently Asked Questions
How high are property taxes in Massachusetts?
When are property taxes due in Massachusetts?
How can I lower my property taxes in Massachusetts?
Does purchasing a home trigger a property tax reassessment?
Sources
- U.S. Census Bureau: American Community Survey (ACS) Real Estate Assessment Benchmark Data. census.gov/programs-surveys/acs
- Massachusetts Department of Revenue, Division of Local Services: Assessment Ratio Manuals. mass.gov/orgs/massachusetts-department-of-revenue