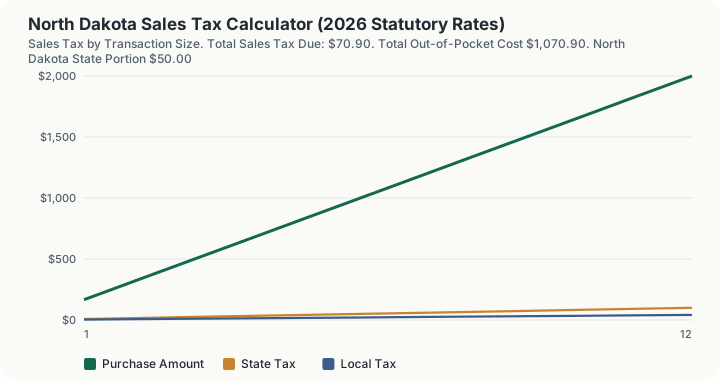
Quick Answer: A $1,000 taxable purchase in North Dakota costs $70.90 in combined state and local sales tax, for a total of $1,070.90 out the door.
Five Percent, Plus City And County Options
Retailers doing business in North Dakota collect sales tax in two pieces at once: the state's 5.00% statutory rate, and whatever the local jurisdiction adds on top. Local jurisdictions (cities, counties, and in some cases special taxing districts) are free to add their own surcharges on top of that, and the statewide average of those add-ons is 2.09%, which brings the typical combined rate to 7.09%.
Getting that combined figure wrong, even by a fraction of a percentage point, creates exposure at audit time, since the state and any local taxing authority both expect their share to be collected and remitted correctly. That leaves North Dakota a bit below the roughly 7.3% average combined rate seen across the states that levy a general sales tax. New sellers registering to collect tax in North Dakota for the first time typically need the state-level number to open an account with the revenue department, and the local add-on on top of it to actually invoice customers correctly from day one.
How This Is Calculated
North Dakota charges 5.00% at the state level with city and county taxes averaging 2.09%, giving a combined 7.09% and $70.90 on a $1,000 purchase. The feature that distinguishes North Dakota is the local refund cap: many North Dakota cities cap the amount of local tax collectible on a single transaction, so above a certain purchase price the local tax stops growing and the buyer can claim a refund of the excess. That makes the effective combined rate on large purchases lower than the posted rate.
Below the cap, state and local rates apply to the same amount:
The order is:
- Read the purchase price. The full pre-tax amount you enter becomes the taxable base.
- No item-level exemption filtering and no local maximum tax cap. For large single transactions the local portion shown here will exceed what a capped city actually collects.
- Multiply by the state rate. This produces the state portion of the bill.
- Apply the local surcharge. The 2.09% average covers city and county taxes; the caps that limit them apply per transaction, not per year.
- Add the pieces together. State tax plus local tax gives the total tax, and adding that to the purchase price gives the amount you actually pay.
Worked Example
For a $1,000 taxable purchase in North Dakota:
- Starting purchase price. The buyer rings up a $1,000.00 taxable retail purchase in North Dakota, the baseline amount before any tax is applied.
- State portion. North Dakota's statutory state sales tax rate of 5.00% applies to the full purchase amount: $1,000.00 × 5.00% = $50.00 owed to the state.
- Local portion. Local municipal, county, and special-district surcharges add an average of 2.09% on top of that: $1,000.00 × 2.09% = $20.90 more.
- Combined tax due. Summing the two pieces, $50.00 in state tax plus $20.90 in local surcharge comes to $70.90 in total sales tax owed on the transaction.
- Total out-of-pocket cost. Adding that $70.90 in tax to the $1,000.00 purchase price brings the buyer's total out-of-pocket cost to $1,070.90.
This example uses North Dakota's statewide average local rate of 2.09%; actual combined rates vary by city and county, so a real receipt could show a combined rate above or below the 7.09% average used here.
Two Ways To Split A North Dakota Receipt, One Of Them Wrong
North Dakota's 5.00% state rate carries a 2.09% average local option on top, and the engine applies the combined 7.09% linearly across the whole twelve-row sweep.
The marginal cost of the next unit. Raising the purchase from $1,000.00 to $1,100.00 moves the tax from $70.90 to $77.99. Every additional $100.00 of taxable spending costs exactly $7.09, and the twelve-row sweep confirms it: each row adds $166.67 of purchase and the state and local columns rise in fixed proportion from row one through row twelve. At $35,000.00 the tax is $2,481.50, split $1,750.00 to the state and $731.50 to local jurisdictions, for a total out-of-pocket cost of $37,481.50.
Right method against wrong method, and this is the error that matters. People routinely need to work backwards from a receipt total to separate the price from the tax. The wrong method subtracts the combined rate from the total: 7.09% of $1,000.00 is $70.90. The right method extracts the tax fraction, because the 7.09% was charged on the pre-tax price and not on the total. Entering $933.79 into this calculator returns $66.21 of tax and a total out-of-pocket cost of exactly $1,000.00, which is the correct decomposition.
What the error costs. Deducting 7.09% from a tax-inclusive $1,000.00 total rather than extracting the fraction overstates the tax by $4.69 and understates the pre-tax price by the same amount. On a $35,000.00 tax-inclusive figure the same mistake is 35 times larger. A business reclaiming or remitting on the wrong base repeats the error on every transaction of the period.
The reverse question: how much can be bought for a fixed budget? A $1,000.00 out-the-door budget buys $933.79 of goods in North Dakota, with $66.21 going to tax. The calculator confirms it directly: enter $933.79 and the total out-of-pocket cost output reads exactly $1,000.00, split $46.69 to the state and $19.52 to local jurisdictions. Scale that ratio for any budget, because the combined 7.09% has no cap and no threshold to break the proportion.
The state-only view, and what it is for. Switching the local surcharge off returns $50.00 on the same $1,000.00 purchase against $70.90 with it on. The difference, taken across the twelve-row sweep, is the entire contribution of local jurisdictions: at 5.0% state and 2.09% average local, local government collects less on every transaction than the state does. That toggle is the only structural switch on this page; there is no bracket, no cap and no threshold anywhere in the combined rate.
What the combined rate conceals. The 2.09% is a statewide average of city and county local option taxes, several of which cap the tax on a single transaction at a maximum refundable amount. The engine models no such cap, so the $2,481.50 shown on a $35,000 purchase overstates the bill in every jurisdiction that applies one. North Dakota's exemptions for groceries and prescription drugs are not modelled either, and no county table exists in this code path.
What This Does Not Account For
- Statutory exemptions on unprepared groceries, prescription medications, or manufacturing equipment.
- Special industry excise taxes (lodging hotel taxes, vehicle rental fees, alcohol/tobacco excise).
- Use tax compliance on out-of-state untaxed online purchases.
- B2B resale certificate exemptions or direct pay permit programs.
Common Pitfalls
- Confusing State and Combined Rates: Quoting the state base rate without factoring in local city and county add-on taxes.
- Overlooking Consumer Use Tax: Failing to self-report and remit use tax on untaxed out-of-state purchases on your state income tax return.
- Missing Annual Sales Tax Holidays: Many states offer annual tax-free weekends for back-to-school items, severe weather supplies, or energy-efficient appliances.
- Failing to Collect Resale Certificates: Selling wholesale without collecting valid exemption certificates exposes sellers to full sales tax liability upon audit.
Frequently Asked Questions
What is the sales tax rate in North Dakota?
Are groceries taxed in North Dakota?
How does use tax differ from sales tax?
Are digital goods and SaaS taxable in North Dakota?
Sources
- North Dakota Office of State Tax Commissioner: 2026 Sales and Use Tax Rate Schedules. tax.nd.gov
- Streamlined Sales Tax Governing Board (SSTGB): State Taxability Matrix. streamlinedsalestax.org/for-businesses/taxability-matrix