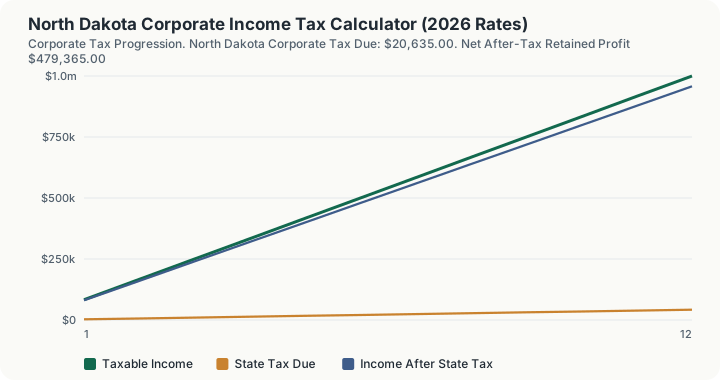
Quick Answer: On $500,000 of pre-apportioned taxable income, North Dakota's graduated corporate income tax brackets (reaching 4.31% at this income level) produce $20,635.00 in state tax due and $479,365.00 in net after-tax profit.
Three Corporate Brackets, All Below $50,000
North Dakota runs a three-bracket graduated schedule that starts unusually low: 1.41% on the first $25,000 of apportioned income, rising to 3.55% on the next tier up to $50,000, before reaching the 4.31% top rate above that.
North Dakota's 4.31% top rate is the second-lowest of any graduated-bracket state in this dataset, just above Arkansas's 4.30%. Combined with the modest $25,000 and $50,000 thresholds, most corporations with meaningful North Dakota-sourced income will face the 4.31% marginal rate on the majority of their earnings, even though the state's lowest bracket, 1.41%, is one of the smallest starting rates in the country.
Running $500,000 through North Dakota's three brackets produces a 4.13% effective rate, below the 4.31% top bracket reached at that income level. The state's very low $25,000 and $50,000 thresholds mean most of a typical filer's income still lands in the 4.31% tier, keeping the effective and marginal rates relatively close.
How This Is Calculated
North Dakota keeps a graduated schedule with unusually precise rates, 1.41%, 3.55%, and 4.31%, set that way by a legislated across-the-board reduction rather than chosen as round numbers. The brackets are narrow, so most filers of any size are effectively paying close to the 4.31% top rate on the bulk of their income.
where $c_i$ are the bracket ceilings ($25{,}000$, $50{,}000$, then unlimited) and $r_i$ the corresponding rates ($1.41\%$, $3.55\%$, $4.31\%$).
- Read the income field as the taxable base. The single income input is taken as North Dakota taxable corporate income exactly as typed. The code applies no modification, allocation or deduction to it before the rate stage; it is the base.
- Walk the bracket schedule slice by slice. Each band is charged only on the income that falls inside it and the pieces are summed: 1.41% on the slice from $0 to $25,000 ($25,000 of the entered income, $352.50); 3.55% on the slice from $25,000 to $50,000 ($25,000 of the entered income, $887.50); 4.31% on the slice from above $50,000 ($450,000 of the entered income, $19,395.00). On $500,000 that totals $20,635.00.
- Subtract credits and floor the result at zero. The credits field is subtracted from the step-2 figure and the difference is clamped at $0.00, so no credit entry can drive the liability negative. With the field at its $0 default the $20,635.00 stands; enter $8,000 of credits and the page returns $12,635.00, a reduction of exactly the credit entered because the subtraction is a straight one.
- Derive the reported rates from those two numbers. The effective rate is the tax divided by the income entered, 4.13% here, and the top statutory bracket is reported separately as 4.31%. Net after-tax retained profit is the income less the tax, $479,365.00. Those four outputs are the whole of what the engine produces.
Worked Example
Using this calculator's baseline scenario: a corporation with $500,000 in taxable income apportioned to North Dakota.
- Start with apportioned taxable income. The corporation has $500,000 of taxable income apportioned to North Dakota before state tax is applied.
- Work through North Dakota's bracket schedule. North Dakota taxes corporate income progressively: each slice of income is taxed only at the rate for its own bracket rather than the entire amount being taxed at the top rate, so lower brackets are filled first and the marginal rate rises step by step as income climbs.
- Marginal rate reached at this income level. At $500,000 of taxable income, the highest bracket reached is 4.31%.
- Sum the marginal brackets. Adding together the tax owed within every bracket the $500,000 passes through produces a total North Dakota state tax liability of $20,635.00.
- Net retained profit. $500,000 − $20,635.00 = $479,365.00 retained after state tax, before any separate federal tax liability.
Because the calculation sums each bracket's marginal tax rather than applying one flat rate to the whole amount, the resulting effective rate (4.13%) is always lower than the top marginal bracket actually touched.
Both Of North Dakota's Corporate Bracket Edges, Walked
North Dakota is one of the few states left with a genuinely graduated corporate schedule, and both of its edges sit low enough that most filers clear them in the first month of the year. The sweep crosses each in turn.
At $25,000 of apportioned income. The whole amount has been taxed at 1.41%. The tax is $352.50, an effective rate of 1.41%, and the marginal rate still reads 1.41%.
At $25,100, one hundred dollars later. The last $100 lands in the 3.55% band. The tax is $356.05 and the marginal rate becomes 3.55%. Crossing costs $3.55 per $100 against $1.41 a moment earlier, more than doubling the marginal charge.
At $50,000. The tax is $1,240.00, an effective rate of 2.48%, with the marginal rate at 3.55%.
At $50,100. The tax is $1,244.31 and the marginal rate becomes 4.31%. That is North Dakota's last edge; every dollar of corporate income above $50,000 is charged at 4.31% and the schedule never steps again.
The marginal cost of the next unit. At the baseline, raising apportioned income from $500,000 to $510,000 moves the tax from $20,635.00 to $21,066.00. Each additional $1,000 costs exactly $43.10 at any income above $50,000.
The reverse question: what is the graduated structure worth? A flat 4.31% on the $500,000 baseline would be $21,550.00 against the engine's $20,635.00, so the two lower brackets are worth $915.00 a year. They are worth exactly $915.00 at $5,000,000 too, where the engine returns $214,585.00 and the effective rate has crept to 4.29%. The relief is a fixed dollar amount, not a percentage, and it becomes negligible as income grows.
Right method against wrong method. Applying North Dakota's 4.31% top rate to the whole $500,000 gives $21,550.00, overstating the bill by the $915.00 above. The opposite error costs far more: applying the 1.41% entry rate to the whole $500,000 gives $7,050.00 and understates the liability by $13,585.00.
What the engine does not do. It applies no North Dakota net operating loss carryforward, computes no apportionment, and models neither the state's water's-edge election nor its treatment of foreign dividend income. The credit field is a flat subtraction floored at zero: $20,635 of entered credits leaves $0.00, and a dollar more is silently dropped.
What This Does Not Account For
- Federal Taxable Income Starting Point. Net corporate earnings are determined under IRC § 63 before North Dakota modifications. This calculator starts one step later: the income box is read as the finished North Dakota taxable figure and nothing is derived from a federal return.
- North Dakota Additions & Subtractions. The North Dakota tax deducted federally is added back, and the state applies its own depreciation and interest adjustments. No addback and no subtraction is computed anywhere in this page's code path, so enter an income figure that already reflects them.
- Apportionment Factor Allocation. North Dakota follows UDITPA and apportions business income across property, payroll, and sales, with elections available for certain water's-edge and worldwide filers. The engine performs no apportionment of any kind. The word does not appear in the primitive this page binds to; the figure you type is taken as the North Dakota figure and multiplied by the rate as it stands.
- Net Operating Loss (NOL) Deductions. Allowable North Dakota NOL carryforwards reduce the base before the bracket walk begins. No loss deduction is applied by this calculator. If a carryforward is available, subtract it yourself before entering the income.
- Federal corporate income tax (21% under IRC § 11).
- Specialized gross receipts taxes (e.g. Ohio CAT, Washington B&O, Texas Franchise Tax) where applicable.
- Minimum entity franchise tax fees or annual report filing charges.
- Base Erosion and Anti-Abuse Tax (BEAT) or Global Intangible Low-Taxed Income (GILTI) provisions.
- Local municipal corporate earnings taxes (e.g. NYC General Corporation Tax).
Common Pitfalls
- Overestimating the Low Starting Bracket's Effect: Assuming North Dakota's 1.41% first-tier rate meaningfully lowers the overall bill, when the low $25,000 and $50,000 thresholds mean most filers' income still lands mainly in the 4.31% top tier.
- Improper Apportionment Sourcing: Applying market-based sourcing vs cost-of-performance rules incorrectly for service revenue apportioned to North Dakota.
- Ignoring Unitary Group Combined Reporting: Failing to account for North Dakota's mandatory combined return requirements across related entities.
- Neglecting State NOL Carryforward Caps: Overlooking North Dakota's annual percentage limitations on net operating loss deductions, which shift where a filer's income lands within the 1.41%/3.55%/4.31% brackets.
Frequently Asked Questions
Does North Dakota have a corporate income tax?
When are North Dakota corporate tax returns due?
Does North Dakota tax S-corporations and LLCs?
How is multi-state corporate income apportioned to North Dakota?
Sources
- North Dakota Office of State Tax Commissioner: Corporate Tax Statutes and Guidance (2026). tax.nd.gov
- Multistate Tax Commission (MTC): Uniform Apportionment and Allocation Guidelines. mtc.gov