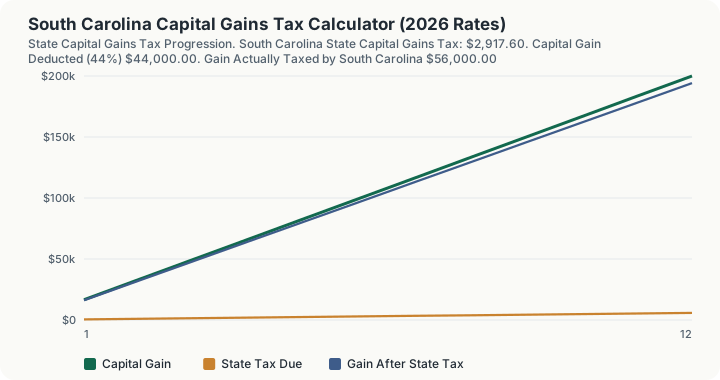
Quick Answer: On a $100,000 long-term capital gain layered on $75,000 of other income, South Carolina's tax is $2,917.60, an effective rate of 2.92%. South Carolina deducts 44% of net capital gain under S.C. Code Ann. § 12-6-1150, so only $56,000 of the gain reaches the brackets. Without the deduction the bill would be $5,210.00.
The 44% Deduction and the Two-Band Schedule
South Carolina grants a 44% deduction for net capital gain. Under S.C. Code Ann. § 12-6-1150, a taxpayer who realizes net capital gain on assets held for the long-term holding period deducts 44% of that gain from state taxable income, so only 56% of it is exposed to the graduated brackets. Under H. 4216, signed 30 March 2026 and effective for tax year 2026, the schedule is two rates: 1.99% below $30,000 of taxable income and 5.21% at $30,000 and above. A long-term gain that lands entirely in the upper band therefore carries an effective state rate of 2.92%, not 5.21%.
The deduction applies to long-term gain only. Short-term gain, on assets held one year or less, gets no deduction and is taxed as ordinary income at the full graduated rates.
Because the state stacks capital gains on top of your other income rather than taxing them separately, a gain realized alongside salary or business income typically lands in your highest bracket, up to that 5.21% ceiling.
How This Is Calculated
South Carolina grants the largest straightforward capital gains break of any state that taxes income: a deduction of 44% of net long-term capital gain, so only 56% of a qualifying gain ever reaches the brackets. Against the 5.21% upper band set by H. 4216 for tax year 2026, that pulls the effective ceiling on long-term gain down to 2.92%, which is exactly what the calculator returns on the default $100,000 gain. Short-term gain gets no deduction and meets the full schedule.
The deduction comes off first, before the remaining gain is stacked on other income and bracketed.
The order of operations matters, so here it is in full:
- Start with the net gain. Capital losses and loss carryforwards are netted against the gain before anything else happens.
- Take the 44% deduction (S.C. Code Ann. § 12-6-1150). Subtract 44% of the net long-term gain first, before anything is stacked or bracketed, leaving 56% of it in the state tax base. On the $100,000 default that removes $44,000 and leaves $56,000.
- Stack what remains on your other income. Ordinary income fills the lower brackets first and the reduced gain sits on top of it, so it is taxed at whatever rates are still open above your salary. The same gain costs a high earner more than it costs a low earner: at $0 of other income the default gain costs $1,951.60, at $30,000 it costs $2,917.60. Enter other income as a taxable-income figure, because the calculator does not subtract a standard deduction or personal exemption for you.
- Walk the brackets. The slice of the gain that falls in each band is multiplied by that band's rate, and the pieces are added together.
- Effective rate. Total South Carolina tax divided by the whole realized gain. On a graduated schedule this sits below the top marginal rate, because the lower slices were taxed at lower rates.
- Net proceeds. Subtract the state tax from the gain to get what you keep before federal tax.
Worked Example
Consider an investor in South Carolina who realizes $100,000 in capital gains on top of $75,000 in baseline ordinary income for the year.
- Apply the 44% deduction first. S.C. Code Ann. § 12-6-1150 removes 44% of the $100,000 net capital gain, or $44,000, from state taxable income. $56,000 of gain remains.
- Stack the income. The $75,000 of baseline ordinary income fills the lower brackets first, so the remaining $56,000 of gain stacks on top of it.
- Apply the marginal brackets. The $75,000 of other income already carries past the $30,000 threshold of the upper band, so the entire $56,000 of taxable gain sits in the 5.21% band: 5.21% x $56,000 = $2,917.60.
- Effective rate. Dividing $2,917.60 by the full $100,000 realized gain gives an effective rate of 2.92%, well under the 5.21% top marginal rate, because the deduction takes 44% of the gain off the table.
- Net proceeds. After paying $2,917.60 in state tax, the investor keeps $97,082.40 of the $100,000 gain, before any federal tax applies.
Had the gain been short-term, no deduction would apply and the full $100,000 would be taxed at 5.21%, producing $5,210.00, the figure that a calculator ignoring § 12-6-1150 reports.
Pricing the 44% Deduction, and Finding the $30,000 Edge
The deduction and the bracket edge pull in opposite directions, and the calculator lets both be priced exactly.
Right method against wrong method, priced
The mistake here is not subtle arithmetic, it is skipping S.C. Code Ann. § 12-6-1150 entirely and running the whole gain through the brackets.
Right: the deduction first. On the $100,000 default the calculator deducts $44,000, leaving $56,000 in the state base. With $75,000 of other income already past the $30,000 threshold, all $56,000 sits in the 5.21% band, and the tax is $2,917.60, an effective 2.92%.
Wrong: 5.21% on the whole gain. The engine will price this too, because feeding it a gain of $178,571.43 leaves exactly $100,000 after the 44% deduction, and it returns $5,210.00 on that base.
The error: $2,292.40 overpaid on a single $100,000 long-term sale, which is 78.6% more tax than the statute asks for. That is also the exact figure a short-term seller pays, since the deduction is a long-term provision and this calculator has no holding-period input to distinguish the two.
The $30,000 edge, walked
The $30,000 threshold is on taxable income after the deduction, so a filer with no other income does not meet it until the gain reaches $53,571.43. Sweeping the gain with other income set to $0:
At a gain of $53,000 the state base is $29,680, all inside the 1.99% band, and the tax is $590.63. At a gain of $54,000 the base is $30,240 and the tax is $609.50, an increment of $18.87 for that $1,000. At $55,000 the tax is $638.68, an increment of $29.18.
So the $1,000 that straddles the edge costs $18.87, and every $1,000 after it costs $29.18, against $11.14 for each $1,000 below the edge. The step in the marginal cost of gain is $18.04 per $1,000, and the calculator's marginal-rate output flips from 1.99% to 5.21% at a gain of exactly $53,571.43 while the tax at that point, $597.00, is the same figure SCDOR's own two forms of the schedule agree on.
The cost of the next $1,000
At the default inputs the sweep gives $2,917.60, $2,946.78, $2,975.95, $3,005.13. Each additional $1,000 of long-term gain costs $29.18, not $52.10, because only $560 of that $1,000 survives the deduction. Below the edge, where the 1.99% band still applies, the same $1,000 costs $11.14.
How much gain fits under the threshold
For a filer with no other income, $53,571.43 of long-term gain can be realised before any of it is taxed above 1.99%, and the whole of that gain costs $597.00. Other income eats that room dollar for dollar: sweeping other income across $0, $15,000, $30,000, $45,000 and $60,000 returns $1,951.60, $2,434.60, $2,917.60, $2,917.60 and $2,917.60. The bill rises by $483.00 for each $15,000 of salary until salary alone reaches $30,000, and then it stops moving entirely, because the threshold has been fully consumed and the whole gain is in the upper band no matter how much more is earned. Above $30,000 of other income, this calculator's other-income field has no further effect on the answer.
Limitations of this page, plainly
The calculator applies the 44% deduction to whatever gain you enter. It collects no holding period, so it cannot tell long-term gain from short-term gain, and a short-term seller reading the headline figure of $2,917.60 is being shown a number $2,292.40 too low. It also does not model the new SC Income Adjusted Deduction introduced by the same act as the rate change ($15,000 single, $30,000 joint, reduced by income), nor the decoupling to federal AGI as the starting point, so a filer near the $30,000 threshold has more room in practice than this page shows. Filing status is collected but does not change the answer: running the defaults as married filing jointly also returns $2,917.60, which is correct, because SC1040TT states that one schedule is used for any filing status.
What This Does Not Account For
While this calculator provides penny-exact state statutory modeling, additional federal and transactional complexities warrant supplementary review: - Federal Capital Gains Taxes: Federal long-term brackets (0%, 15%, 20%) and short-term ordinary rates up to 37% under IRC § 1. - Net Investment Income Tax (NIIT): The 3.8% surtax on net investment income under IRC § 1411 for single filers over $200,000 (married joint over $250,000). - Alternative Minimum Tax (AMT): Federal AMT calculations under IRC § 55 impacting incentive stock option (ISO) exercise spread. - Section 1031 Like-Kind Exchanges: Tax deferral mechanisms for real property held for productive use in trade, business, or investment. - Qualified Small Business Stock (QSBS): Federal Section 1202 gain exclusions where state conformity varies significantly.
Common Pitfalls
- Overpaying by Skipping the 44% Deduction: South Carolina is not a state that taxes capital gains at flat ordinary rates. On the default $100,000 long-term gain the calculator returns $2,917.60; taxing the whole gain at 5.21% gives $5,210.00. Failing to claim the S.C. Code Ann. § 12-6-1150 deduction therefore costs $2,292.40 on that sale.
- Failing to Track Holding Periods: The 44% deduction applies only to gain held for the long-term holding period. Assets held one year or less get no deduction at the state level and carry higher federal rates on top of that.
- Underestimating Multi-State Apportionment: Selling real estate or business assets located in other jurisdictions triggers multi-state non-resident return filing obligations.
- Neglecting Underpayment Penalties: Substantial one-time liquidity events require prompt estimated tax payments within the quarter of sale to avoid statutory penalties.
- Mismatched Cost Basis Records: Failure to document reinvested dividends, stock splits, or structural return-of-capital distributions leads to inflated taxable gain calculations.
Frequently Asked Questions
Does South Carolina have a state capital gains tax?
How are short-term and long-term capital gains taxed in South Carolina?
Are retirement account distributions subject to capital gains tax in South Carolina?
Can capital losses offset capital gains in South Carolina?
When are estimated state tax payments required on capital gains?
Does filing status change the South Carolina tax on a capital gain?
Sources
- South Carolina Department of Revenue: 2026 Statutory Individual Income Tax Rate Schedules. dor.sc.gov
- Internal Revenue Service (IRS): Publication 544 (Sales and Other Dispositions of Assets) and Publication 550 (Investment Income and Expenses). irs.gov/publications/p544
Also consulted: S.C. Code Ann. § 12-6-1150: 44% deduction for net capital gain held for the long-term holding period.