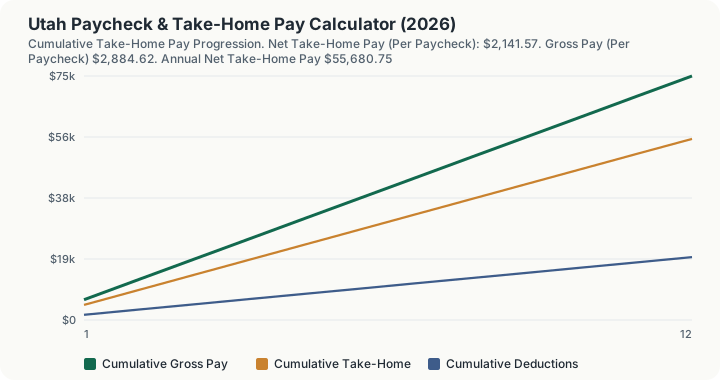
Quick Answer: A $75,000 annual salary in Utah, paid bi-weekly and filing single, takes home about $2,141.57 per paycheck ($55,680.75 per year) after federal tax, FICA, and Utah state withholding.
Overview
Utah applies a single flat income tax rate to wages, 4.45% for 2026, with no brackets to climb through and no tiers based on income level. That flat structure means every dollar of taxable wages gets taxed at the same rate here, unlike states running graduated brackets where the effective rate shifts as income rises. This calculator applies verified 2026 figures to compute the complete withholding picture, including Social Security and Medicare, federal income tax brackets, Utah's flat state tax, and how pre-tax elections like a 401(k) or HSA contribution change the wages those taxes get calculated against. It covers bi-weekly, semi-monthly, monthly, and weekly pay schedules, because the same annual salary produces different per-paycheck totals depending on how often you're paid. Salaried employees comparing offers, hourly workers estimating a raise, and payroll staff processing new hires all rely on the same underlying arithmetic. A flat rate simplifies the state portion of the calculation, but federal withholding, FICA, and pre-tax elections still add enough moving parts that an exact figure beats a rough estimate every time.
How This Is Calculated
Utah applies a single 4.45% rate to all taxable income and this calculator applies that rate and nothing else on the state side. No Utah city levies a wage tax. The paycheck arithmetic:
Four steps produce the number on the check:
- FICA Payroll Tax Computation: - Social Security (OASDI): 6.20% withheld on wages up to the 2026 statutory wage base ($184,500). - Medicare (HI): 1.45% withheld on all gross earnings (no wage cap), plus 0.90% Additional Medicare Tax on earnings exceeding $200,000 (single) or $250,000 (married filing jointly).
- Federal Income Tax Withholding: Evaluated using 2026 progressive federal tax brackets (10%, 12%, 22%, 24%, 32%, 35%, 37%) after applying standard deduction thresholds ($16,100 single / $32,200 married joint).
- Utah State Income Tax Withholding: A flat 4.45% applied to 2026 Utah taxable income.
- Pay Period Proration: Annual net compensation is divided across the designated pay frequency (26 bi-weekly, 24 semi-monthly, 12 monthly, or 52 weekly pay periods).
Worked Example
Consider an employee in Utah earning $75,000 annually, paid bi-weekly (26 paychecks per year), filing single, with $3,500 in annual pre-tax 401(k) contributions.
- Gross pay per paycheck. $75,000 ÷ 26 pay periods = $2,884.62 before any withholding.
- Pre-tax deduction. The $3,500 annual 401(k) contribution reduces each paycheck by $134.62 and also shrinks the wages used to calculate federal and state income tax; FICA is still assessed on the full gross amount.
- FICA payroll taxes. Social Security withholds 6.2% of gross pay ($178.85) and Medicare withholds 1.45% ($41.83), for $220.67 per paycheck.
- Federal income tax withholding. Applying the 2026 IRS withholding tables to the reduced taxable wage withholds $265.38 per paycheck.
- Utah state tax withholding. The flat 4.45% rate applies to the reduced taxable wage, withholding $122.38 per paycheck.
- Net take-home pay. $2,884.62 gross, minus $134.62 pre-tax, minus $220.67 FICA, minus $265.38 federal tax, minus $122.38 state tax leaves $2,141.57 per paycheck, or $55,680.75 per year, an effective total tax rate of 21.09%.
Carrying The Year Forward
Utah's flat 4.45% is applied without brackets, and its cumulative state line rises at a constant rate from the first month to the twelfth.
Step 7 -- Two months of cumulative pay. The schedule's first row shows $6,250.00 of cumulative gross against $4,640.06 of cumulative take-home. Row two doubles both: $12,500.00 gross, $9,280.13 take-home, with $3,219.88 accumulated on the deduction side.
Step 8 -- The full year. By month twelve the schedule reaches $75,000.00 of cumulative gross and $55,680.75 of cumulative take-home, adding $4,640.06 every month without variation.
Step 9 -- What the year actually withheld. The cumulative deduction column closes at $19,319.25. That column carries the $3,500 pre-tax 401(k) contribution alongside the tax, so tax alone is $19,319.25 - $3,500 = $15,819.25, an effective total tax rate of 21.09% on $75,000.00 of gross pay.
Step 10 -- Why the monthly increment never changes. The twelve rows rise in identical increments, which is worth naming rather than assuming. FICA is computed once on the full annual wage -- Social Security capped at $184,500, Additional Medicare charged above $200,000 for a single filer -- and the annual figure is then spread evenly across the months. So the mid-year jump in take-home that a high earner sees on a real pay stub never appears here. At $75,000 nothing crosses either threshold anyway; it would take $184,500 to reach the first and $200,000 to reach the second.
$55,680.75 lands over the year. Utah's single rate means every additional dollar of salary is taxed identically, keeping the $15,819.25 total easy to extrapolate.
Where The Next $100 Of Salary Goes
The federal edges, at $100 spacing. $70,000 of gross is not an arbitrary point for this input set. The $16,100 single standard deduction and the $3,500 pre-tax election shelter $19,600 between them, so $70,000 of gross is exactly $50,400 of federal taxable income, the dollar where the 22% federal band opens. At $70,000 the check is $2,014.84 and the year closes at $52,385.75. At $70,100, one hundred dollars later, the check is $2,017.37 and the year closes at $52,451.65. The federal line moves from $223.08 to $223.92 per check across that step, which is $0.84.
The next edge is the 24% band at $105,700 of taxable income, which is $125,300 of gross under the same election. At $125,300 the check is $3,416.48, the year $88,828.45, the reported effective rate 26.31%. At $125,400 it is $3,418.94, $88,892.35, 26.32%. Two full federal bracket edges therefore sit inside the salary range this calculator is most often pointed at, and neither of them is visible in the twelve-row schedule, which holds gross salary fixed and only walks the calendar.
Utah's own line does not notice any of it. The state figure moves from $113.82 to $113.99 across the $70,000 step and from $208.47 to $208.64 across the $125,300 step, both of which are 4.45% of the extra $100 spread over 26 checks. There is no Utah bracket edge anywhere in the sweep, so every step in the effective rate on this page is federal or FICA in origin.
Where FICA stops behaving like a flat 7.65%. Three probes at the same $100 spacing isolate it, and none of them involve the state line. From $150,000 to $150,100 of gross the FICA figure rises from $441.35 to $441.64 per check, $0.29. From $190,000 to $190,100 it rises from $545.92 to $545.98, $0.06: Social Security has stopped at the $184,500 wage base and only the 1.45% Medicare rate is still running on the next dollar. From $210,000 to $210,100 it rises from $560.54 to $560.63, $0.09, because the 0.9% Additional Medicare surtax switches on above $200,000 for a single filer. The engine applies all three of those rules to the annual figure and then divides by the pay frequency, so a real payroll ledger would show the wage base stopping mid-year while this schedule shows twelve identical steps.
What a $1,000 raise is actually worth. At $75,000 the annual take-home is $55,680.75; at $76,000 it is $56,339.75, so the raise delivers $659.00. At $150,000 the same $1,000 delivers $639.00, because the marginal federal rate is higher there. At $200,000 it delivers $692.00, more than at $150,000, because Social Security has already stopped on those dollars. The retained share is not monotonic in salary, and the wage base is why.
Right method against wrong method, priced. The effective total tax rate this calculator reports is tax divided by gross with the pre-tax election deliberately excluded from the numerator, because a 401(k) contribution is deferred pay rather than tax. Read as a take-home rate it misleads. The engine's own tax total for the worked example is $15,819.25, which would leave $59,180.75 of the $75,000. The check actually delivers $55,680.75 across the year. The $3,500.00 difference is the pre-tax contribution, and the cumulative deduction column in the schedule carries it alongside the tax, which is why that column closes at a larger figure than the tax total.
What This Does Not Account For
- The Utah taxpayer credit is not modelled. The engine applies the flat 4.45% rate to wages less the pre-tax election and stops. Utah's phase-out credit, which reduces the amount actually paid at lower incomes, appears in no code path here, so the $122.38 per check this page reports is the pre-credit figure.
- Local municipal, city, or county wage taxes where applicable.
- Post-tax wage garnishments (child support, tax levies, student loans).
- Voluntary post-tax deductions (Roth 401k, charitable giving, supplemental insurance).
Common Pitfalls
- Confusing Bi-Weekly with Semi-Monthly Pay: Bi-weekly pay results in 26 paychecks per year (two 3-paycheck months), whereas semi-monthly pay results in 24 equal paychecks.
- Failing to Update Form W-4: Inaccurate withholding allowances on Form W-4 can lead to substantial underpayment penalties or large unexpected tax bills.
- Forgetting Pre-Tax Deduction Benefits: Contributions to 401(k) and HSA accounts directly reduce taxable income, lowering both federal and state tax burdens.
- Overlooking Additional Medicare Tax: Failing to anticipate the 0.9% surtax on high-earning households with multiple income sources.
- Using an Outdated Utah Rate: The flat rate is 4.45% for 2026, so older 4.55% or 4.65% references overstate state withholding.
Frequently Asked Questions
Does Utah have a state income tax on paychecks?
How is overtime pay taxed in Utah?
What is the Social Security wage cap for 2026?
Can I adjust my state tax withholding?
Sources
- Internal Revenue Service (IRS): Publication 15 (Circular E) and Publication 15-T (2026). irs.gov/publications/p15
- Social Security Administration (SSA): 2026 Social Security Wage Base Limit. ssa.gov
- Utah State Tax Commission: Employer Withholding Tax Tables (2026). tax.utah.gov