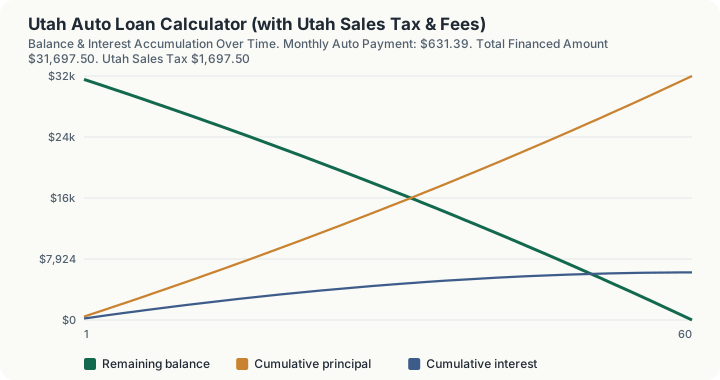
Quick Answer: A $35,000 vehicle in Utah with $5,000 cash down, a 60-month term, and a 7.25% APR carries a $631.39 monthly payment at the 4.85% state rate alone, financing $31,697.50. At a Salt Lake City combined rate near 8.45% the tax rises from $1,697.50 to $2,957.50 and the payment to $656.49. Utah sources a dealer sale to the dealer's location, not your home address.
Overview
Two things separate Utah from most of its neighbours, and one of them is easy to get backwards.
The first: Utah does not publish a special automotive rate. Utah Code § 59-12-103 sets the state sales tax at 4.85% and a vehicle is taxed like any other tangible purchase, at the ordinary combined state, county, city, and transit rate. That is the opposite of the pattern in states like Alabama and Tennessee, which carve out a distinct vehicle rate. Combined Utah rates in the major markets run roughly 6.75% to 8.45%, and the local component can be larger than half the state rate again.
The second: sourcing. Utah State Tax Commission Publication 5 sources a dealer sale to the dealer's location, so the rate that lands on your buyer's order is the rate at the lot where you signed, not the rate where you park the car. Buying in Salt Lake City and registering in Provo means paying Salt Lake City's rate. That runs against the rule in a majority of states, where the tax follows the buyer's residence, and against what most people assume. It also means the rate is one more thing to weigh when you cross county lines chasing inventory.
A caution about the numbers on this page. The 4.85% state rate and the taxability rules below come from primary Utah sources. The metro combined rates were read from the Tax Commission's rate chart through an automated summary rather than checked line by line, and the Utah DMV fee pages block automated retrieval entirely. Where a figure could not be verified, this calculator leaves it out rather than presenting a guess as a fact. That is why no title or registration amount is financed into the delivered price here.
Auto Loan APR by Credit Score
The APR columns below are national averages, not Utah figures. No primary source publishes average auto loan APR by state: Experian's report has no geographic cut, the CFPB publishes state origination volume but no rates, and the New York Fed publishes state delinquency only. The payment column is the part that is specific to Utah, because it runs this calculator's own Utah tax and fee rules at each tier's rate.
| Credit Tier | VantageScore 4.0 | Avg New APR | Avg Used APR | Est. Payment in Utah |
|---|---|---|---|---|
| Super prime | 781-850 | 4.55% | 6.30% | $591.66 |
| Prime | 661-780 | 6.23% | 8.77% | $616.20 |
| Nonprime | 601-660 | 9.67% | 14.03% | $668.34 |
| Subprime | 501-600 | 13.44% | 19.42% | $728.38 |
| Deep subprime | 300-500 | 16.01% | 21.77% | $770.99 |
Payment assumptions: $35,000 vehicle price, $0 trade-in, $5,000 cash down, $0 dealer documentation fee, 60-month term, new-vehicle APR applied to the Utah delivered price including tax and statutory fees. At the 6.39% overall new-car average the same purchase costs $618.57 a month.
The score bands are VantageScore 4.0, not FICO. The same borrower can land in a different tier under each model, so a FICO score pulled from a card issuer will not always match the band here. Source: Experian, State of the Automotive Finance Market, Q1 2026, slide 45.
What Moves Your Payment
Each row changes one input and leaves the rest at the baseline below. The dollar effects are this calculator's own output for Utah, not a rule of thumb.
| Factor | What Changes | Effect on Monthly Payment | Effect on Total Interest |
|---|---|---|---|
| Vehicle Price | Each extra $1,000 of price raises both the amount financed and the sales tax base, so the tax rises with it. | +$20.89 | +$204.62 |
| Trade-In Allowance | A $1,000 allowance cuts the amount financed by $1,000 and reduces the sales tax base by the same amount, so it saves tax as well as principal. | -$20.88 | -$204.63 |
| Cash Down Payment | A $1,000 larger down payment cuts the amount financed by $1,000. It never reduces the sales tax, which is assessed on the price, not on what you borrow. | -$19.92 | -$195.16 |
| Dealer Doc Fee | A $100 higher documentation fee adds $100 to the amount financed and is inside the sales tax base, so it is taxed on top of itself. | +$2.09 | +$20.46 |
| Longer Term | Stretching the same balance from 60 months to 72 months spreads the principal over twelve more payments at the same rate. | -$87.17 | +$1,300.49 |
Baseline: $35,000 vehicle price, $0 trade-in, $5,000 cash down, $0 documentation fee, 60 months at 7.25% APR, giving a $631.39 payment and $6,186.18 of total interest.
How This Is Calculated
Utah requires the trade and the purchase to be a single transaction between two parties before the credit applies. Four steps.
1. Net taxable amount. Utah Code § 59-12-102 excludes a trade-in allowance from the purchase price. Pub 5 lists document service fees and dealer preparation fees inside the taxable amount, while titling and registration amounts, manufacturer rebates, safety inspection fees, GAP, and separately stated interest and insurance are outside it.
Pub 5 attaches a condition to the trade-in: it "must be part of a single transaction between only two parties." The trade and the purchase have to happen together and be documented together. Selling your old car to a third party the same week does not qualify, however similar the cash flows look.
2. Sales tax. The state rate plus whatever local component applies at the dealer's location.
3. Delivered price. Price plus document service fee plus tax. DMV fees are excluded, as explained above.
4. Amount financed and amortization. The trade-in works twice, cutting the tax base and reducing the balance borrowed.
The balance amortizes as a fixed-rate installment loan:
where $P$ is the financed amount, $i$ is the monthly rate (APR ÷ 12), and $n$ is the term in months. Each period's interest is the outstanding balance times $i$, the remainder reduces principal, and the schedule reconciles to zero at maturity.
About the Local Rates
No rate table is published on this page, deliberately. The combined rates behind the metro buttons, Salt Lake City near 8.45%, West Valley City and Provo near 7.45%, Ogden near 7.25%, and St. George near 6.75%, came from the Utah State Tax Commission's Q1 2026 combined rate chart read through an automated summary, and the split between the county, city, and transit components was never obtained separately. That is good enough to show you the shape of the difference between markets. It is not good enough to print as a rate schedule you would rely on at signing.
Two things follow. Use the metro buttons to see how much the local component moves your payment, then confirm the exact rate for the dealer's address against the Tax Commission's own rate lookup before you sign. And note that Salt Lake City and West Valley City sit in the same county and are roughly a full percentage point apart, which is about $350 of tax on a $35,000 car. County alone does not settle the rate in Utah.
Worked Example
The 4.85% below is a floor nobody actually pays: every Utah address carries a local component on top. It is shown alone so you can see the state share separately, and no title or registration fee is financed here because those DMV figures could not be verified.
- Vehicle price: $35,000
- Trade-in allowance: $0
- Cash down: $5,000
- Document service fee: $0
- Local component: 0% (state rate alone)
- Term: 60 months at 7.25% APR
Step 1 -- The taxable amount. Purchase price less a trade-in credit taken in the same two-party transaction: $35,000 - $0 = $35,000.00
Step 2 -- Utah sales tax at the 4.85% state rate. $35,000.00 x 4.85% = $1,697.50
Step 3 -- Total delivered price. $35,000 + $1,697.50 = $36,697.50
Step 4 -- Amount financed. $36,697.50 - $0 trade-in - $5,000 cash down = $31,697.50
Step 5 -- The monthly payment. $31,697.50 at 7.25% over 60 months = $631.39
Step 6 -- Month 1. $31,697.50 x (7.25% / 12) = $191.51 interest, $439.88 principal, balance $31,257.62
Step 7 -- Month 2. $31,257.62 x (7.25% / 12) = $188.85 interest, $442.54 principal, balance $30,815.08. Cumulative interest: $380.36
Step 8 -- The accumulation. Interest through month 12 is $2,119.09 with $26,239.91 still owed. Over the full term, $6,186.18
Switch to a Salt Lake City combined rate near 8.45% and the tax becomes $2,957.50, the financed balance $32,957.50, and the payment $656.49. St. George near 6.75% lands in between at $2,362.50 of tax and a $644.64 payment.
Add a $10,000 trade-in at the state rate alone and the taxable amount drops to $25,000, the tax to $1,212.50, and the payment to $422.54. The credit saved $485.00. In Salt Lake City the same trade-in saves $845.00, because the credit is worth whatever the combined rate is. That is the practical case for trading in rather than selling privately: a private buyer has to beat the dealer's trade offer by more than $845 before you come out ahead in a high-rate market.
A $300 document service fee raises the taxable amount to $35,300 and, at 8.45%, the tax to $2,982.85. The fee costs $325.35 all in.
What This Does Not Account For
- Title and registration fees. Utah's title fee is widely reported at $6 and base passenger registration near $44, but dmv.utah.gov returns HTTP 403 to automated retrieval, so neither figure could be confirmed against a primary document. Both are excluded from the delivered price here rather than financed into a number the source does not support. Check the current DMV fee page and add them yourself. Counties also add local option registration fees.
- The annual age-based uniform fee. Utah charges this at registration in lieu of an ad valorem property tax on most passenger vehicles, with reported tiers of $150 under three years old, $110 at three to six, $80 at six to nine, $50 at nine to twelve, and $10 beyond that. Those tier amounts came from the same blocked source and are unverified. Some vehicle classes instead pay a uniform fee of 1.0% or 1.5% of value. Either way it is a recurring annual cost, not something financed into the loan.
- The exact local rate at your dealer's address. See the section above. The metro figures here are approximate.
- Private-party purchases. Pub 5 sources those to the rate where the buyer registers the vehicle rather than to a dealer location, and the trade-in mechanics differ because there is no dealer taking the old car in a single transaction.
- Safety inspection fees, manufacturer rebates, and separately stated interest or insurance, all of which Pub 5 places outside the taxable amount.
- GAP insurance, extended service contracts, and aftermarket accessories, unless you fold them into the vehicle price yourself.
Common Pitfalls
- Using your home ZIP code's rate on a dealer purchase. Pub 5 sources a dealer sale to the dealer's location. A Provo resident buying in Salt Lake City pays the Salt Lake City rate, and on a $35,000 car that is about $350 more than the Provo rate would produce.
- Assuming the county fixes the rate. Salt Lake City and West Valley City are both in Salt Lake County and differ by roughly a percentage point.
- Treating 4.85% as the rate you will pay. Nowhere in Utah is the combined rate 4.85%. The state component alone understates a Salt Lake City tax bill by $1,260 on a $35,000 car.
- Selling your old car separately and expecting the trade-in credit. Pub 5 requires a single transaction between only two parties. A separate sale, even to the same dealer on a different ticket, puts the credit at risk.
- Forgetting the document service fee is taxable. Pub 5 names it explicitly. Utah caps it at nothing, so it is worth negotiating, and every dollar you cut saves the combined rate on top.
- Budgeting only the purchase. The annual uniform fee arrives every registration renewal for the life of the car and is largest in the first three years, exactly when the loan payment is also largest.
- Judging the loan by the payment alone. Stretching the Salt Lake City balance of $32,957.50 from 60 to 72 months lowers the payment to $565.86 and raises total finance charges from $6,432.04 to $7,784.23.
Frequently Asked Questions
What is the sales tax on a car in Utah?
Is Utah car tax based on where I live or where I buy?
Does a trade-in reduce sales tax in Utah?
Is the Utah dealer document service fee taxable?
What is the Utah uniform fee on a vehicle?
Why does this calculator not include Utah title and registration fees?
Sources
- Utah State Tax Commission, Publication 5, Sales Tax Information for Vehicle and Watercraft Dealers (dealer-location sourcing; document service and dealer preparation fees inside the taxable amount; titling and registration amounts, rebates, inspection fees, GAP and separately stated interest outside it; single-transaction condition on the trade-in) tax.utah.gov
- Consumer Financial Protection Bureau, Truth in Lending Act (Regulation Z, 12 CFR § 1026.22) disclosure requirements for installment credit. ecfr.gov/current/title-12/chapter-X/part-1026
Also consulted: Utah Code § 59-12-103 (state sales and use tax rate); Utah Code § 59-12-102 (definition of purchase price and sales price, trade-in exclusion); Utah Code § 59-12-211 (sourcing of motor vehicle sales); Utah State Tax Commission combined sales tax rate chart, Q1 2026 (metro combined rates, read via automated summary and treated as approximate); Utah Division of Motor Vehicles registration taxes and fees page (title, registration, and age-based uniform fee amounts, unverified: the page blocks automated retrieval); Experian, State of the Automotive Finance Market, Q1 2026, slide 45 (average new and used auto loan APR by VantageScore 4.0 credit tier; national, no state level cut published).