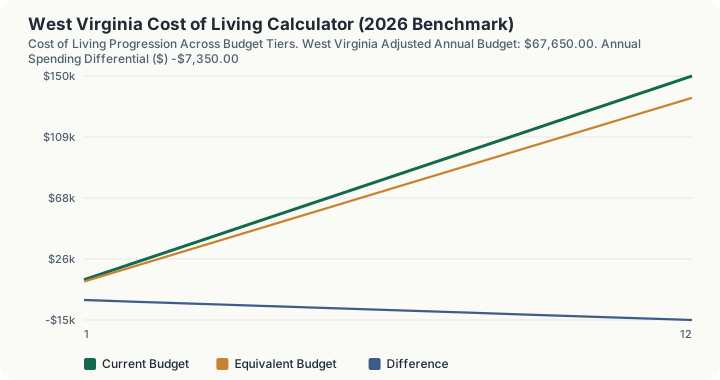
Quick Answer: West Virginia's cost of living is 9.8% below the U.S. national average (composite index 90.2), so a $75,000.00 national-average household budget costs about $67,650.00 a year in West Virginia.
Overview
West Virginia's composite cost-of-living index sits at 90.2 against the national baseline of 100, meaning a household budget runs 9.8% below the U.S. average once it crosses the state line. That places West Virginia among the fifteen most affordable states nationally.
The housing index does most of the work behind that number, priced at an index of 76.5, the widest gap from the 100 baseline of any category the state tracks. Utilities (index 93.2) and groceries (index 96.8) move the total by comparison-smaller amounts.
For relocation budgeting and compensation planning, the practical takeaway is that West Virginia is among the more affordable Southern states, so employers benchmarking pay against neighboring states should not assume a single regional adjustment applies evenly across the South.
On the calculator's $75,000 reference budget, that trims about $7,350 a year, a gap traceable mostly to housing: the housing index sits 23.5 points below the 100.0 baseline on its own. MERIC's composite figure also folds in transportation, healthcare, and miscellaneous goods and services, categories the index tracks but does not break out state by state in the published table.
Key Index Components for West Virginia:
- Composite Benchmark Index: 90.2 (Rank #43)
- Housing Cost Index: 76.5
- Utilities Cost Index: 93.2
- Grocery Cost Index: 96.8
How This Is Calculated
West Virginia's composite of 90.2 comes almost entirely from housing at 76.5, close to 24 points under the national line. Groceries at 96.8 and utilities at 93.2 contribute much less. Rank 43 of 50. The calculator scales your budget by the composite.
- Baseline budget. You enter annual household spending priced at the national benchmark, index 100.0.
- Composite lookup. West Virginia's composite index of 90.2 is read from the 2026 MERIC state table, along with its rank of #43 among the 50 states.
- Single-factor scaling. The baseline is multiplied by 90.2 and divided by 100. Housing 76.5, groceries 96.8 and utilities 93.2 are context figures, not separately weighted terms, because MERIC's composite already applies category weights. Outside shelter the state runs only about 5% under the national average, so the composite flatters West Virginia for a household that already owns a home.
- Differential. The dollar and percentage difference against the baseline is taken from the scaled result, which is what the headline output and the monthly view report.
Worked Example
Using this calculator's baseline scenario: a household needing $75,000.00 a year to sustain a standard basket of goods (housing, groceries, utilities, transportation, and healthcare), priced at the U.S. national average (composite index 100.0).
- National baseline. $75,000.00 is the reference spending level at the national-average price level (index 100.0).
- Apply West Virginia's composite index. West Virginia's composite index of 90.2 (rank #43 nationally) means local prices run 9.8% below the national basket. Scaling: $75,000.00 × (90.2 ÷ 100) = $67,650.00.
- Dollar differential. $67,650.00 − $75,000.00 = -$7,350.00, so a household living in West Virginia needs its budget to shrink by that amount to match the same standard of living.
- Percentage and monthly view. That is -9.8% of the baseline, or $5,637.50/mo in West Virginia versus $6,250.00/mo nationally.
West Virginia runs meaningfully cheaper than the national baseline, with housing costs (index 76.5, 23.5 points below average) the largest single driver of the gap.
Reading A Discount Off The Budget Ladder
The marginal cost of the next $1,000 of national-average budget. Raising the baseline from $75,000 to $76,000 moves the West Virginia figure from $67,650.00 to $68,552.00, a step of $902.00. Every additional $1,000 of national-average spending costs $902.00 in West Virginia, at every budget level, because the engine performs one multiplication by 90.2 divided by 100 and nothing else. At $120,000 of baseline the figure is $108,240.00 and the differential is $-11,760.00.
The reverse question. A household already spending $67,650.00 in West Virginia and asking what that buys at national prices divides rather than multiplies: $67,650.00 at an index of 90.2 corresponds to the $75,000 baseline this calculator started from. The relationship is exactly proportional in both directions and the calculator only runs one of them, so there is no national-baseline input to solve backwards and the division has to be done outside the page.
Stepping the budget up in twelfths. The twelve-row schedule prices a budget tier of baseline times i divided by 6 on row i, and it applies the 90.2 composite to every one of those tiers. Row one, at $12,500 of baseline, reads $11,275.00. Row two, at $25,000, reads $22,550.00. Row three, at $37,500: $33,825.00. Row four, at $50,000: $45,100.00. Row five, at $62,500: $56,375.00. Only one thing changes between adjacent rows, the tier, so each row sits exactly $11,275.00 above the row before it and the column is a straight line through the origin. The Difference column climbs in equal steps of -$1,225.00 for the same reason: a fixed fraction of a fixed increment is itself fixed.
Row six restates the answer above. Row six carries the $75,000 baseline, the same figure entered above, and it reads $67,650.00 against a Difference of -$7,350.00. Those are the headline result and the headline differential to the cent, because the row and the headline run the identical multiplication. Row twelve, at $150,000 of baseline, reads $135,300.00, exactly twice row six, since doubling the tier doubles the scaled figure and the difference alike. Nothing in the sweep bends, caps, or switches to a different index partway down, so the table can be read straight down and any row can be compared with any other.
Why the sub-indices stay out of the arithmetic. The composite already carries MERIC's category weights. Housing at 76.5, groceries at 96.8 and utilities at 93.2 are the components those weights were applied to, so multiplying a budget by each of them and summing would count the same spending three times over. The engine never does this. It scales by a single factor, and the three category readings appear on this page as context beside the composite: no code path multiplies your budget by any of them, in the headline or in any row of the schedule.
What This Does Not Account For
- The category indices are context only. Housing 76.5, groceries 96.8 and utilities 93.2 are printed beside the composite and enter no calculation on this page. Every figure here, headline and schedule alike, comes from the single composite 90.2.
- Household size is not an input. One person and a family of five entering $100,000 of baseline receive the same West Virginia figure, because the only input the engine reads is the budget itself.
- No spending is apportioned across categories. The engine multiplies the whole budget by one composite index. It does not split the budget into housing, food and utility shares and it does not weight them.
- The national rank of #43 is read from the same table as the index and is not computed. It does not move with the budget entered.
- There is no sub-state variation. One statewide composite covers every address in West Virginia, so a household in the most expensive metro and one in the cheapest county receive the same answer.
- Intra-state variance between major metropolitan urban centers and rural counties within West Virginia.
- Discretionary lifestyle choices, private schooling, and luxury expenditures.
- State income and property tax impacts on disposable take-home salary.
- Dynamic seasonal utility price surges during peak winter heating or summer cooling months.
Common Pitfalls
- Comparing State Averages Instead of Metro Areas: Living in a major metro area is often 20%-40% more expensive than the statewide average.
- Focusing Solely on Housing: Overlooking higher utility, transportation, or food costs in colder or remote regions.
- Ignoring Net Take-Home Pay: Comparing gross salary without factoring in state income and sales tax differentials.
- Failing to Adjust for Family Size: Larger households experience disproportionately higher grocery and healthcare expenditures.
Frequently Asked Questions
Is West Virginia expensive to live in?
What is the biggest cost factor in West Virginia?
How much salary do I need to maintain my lifestyle in West Virginia?
How often are cost of living indices updated?
Sources
- U.S. Bureau of Economic Analysis (BEA): Regional Price Parities. bea.gov/data/prices-inflation/regional-price-parities-state-and-metro-area
- U.S. Bureau of Labor Statistics (BLS): Consumer Expenditure Survey. bls.gov/cex
- West Virginia State Tax Department, the official state tax authority for West Virginia rates, rules and forms. tax.wv.gov
Also consulted: MERIC: Cost of Living Data Series (2025/2026).