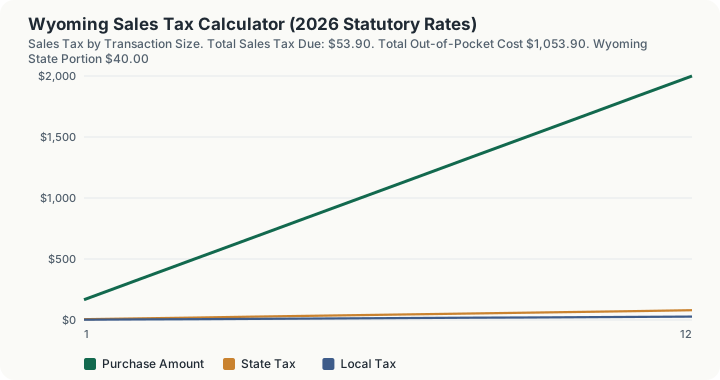
Quick Answer: A $1,000 taxable purchase in Wyoming costs $53.90 in combined state and local sales tax, for a total of $1,053.90 out the door.
Overview
How much sales tax gets added to a purchase in Wyoming depends on two separate decisions: what the state legislature set as the statutory rate (4.00%), and what the local city or county government layered on top of it. Local jurisdictions (cities, counties, and in some cases special taxing districts) are free to add their own surcharges on top of that, and the statewide average of those add-ons is 1.39%, which brings the typical combined rate to 5.39%.
That 5.39% average combined rate ranks among the five lowest of any state that still levies a general sales tax. A single combined figure is useful for budgeting and for comparing Wyoming to other states, but it is still an average. The exact rate a shopper pays depends on the specific address where the sale takes place. Someone relocating to Wyoming, or opening a second business location within the state, should treat the 5.39% figure as a planning estimate rather than the number that will appear on every single invoice.
How This Is Calculated
Wyoming charges 4.00%, tied for one of the lowest state rates in the country, and counties add an average 1.39% for a combined 5.39% and $53.90 on a $1,000 purchase. The local layer is county-level and voter-approved, typically a general purpose or specific purpose option tax that expires unless renewed, so a Wyoming county's rate can move by a full point between elections. Wyoming has no individual income tax and leans heavily on mineral severance revenue, which is why it can hold the sales tax rate this low.
State and county rates apply to the same base and combine into one rate:
The calculator runs:
- Take the entered amount as the base. No adjustments are made to the price before tax is computed.
- No item-level exemption filtering. Wyoming exempts groceries for home consumption and prescription drugs; the calculator applies the general rate to the whole amount you enter.
- Compute the state portion. The base is multiplied by the state statutory rate.
- Apply the county surcharge. The 1.39% average reflects the optional county taxes currently in force, which are approved for fixed terms rather than permanently.
- Sum and total. The state and local amounts are added to give total tax, and the total is added back to the price to give the out-of-pocket cost.
Worked Example
For a $1,000 taxable purchase in Wyoming:
- Starting purchase price. The buyer rings up a $1,000.00 taxable retail purchase in Wyoming, the baseline amount before any tax is applied.
- State portion. Wyoming's statutory state sales tax rate of 4.00% applies to the full purchase amount: $1,000.00 × 4.00% = $40.00 owed to the state.
- Local portion. Local municipal, county, and special-district surcharges add an average of 1.39% on top of that: $1,000.00 × 1.39% = $13.90 more.
- Combined tax due. Summing the two pieces, $40.00 in state tax plus $13.90 in local surcharge comes to $53.90 in total sales tax owed on the transaction.
- Total out-of-pocket cost. Adding that $53.90 in tax to the $1,000.00 purchase price brings the buyer's total out-of-pocket cost to $1,053.90.
This example uses Wyoming's statewide average local rate of 1.39%; actual combined rates vary by city and county, so a real receipt could show a combined rate above or below the 5.39% average used here.
The Wyoming Rate Applied Twice Over
The per-$100 figure. A $100 taxable purchase in Wyoming carries $5.39 of combined tax. That is the whole marginal story on this page: the engine multiplies one base by one combined rate, so tax scales exactly linearly and the figure for any amount is $5.39 for every hundred dollars of it. At $1,000 it is $53.90; at $30,000 it is $1,617.00, which is thirty times $5.39 to the cent.
The state share against the local share. On the $1,000 default the split is $40.00 to the state at 4.00% and $13.90 to local jurisdictions at the 1.39% statewide average, so the local layer is 25.8% of the total tax collected. Turn the local surcharge off and the tax falls from $53.90 to $40.00, a difference of $13.90. On a $30,000 vehicle the same toggle moves the bill from $1,617.00 to $1,200.00, a difference of $417.00, which is the practical size of the question "which county did this sale happen in".
The reverse question, and the error it usually attracts. Someone holding a Wyoming receipt for $1,053.90 and wanting the pre-tax base cannot subtract the combined rate from it. Feed $1,053.90 back into this calculator as the purchase amount and it returns $56.81 of tax, because $1,053.90 is not the base: it already contains the tax. Deducting that $56.81 leaves $997.09, when the true base is $1,000.00. The error is $2.91 on a single $1,000 purchase, and it scales: on the $31,617.00 total of a $30,000 purchase the same wrong step returns $1,704.16 of tax and a base of $29,912.84, understating by $87.16.
The correct operation. Divide the tax-inclusive total by 1 plus the combined rate, or equivalently multiply it by the 5.39% fraction of the gross rather than of the base. The calculator adds tax to a base and does not run that direction: there is no tax-inclusive input on this page, and every figure it reports assumes the amount entered is exclusive of tax. Entering a till total instead of a net price overstates the tax by $2.91 per $1,000 every time.
What This Does Not Account For
- There is no tax-inclusive mode. The amount entered is treated as the pre-tax base without exception, so a total that already contains tax returns $56.81 rather than $53.90 on the $1,000 example.
- The local figure is a single statewide average, not an address lookup. The engine holds one 1.39% number for the whole state and applies it or does not; no county, city or special district rate exists anywhere in the code path.
- No item is exempt. The combined rate is applied to the whole amount entered, so groceries, prescriptions and any other statutory exemption have to be excluded from the input before it is entered.
- Statutory exemptions on unprepared groceries, prescription medications, or manufacturing equipment.
- Special industry excise taxes (lodging hotel taxes, vehicle rental fees, alcohol/tobacco excise).
- Use tax compliance on out-of-state untaxed online purchases.
- B2B resale certificate exemptions or direct pay permit programs.
Common Pitfalls
- Confusing State and Combined Rates: Quoting the state base rate without factoring in local city and county add-on taxes.
- Overlooking Consumer Use Tax: Failing to self-report and remit use tax on untaxed out-of-state purchases on your state income tax return.
- Missing Annual Sales Tax Holidays: Many states offer annual tax-free weekends for back-to-school items, severe weather supplies, or energy-efficient appliances.
- Failing to Collect Resale Certificates: Selling wholesale without collecting valid exemption certificates exposes sellers to full sales tax liability upon audit.
Frequently Asked Questions
What is the sales tax rate in Wyoming?
Are groceries taxed in Wyoming?
How does use tax differ from sales tax?
Are digital goods and SaaS taxable in Wyoming?
Sources
- Wyoming Department of Revenue: 2026 Sales and Use Tax Rate Schedules. revenue.wyo.gov
- Streamlined Sales Tax Governing Board (SSTGB): State Taxability Matrix. streamlinedsalestax.org/for-businesses/taxability-matrix