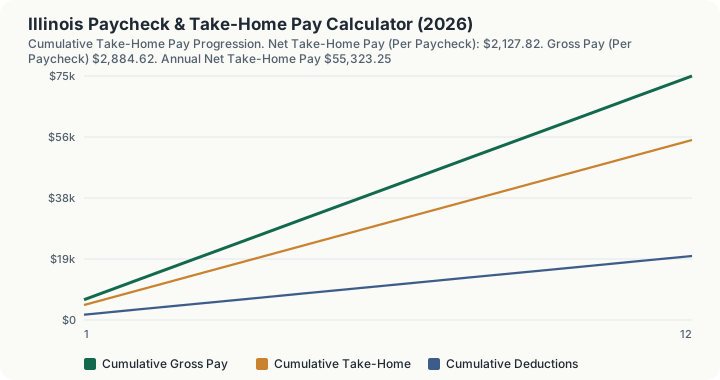
Quick Answer: A $75,000 annual salary in Illinois, paid bi-weekly and filing single, takes home about $2,127.82 per paycheck ($55,323.25 per year) after federal tax, FICA, and Illinois state withholding.
A Constitutionally Single Rate
Illinois applies a flat 4.95% state income tax rate to wages, a structure written into the state constitution, which requires that any income tax be applied uniformly rather than through graduated brackets. The Illinois Paycheck Calculator applies that flat rate together with federal withholding and FICA to compute exact net take-home pay.
That constitutional requirement is part of why Illinois has stuck with a flat rate even as several other Midwestern states have debated or adopted graduated systems; voters rejected a proposed switch to a graduated tax in 2020, leaving the flat structure in place.
Salaried employees, hourly workers, payroll administrators, and HR teams still need to model the combined effect of federal brackets, FICA, and Illinois's flat state rate to forecast net pay accurately across bi-weekly, semi-monthly, monthly, and weekly schedules. Because the rate never changes with income, pre-tax elections like 401(k) and HSA contributions are the main tool Illinois workers have for adjusting how much is withheld from each paycheck.
How This Is Calculated
Illinois is constitutionally required to tax income at a single rate, currently 4.95%, and voters declined to change that in a 2020 ballot measure. No Illinois municipality levies a wage tax, including Chicago, so the 4.95% line is the entire state and local income tax picture on an Illinois stub. The paycheck is one subtraction:
Four steps stand between gross salary and net pay:
- FICA Payroll Tax Computation: - Social Security (OASDI): 6.20% withheld on wages up to the 2026 statutory wage base ($184,500). - Medicare (HI): 1.45% withheld on all gross earnings (no wage cap), plus 0.90% Additional Medicare Tax on earnings exceeding $200,000 (single) or $250,000 (married filing jointly).
- Federal Income Tax Withholding: Evaluated using 2026 progressive federal tax brackets (10%, 12%, 22%, 24%, 32%, 35%, 37%) after applying standard deduction thresholds ($16,100 single / $32,200 married joint).
- Illinois State Income Tax Withholding: A flat 4.95% applied to Illinois taxable income after the state personal exemption.
- Pay Period Proration: Annual net compensation is divided across the designated pay frequency (26 bi-weekly, 24 semi-monthly, 12 monthly, or 52 weekly pay periods).
Worked Example
Consider an employee in Illinois earning $75,000 annually, paid bi-weekly (26 paychecks per year), filing single, with $3,500 in annual pre-tax 401(k) contributions.
- Gross pay per paycheck. $75,000 ÷ 26 pay periods = $2,884.62 before any withholding.
- Pre-tax deduction. The $3,500 annual 401(k) contribution reduces each paycheck by $134.62 and also shrinks the wages used to calculate federal and state income tax; FICA is still assessed on the full gross amount.
- FICA payroll taxes. Social Security withholds 6.2% of gross pay ($178.85) and Medicare withholds 1.45% ($41.83), for $220.67 per paycheck.
- Federal income tax withholding. Applying the 2026 IRS withholding tables to the reduced taxable wage withholds $265.38 per paycheck.
- Illinois state tax withholding. Illinois's withholding tables apply to the reduced taxable wage, withholding $136.13 per paycheck.
- Net take-home pay. $2,884.62 gross, minus $134.62 pre-tax, minus $220.67 FICA, minus $265.38 federal tax, minus $136.13 state tax leaves $2,127.82 per paycheck, equal to $55,323.25 per year, an effective total tax rate of 21.57%.
From Month Two To The Twelve-Month Total
Illinois applies a flat 4.95%, and this engine applies it to the whole reduced wage with no personal exemption allowance, so the cumulative state line is a straight multiple of gross pay less the 401(k) contribution.
Step 7 -- Two months of cumulative pay. The schedule's first row shows $6,250.00 of cumulative gross against $4,610.27 of cumulative take-home. Row two doubles both: $12,500.00 gross, $9,220.54 take-home, with $3,279.46 accumulated on the deduction side.
Step 8 -- The full year. By month twelve the schedule reaches $75,000.00 of cumulative gross and $55,323.25 of cumulative take-home, adding $4,610.27 every month without variation.
Step 9 -- What the year actually withheld. The cumulative deduction column closes at $19,676.75. That column carries the $3,500 pre-tax 401(k) contribution alongside the tax, so tax alone is $19,676.75 - $3,500 = $16,176.75, an effective total tax rate of 21.57% on $75,000.00 of gross pay.
Step 10 -- Why the monthly increment never changes. Every month in the schedule adds the same amount, and that is a property of the engine, not just of this salary. The $184,500 Social Security wage base and the $200,000 Additional Medicare threshold are applied to annual wages first, and only then is the annual result divided across twelve months. A real payroll ledger would show take-home step up in the month Social Security stops; this schedule never does. At $75,000 the point is academic, because gross reaches neither limit. Above $184,500, or above $200,000 filing single, it would matter and this schedule would still run flat.
$55,323.25 lands over the year. Because the state rate is flat and no exemption is applied, the Illinois portion of the $16,176.75 total scales exactly with gross pay: a 10% raise raises it by 10%.
Filing Status, Deferral and the Wage Base
Illinois taxes at a constitutionally single rate of 4.95%, so the state line in the schedule above is a straight multiple of the reduced wage. The interesting movement is in the other three inputs, and in one federal threshold.
The marginal wedge on a raise. At $76,000 the engine returns $55,977.25 of annual take-home against $55,323.25 at the baseline, so a $1,000 raise delivers $654.00 and the combined federal, FICA and Illinois wedge on the next thousand dollars is 34.60%. The 21.57% effective rate on the page describes the whole salary; this is what an extra thousand of overtime is worth.
Crossing the Social Security wage base. At $184,500 the engine withholds $542.86 of FICA per bi-weekly check; at $185,500 it withholds $543.41. That is 55 cents on $38.47 more gross per check, where the same $38.47 at the $75,000 baseline costs $2.95, moving FICA from $220.67 to $223.62. Annual take-home over that upper thousand rises from $125,752.25 to $126,448.25, delivering $696.00 rather than $654.00. It is the only threshold anywhere in this calculation.
The 401(k) dial, priced. Raising the pre-tax contribution from $3,500 to $13,500 takes annual take-home from $55,323.25 to $47,518.25. Ten thousand dollars deferred costs $7,805.00 of net pay, so each $1,000 into the plan costs $780.50 in the bank and saves $219.50 in federal and Illinois tax. Setting the contribution to zero returns $57,880.00, with per-check Illinois withholding at $142.79 instead of $136.13.
Filing status. Married filing jointly lifts annual take-home from $55,323.25 to $58,003.25, a gain of $2,680.00, and Illinois withholding holds at $136.13 per check under both statuses. Illinois applies one rate regardless of status, so the state result is right; the engine would behave the same way in a state where it is not.
The Illinois exemption is not implemented. This is the most consequential thing on the page. Illinois grants a personal exemption allowance per taxpayer and dependent, subtracted from net income before the 4.95% applies. This engine applies 4.95% directly to gross pay less your pre-tax contributions, with no exemption allowance, no standard deduction and no W-4 line, so the $136.13 per check overstates what an Illinois employer would actually withhold. The overstatement is a fixed dollar amount rather than a slope change, which is why the schedule above still rises in perfectly even steps.
What This Does Not Account For
- Local municipal, city, or county wage taxes where applicable.
- Post-tax wage garnishments (child support, tax levies, student loans).
- Voluntary post-tax deductions (Roth 401k, charitable giving, supplemental insurance).
Common Pitfalls
- Confusing Bi-Weekly with Semi-Monthly Pay: Bi-weekly pay results in 26 paychecks per year (two 3-paycheck months), whereas semi-monthly pay results in 24 equal paychecks.
- Failing to Update Form W-4: Inaccurate withholding allowances on Form W-4 can lead to substantial underpayment penalties or large unexpected tax bills.
- Forgetting Pre-Tax Deduction Benefits: Contributions to 401(k) and HSA accounts directly reduce taxable income, lowering both federal and state tax burdens.
- Overlooking Additional Medicare Tax: Failing to anticipate the 0.9% surtax on high-earning households with multiple income sources.
Frequently Asked Questions
Does Illinois have a state income tax on paychecks?
How is overtime pay taxed in Illinois?
What is the Social Security wage cap for 2026?
Can I adjust my state tax withholding?
Sources
- Internal Revenue Service (IRS): Publication 15 (Circular E) and Publication 15-T (2026). irs.gov/publications/p15
- Social Security Administration (SSA): 2026 Social Security Wage Base Limit. ssa.gov
- Illinois Department of Revenue: Employer Withholding Tax Tables (2026). tax.illinois.gov