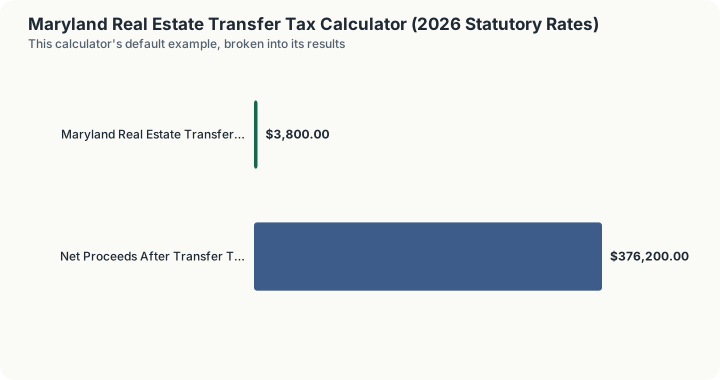
Quick Answer: A $380,000 home sale in Maryland owes $3,800.00 in combined state and county transfer tax, an effective 1% rate combining the flat 0.5% state transfer tax with a typical 0.5% county transfer tax add-on.
Overview
Maryland's transfer tax is a two-layer system: a flat 0.5% state tax under Tax-Property Section 13-203 applies everywhere, and county transfer taxes stack on top at rates that vary enormously by jurisdiction, from 0% in Frederick, Carroll, Charles, and Calvert counties to as much as 1.5% in Baltimore City and Baltimore County. That range means the identical $380,000 sale can owe $1,900 in one Maryland county and roughly $7,600 in another, purely because of the local add-on.
Maryland transfer tax is customarily split between buyer and seller, though the specific allocation is a matter of the purchase contract and can vary by local custom and county. This calculator applies a typical 0.5% local rate as its statewide baseline; because Maryland's actual local rates span the full 0% to 1.5% range, confirming the specific county rate matters here more than in almost any other state's calculation, and this baseline also excludes Maryland's separate state and county recordation tax.
How This Is Calculated
Maryland's transfer tax comes in two flat layers, and the county layer varies more than almost anywhere else: from zero in Frederick, Carroll, Charles and Calvert up to 1.5% in Baltimore City and Baltimore County.
The engine applies the 0.5% state rate under Tax-Property 13-203 plus a 0.5% county figure taken as a mid-range value across Maryland's 24 counties and Baltimore City. Both components are flat, so the combined 1% applies to the whole price with no bracket to cross. This figure does not include Maryland's separate state and county recordation tax, which is charged on top and looked up separately.
Worked Example
Maryland stacks a state transfer tax and a county transfer tax on the same consideration. The engine applies each to the full price and adds them.
Step 1 -- The consideration. Contract sale price = $380,000
Step 2 -- The state transfer tax. Tax-Property 13-203, 0.5% of the full price: $380,000 x 0.005 = $1,900.00
Step 3 -- The typical county transfer tax. Statewide-typical 0.5%: $380,000 x 0.005 = $1,900.00
Step 4 -- Total transfer tax due. $1,900.00 + $1,900.00 = $3,800.00
Step 5 -- Net proceeds after tax. $380,000.00 - $3,800.00 = $376,200.00
Step 6 -- The effective rate. $3,800.00 / $380,000 = 1.000%
At the calculator's $1,500,000 scenario the two components scale together.
Step 7 -- State portion on the luxury sale. $1,500,000 x 0.005 = $7,500.00
Step 8 -- County portion on the luxury sale. $1,500,000 x 0.005 = $7,500.00
Step 9 -- Total on the luxury sale. $7,500.00 + $7,500.00 = $15,000.00
Step 3 is a statewide average, and Maryland's counties diverge from it more than most states' do. Frederick, Carroll, Charles and Calvert charge no county transfer tax at all, which would take the Step 4 total down to the $1,900 of Step 2 alone, while Baltimore City and Baltimore County reach 1.5%, which would push it to $7,600 on the same sale. That is a four-fold spread on identical consideration, decided entirely by which side of a county line the property sits on. Separately, Maryland levies recordation tax by the $500 of consideration at county-set rates, a distinct charge that is not part of any figure above. First-time Maryland homebuyers are exempt from the state portion in Step 2, which the engine does not model.
What This Does Not Account For
- The wide variation in actual county transfer tax rates. Some Maryland counties, including Frederick, Carroll, Charles, and Calvert, charge no local transfer tax at all, while Baltimore City and Baltimore County charge as much as 1.5%. This calculator's 0.5% average county rate is a reasonable planning estimate, not the exact rate for any specific county.
- The separate state and county recordation tax. Maryland imposes a distinct recordation tax on deeds and on mortgage or deed of trust debt, calculated separately from the transfer tax and varying by county. This calculator does not include recordation tax in its output.
- First-time homebuyer exemptions and reductions. Maryland and many of its counties offer reduced transfer tax rates or partial state transfer tax exemptions for qualifying first-time homebuyers, which this calculator does not model.
- Exemptions for certain transfer types. Transfers between spouses, transfers into revocable trusts, and transfers by operation of law may be exempt from some or all of the transfer tax under Maryland law. This calculator assumes a standard taxable arm's-length sale.
Common Pitfalls
- Using the state-only rate and forgetting the county component. The 0.5% state transfer tax alone significantly understates total transfer tax due in nearly every Maryland county, since almost all counties layer their own local rate on top.
- Assuming every county charges the same local rate. Maryland's county transfer tax rates range from 0% in several counties to 1.5% in Baltimore City and County, a meaningful spread; using this calculator's 0.5% average instead of the actual county rate can produce a noticeably different number for a specific property.
- Confusing the transfer tax with the recordation tax. Maryland charges these as two separate taxes with different bases and different rate structures; combining or substituting one for the other on a closing worksheet produces an incorrect total.
- Overlooking first-time homebuyer relief. Qualifying first-time buyers in Maryland can receive a reduced state transfer tax rate and sometimes a county-level reduction as well, which this calculator's standard-sale baseline does not reflect.
Frequently Asked Questions
What is Maryland's real estate transfer tax rate?
Who pays the transfer tax in Maryland?
Do all Maryland counties charge the same local transfer tax rate?
Is the Maryland transfer tax the same as the recordation tax?
Does Maryland offer any transfer tax relief for first-time homebuyers?
Sources
- Comptroller of Maryland, the official state tax authority for Maryland rates, rules and forms. marylandtaxes.gov
Also consulted: Maryland Department of Assessments and Taxation: State transfer tax guidance under Tax-Property Article 13-203.