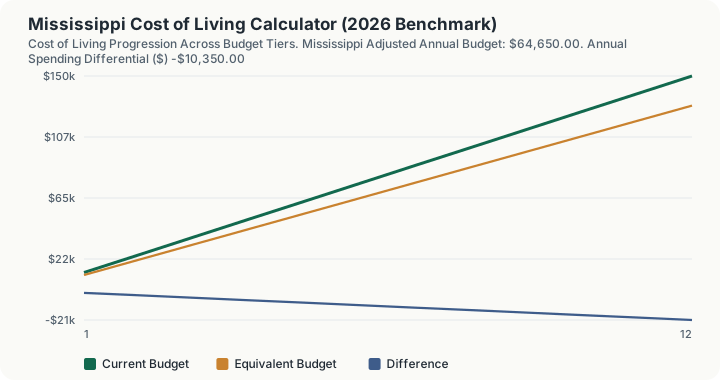
Quick Answer: Mississippi's cost of living is 13.8% below the U.S. national average (composite index 86.2), so a $75,000.00 national-average household budget costs about $64,650.00 a year in Mississippi.
The Lowest-Cost End of the National Range
Mississippi's composite cost-of-living index sits at 86.2 against the national baseline of 100, meaning a household budget runs 13.8% below the U.S. average once it crosses the state line. That places Mississippi among the ten most affordable states in the country.
The housing index does most of the work behind that number, priced at an index of 68.4, the widest gap from the 100 baseline of any category the state tracks. Utilities (index 91.2) and groceries (index 92.5) move the total by comparison-smaller amounts.
For relocation budgeting and compensation planning, the practical takeaway is that Mississippi is among the most affordable of the 16 Southern states by this measure, though Oklahoma and Alabama both price lower, so employers benchmarking pay against neighboring states should not assume a single regional adjustment applies evenly across the South.
On the calculator's $75,000 reference budget, that trims about $10,350 a year, a gap traceable mostly to housing: the housing index sits 31.6 points below the 100.0 baseline on its own. MERIC's composite figure also folds in transportation, healthcare, and miscellaneous goods and services, categories the index tracks but does not break out state by state in the published table.
How This Is Calculated
Mississippi has the cheapest housing in the United States at an index of 68.4, more than 31 points under the national line and lower than any other state in the 2026 table. That drives the composite to 86.2, third-cheapest overall, with utilities at 91.2 and groceries at 92.5 adding smaller discounts. The calculator prices your national-average budget at that composite.
- Baseline budget. You enter annual household spending priced at the national benchmark, index 100.0.
- Composite lookup. Mississippi's composite index of 86.2 is read from the 2026 MERIC state table, along with its rank of #48 among the 50 states.
- Single-factor scaling. The baseline is multiplied by 86.2 and divided by 100. Housing 68.4, groceries 92.5 and utilities 91.2 are shown for context and not separately weighted, because the composite already carries MERIC's weighting. Note how much milder the non-housing discounts are: outside shelter, Mississippi is roughly 8% cheaper than the national average, not the 14% the composite suggests.
- Differential. The dollar and percentage difference against the baseline is taken from the scaled result, which is what the headline output and the monthly view report.
Worked Example
Using this calculator's baseline scenario: a household needing $75,000.00 a year to sustain a standard basket of goods (housing, groceries, utilities, transportation, and healthcare), priced at the U.S. national average (composite index 100.0).
- National baseline. $75,000.00 is the reference spending level at the national-average price level (index 100.0).
- Apply Mississippi's composite index. Mississippi's composite index of 86.2 (rank #48 nationally) means local prices run 13.8% below the national basket. Scaling: $75,000.00 × (86.2 ÷ 100) = $64,650.00.
- Dollar differential. $64,650.00 − $75,000.00 = -$10,350.00, so a household living in Mississippi needs its budget to shrink by that amount to match the same standard of living.
- Percentage and monthly view. That is -13.8% of the baseline, or $5,387.50/mo in Mississippi versus $6,250.00/mo nationally.
Mississippi runs meaningfully cheaper than the national baseline, with housing costs (index 68.4, 31.6 points below average) the largest single driver of the gap.
Costing the Discount: What a Dollar of National Budget Buys Here
Mississippi has the widest below-parity gap in this batch, and the arithmetic of a large discount is not symmetric with the arithmetic of a large premium, which is where most of the errors come from.
The marginal cost of the next unit. Each additional $1,000 of national-baseline budget costs $862.00 in Mississippi, a saving of $138.00 per $1,000. The engine returns $64,650.00 on the $75,000 baseline and $65,512.00 on $76,000. At other scales: $51,720.00 on a $60,000 baseline, $86,200.00 on $100,000, $103,440.00 on $120,000. The saving grows in step, from $8,280.00 at $60,000 to $16,560.00 at $120,000, a constant 13.8%.
The reverse question. A Mississippi household asking what national standard its spending represents divides by 0.862. A $86,200.00 Mississippi budget corresponds to a $100,000 national-average standard, which the engine confirms by returning exactly $86,200.00 for a $100,000 baseline. In compensation terms, a Mississippi salary of $64,650.00 matches a $75,000 national-average salary, and a Mississippi employer offering $60,000 is offering below national-average purchasing power, not above it.
Right method against wrong method, priced. The natural shortcut is to add back the 13.8% differential: $64,650.00 x 1.138 = $73,571.70. The correct inversion is $64,650.00 / 0.862 = $75,000.00, the engine's own input. Adding back the percentage understates the national equivalent by $1,428.30. A 13.8% discount is undone by a 16.0% increase, not a 13.8% one, and treating the two as interchangeable is the single most common error in relocation arithmetic.
How the sweep table lines up with the headline. The twelve rows step the budget from one sixth to two times the entered amount and price every tier at the composite 86.2. Row 6 sits at the entered $75,000 and reads $64,650.00, the headline exactly. Row 10, at a $125,000 tier, reads $107,750.00; row 12, at $150,000, reads $129,300.00. Only the budget changes between rows, so differencing any two of them isolates the budget step cleanly: each $12,500 of tier adds $10,775.00.
What the twelve rows deliberately do not carry. No city detail, so Jackson, Oxford and the Delta all price at 86.2. No household composition, so the same tier serves a couple and a family of six. No tax and no time axis, so nothing in the column ages the index or nets a paycheck. The sweep is a scale test of one multiplication, and it is honest only as long as it is read that way.
One multiplication, and what it cannot see. The engine computes budget times 86.2 divided by 100. It does not apportion spending across categories and does not weight them. Housing at an index of 68.4 is the widest gap from parity of any figure in this batch and is what pulls the composite down, but a Gulf Coast household facing coastal insurance premiums and a Delta household facing none both receive $64,650.00 from a $75,000 baseline.
What This Does Not Account For
- Intra-state variance between major metropolitan urban centers and rural counties within Mississippi.
- Discretionary lifestyle choices, private schooling, and luxury expenditures.
- State income and property tax impacts on disposable take-home salary.
- Dynamic seasonal utility price surges during peak winter heating or summer cooling months.
Common Pitfalls
- Comparing State Averages Instead of Metro Areas: Living in a major metro area is often 20%-40% more expensive than the statewide average.
- Focusing Solely on Housing: Overlooking higher utility, transportation, or food costs in colder or remote regions.
- Ignoring Net Take-Home Pay: Comparing gross salary without factoring in state income and sales tax differentials.
- Failing to Adjust for Family Size: Larger households experience disproportionately higher grocery and healthcare expenditures.
Frequently Asked Questions
Is Mississippi expensive to live in?
What is the biggest cost factor in Mississippi?
How much salary do I need to maintain my lifestyle in Mississippi?
How often are cost of living indices updated?
Sources
- U.S. Bureau of Economic Analysis (BEA): Regional Price Parities. bea.gov/data/prices-inflation/regional-price-parities-state-and-metro-area
- U.S. Bureau of Labor Statistics (BLS): Consumer Expenditure Survey. bls.gov/cex
Also consulted: MERIC: Cost of Living Data Series (2025/2026).