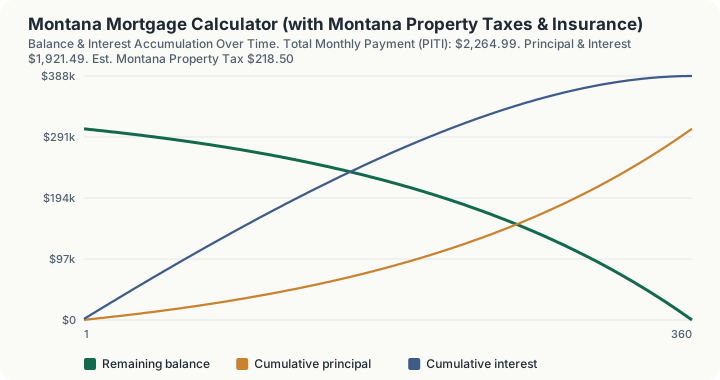
Quick Answer: A $380,000 Montana home with 20% down and a 6.5% fixed rate carries a total monthly payment (principal, interest, property tax, and insurance) of roughly $2,265.
Overview
Montana's property tax system runs on a classification structure that taxes residential property at a relatively low effective rate compared to most of the country, averaging close to 0.69% of market value statewide. Montana also has no general sales tax, which shapes the state's overall tax mix toward property and income taxes rather than consumption taxes. For a mortgage calculator, the relevant figure is the effective residential property tax rate, and this tool uses Montana's statewide average as the default for estimating your monthly escrow contribution.
Montana's housing market includes a wide range of price points, from rural agricultural properties to high-demand markets like Bozeman, Missoula, and the Flathead Valley, where prices have risen sharply and property tax bills have followed. This calculator builds a full PITI (Principal, Interest, Taxes, Insurance) monthly payment so buyers get a realistic sense of total housing cost rather than a principal-and-interest figure alone.
How This Is Calculated
The calculator works through four stages.
- Loan principal. Home price minus the down payment (home price multiplied by your down payment percentage) determines the amount financed.
- Principal and interest. The loan principal is amortized over a standard 360-month (30-year) term at your entered interest rate.
- Property tax estimate. Montana's statewide effective property tax rate of 0.69% is applied to the home price and divided by 12 for a monthly escrow figure.
- Insurance estimate. A flat $125 monthly placeholder stands in for typical homeowners insurance; actual Montana premiums vary with wildfire and severe weather risk exposure by region.
The standard fixed-rate amortization formula for monthly principal and interest $M$ is:
where $P$ is the loan principal, $r$ is the monthly interest rate, and $n$ is the number of monthly periods.
Worked Example
Using the calculator's baseline inputs:
- Home price: $380,000
- Down payment: 20% ($76,000)
- Interest rate: 6.5% APR
- Term: 30 years (360 months)
The financed loan principal is $380,000 - $76,000 = $304,000. Amortized over 360 months at 6.5%, principal and interest comes to approximately $1,921.49 per month, matching the calculator's verified test vectors. Montana's 0.69% effective property tax rate applied to the $380,000 home price gives $380,000 × 0.69% ÷ 12 = $218.50 per month in escrowed property tax. Adding the $125 insurance placeholder, total monthly PITI comes to $1,921.49 + $218.50 + $125.00 = approximately $2,264.99 per month.
What Each Input Is Worth, Priced
The amortization table walks the months. This section holds the term fixed and moves the three inputs instead, which is the comparison a buyer is actually making.
A quarter-point of rate. Moving from 6.5% to 6.625% raises principal and interest from $1,921.49 to $1,946.55, or $25.06 a month, and raises total 30-year interest from $387,732.82 to $396,756.31, a difference of $9,021.08 on the same $304,000 loan.
Two full points of rate. At 5.5% the payment is $1,726.08 and lifetime interest is $317,388.26. At 7.5% they are $2,125.61 and $461,220.45. Two points of rate is therefore $399.53 a month and $143,832.19 over the life of the loan, on an unchanged $380,000 purchase.
Cutting the down payment from 20% to 5%. The financed principal rises from $304,000 to $361,000 and total monthly PITI rises from $2,264.99 to $2,625.27, an increase of $360.28 a month. Lifetime interest rises by $72,700.34. Note what is not in that $360.28: no mortgage insurance. The calculator adds no PMI at any down payment, so a 5% buyer's real payment is higher than the figure shown by the whole PMI premium.
Zero down. The loan becomes the full $380,000, PITI reaches $2,745.36 and lifetime interest reaches $484,667.97. That is $480.37 a month above the 20% baseline, again with no mortgage insurance included.
Raising the price 25%. A $475,000 Montana home at 20% down finances $380,000, exactly what the $380,000 home finances at 0% down, so principal and interest are identical at $2,401.86. The difference between the two cases is entirely in the tax line: $273.13 a month against $218.50, because the 0.69% is applied to the purchase price. Total PITI is $2,799.99.
The two fixed assumptions worth naming. The insurance line is a flat $125.00 a month at every price, so a $2,000,000 Montana home and a $200,000 one carry the identical insurance figure in this model. And the property tax line is 0.69% of the purchase price held constant for 360 months, so no reappraisal, no valuation growth and no millage change ever moves it.
What This Does Not Account For
- No private mortgage insurance is added at any down payment. Setting the down payment to 5% or 0% raises the payment by principal and interest alone, understating the real monthly cost of a low-equity loan.
- Insurance is a flat $125.00 a month regardless of home price, and the property tax line is a fixed percentage of the purchase price held constant across all 360 months.
- County and market-specific reappraisal cycles. Montana reappraises property periodically, and fast-appreciating markets like Bozeman, Missoula, and Kalispell can see tax bills rise faster than the statewide average implies.
- Wildfire insurance risk premiums. Montana properties in wildland-urban interface zones can carry meaningfully higher homeowners insurance premiums than the flat $125 estimate used here, particularly in western Montana.
- Private mortgage insurance (PMI). This calculator's default assumes 20% down, which typically avoids PMI; a smaller down payment adds a cost not modeled here.
- HOA and special district assessments. Many newer Montana subdivisions and resort-area developments carry homeowners association dues or special improvement district assessments not included in this estimate.
- Non-resident and second-home tax treatment. Montana's property tax classification can differ for non-primary residences in some circumstances, which this calculator does not distinguish.
Common Pitfalls
- Underestimating homeowners insurance in wildfire-exposed areas. Buyers in western Montana counties near forested terrain often pay more than the flat placeholder used in this calculator, and some insurers have restricted coverage in the highest-risk zones.
- Assuming statewide averages apply to fast-growth markets. Gallatin County (Bozeman) and Missoula County have both seen home values and effective tax bills climb faster than Montana's rural counties.
- Forgetting PMI below 20% down. Since this calculator's baseline assumes 20% down, buyers financing with less should add an estimated PMI cost separately.
- Comparing a 30-year quote against a 15-year quote without adjusting the term. This calculator models the standard 360-month amortization; shortening the term raises the monthly payment but cuts total lifetime interest substantially.
- Ignoring how Montana's lack of sales tax shifts the overall tax burden onto property and income. Buyers relocating from a high-sales-tax, low-property-tax state may misjudge their total Montana tax picture if they only compare property tax rates in isolation.
Frequently Asked Questions
What is the average property tax rate in Montana?
Does Montana have a state sales tax that affects housing costs?
How does Montana's property reappraisal cycle affect my tax bill over time?
Is homeowners insurance more expensive in Montana due to wildfire risk?
Does this calculator assume a 20% down payment?
Sources
- Montana Department of Revenue: Property classification and statewide effective tax rate data. mtrevenue.gov
- Consumer Financial Protection Bureau: Regulation Z (Truth in Lending Act) and mortgage disclosure standards. ecfr.gov/current/title-12/chapter-X/part-1026
- Federal Reserve Bulletin: Historical mortgage interest rate benchmarks. federalreserve.gov