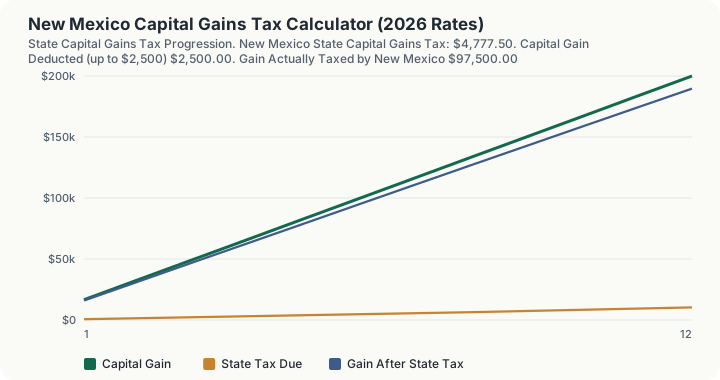
Quick Answer: On a $100,000 capital gain layered on $75,000 of other income, New Mexico's tax is $4,777.50, an effective rate of 4.78%. New Mexico deducts 100% of net capital gains up to $2,500 under NMSA 1978 § 7-2-34. HB 252 (2024) repealed the old 40%-of-all-gains deduction, so most taxpayers now get $2,500 and no more.
A $2,500 Exclusion, Then the Ordinary Ladder
New Mexico does not tax capital gain under a separate schedule. It allows a deduction and then runs what is left through the ordinary income brackets, stacked on top of the other taxable income you enter.
At the defaults, $100,000 of gain over $75,000 of other income, the calculator excludes $2,500 under the generally available prong of the state deduction, leaving $97,500.00 of taxable gain, and returns $4,777.50 of New Mexico tax. That is an effective rate of 4.78% measured against the full gain and a marginal rate of 4.90%, with $95,222.50 retained.
The gap between those two rates is the exclusion doing its work: $2,500 comes off the top of the stack at the 4.90% marginal rate. The twelve-row sweep reflects the same structure, taxing a $16,666.67 tier at $694.17 in row 1 and $200,000 at $10,302.50 in row 12.
How This Is Calculated
New Mexico used to deduct 40% of every capital gain. It does not any more. HB 252 repealed that general deduction, and what remains is the greater of two much narrower prongs: 100% of net capital gain up to $2,500, or 40% of up to $1,000,000 of gain from the sale of a New Mexico business. The $2,500 prong is the one available to everyone, and it is a fixed dollar amount, so it matters on a small gain and rounds to nothing on a large one.
This calculator applies the $2,500 prong, since it does not collect a business-sale input. The deduction comes off before the rest is stacked on other income and run through the 1.5% to 5.9% schedule.
What actually happens to your numbers:
- Start with the net gain. Capital losses and loss carryforwards are netted against the gain before anything else happens.
- Stack the gain on your other income. Ordinary income fills the lower brackets first and the gain sits on top of it, so the gain is taxed at whatever rates are still open above your salary. The same gain costs a high earner more than it costs a low earner. Enter other income as a taxable-income figure: the calculator does not subtract a standard deduction or personal exemption for you.
- Take the capital gains deduction (NMSA 1978 § 7-2-34). Subtract the lesser of $2,500 or the net capital gain before anything is stacked or bracketed. The business-sale prong is not applied, because the calculator does not ask whether a New Mexico business was sold.
- Walk the brackets. The slice of the gain that falls in each band is multiplied by that band's rate, and the pieces are added together.
- Effective rate. Total New Mexico tax divided by the whole realized gain. On a graduated schedule this sits below the top marginal rate, because the lower slices were taxed at lower rates.
- Net proceeds. Subtract the state tax from the gain to get what you keep before federal tax.
Worked Example
Consider an investor in New Mexico who realizes $100,000 in capital gains on top of $75,000 in baseline ordinary income for the year.
- Apply the deduction first. NMSA 1978 § 7-2-34 deducts 100% of net capital gains capped at $2,500, so $2,500 comes out of the $100,000 gain. $97,500 remains taxable.
- Stack the income. The $75,000 of baseline ordinary income fills the lower brackets first, so the remaining $97,500 of gain stacks on top of it.
- Apply the marginal brackets. The $75,000 of other income is already inside the 4.90% bracket, which runs from $66,500 to $210,000 for a single filer, and $172,500 of combined income stays inside it, so the entire $97,500 of taxable gain is taxed at 4.90%: $4,777.50.
- Effective rate. Dividing $4,777.50 by the full $100,000 realized gain gives an effective rate of 4.78%, marginally below the 4.90% bracket rate. The $2,500 cap is a small absolute benefit on a large gain.
- Net proceeds. After paying $4,777.50 in state tax, the investor keeps $95,222.50 of the $100,000 gain, before any federal tax applies.
Without any deduction, the same gain would produce $4,900.00. A calculator still applying the repealed 40% rule would report roughly $2,940.00, understating the liability by about $1,838.
The 4.90% Line and What Sits Around It
Each additional $1,000 of gain costs $49.00 at the defaults, moving the tax from $4,777.50 at $100,000 of gain to $4,826.50 at $101,000.
The threshold walk. The stored schedule steps from 4.90% to 5.90% at $210,000 of total income, which with $75,000 of other income and the $2,500 exclusion means a gain of $137,500. At $137,400 of gain the tax is $6,610.10 and the marginal rate output reads 4.90%. At $137,600 it is $6,620.90 and the marginal rate reads 5.90%. Those $200 of gain cost $10.80 against the $9.80 they would have cost below the line, so the edge is worth $1.00. The effective rate reads 4.81% on both sides.
The other-income field is worth $542.00 here. Set other taxable income to $0 and the same $100,000 gain is taxed at $4,235.50 instead of $4,777.50, an effective 4.24%, because the gain then fills the lower bands of the schedule on its way up rather than starting above them.
Filing status is worth $50.00 at the defaults. Married filing jointly returns $4,727.50 against the single filer's $4,777.50. The whole difference is one band boundary: the joint schedule's 4.70% band runs from $50,000 to $100,000 where the single schedule's ends at $66,500, so $25,000 of this stack that a single filer pays 4.90% on a joint filer pays 4.70% on, and $25,000 x 0.20% = $50.00. Above $100,000 the two schedules charge the same 4.90% and the saving stops growing.
The exclusion has a hard edge of its own. It is a flat $2,500, not a percentage, so it is worth the same $2,500 of removed gain whether the gain is $10,000 or $10,000,000. As a share of the tax it therefore shrinks continuously: it is the entire difference between the 4.78% effective rate and the 4.90% marginal rate at $100,000 of gain, and a rounding error at $10,000,000.
The reverse question: how much gain can be realised before the 5.90% band begins? With $75,000 of other income and the $2,500 exclusion applied, $137,400 of gain keeps the marginal rate at 4.90% and costs $6,610.10. Crossing costs $1.00 on the next $200, which makes this one of the cheapest bracket edges in this batch of calculators.
The schedule this page walks, and where it came from. The bracket bounds behind every figure above are NMSA 1978 Section 7-2-7 as amended by Laws 2024 ch. 67, the codification of HB 252 (2024), which applies to taxable years beginning on or after January 1, 2025 and is the schedule in force for 2026. For a single filer it runs 1.5% to $5,500, 3.2% to $16,500, 4.3% to $33,500, 4.7% to $66,500, 4.9% to $210,000 and 5.9% above that. This page previously carried a disclosure that the stored bounds were the superseded pre-HB-252 schedule, missing the 4.3% band entirely and using a 1.7% bottom rate; that defect was corrected on 2026-08-31 once the statute itself became readable, and the disclosure has been removed because it no longer describes this calculator.
What This Does Not Account For
While this calculator provides penny-exact state statutory modeling, additional federal and transactional complexities warrant supplementary review: - Federal Capital Gains Taxes: Federal long-term brackets (0%, 15%, 20%) and short-term ordinary rates up to 37% under IRC § 1. - Net Investment Income Tax (NIIT): The 3.8% surtax on net investment income under IRC § 1411 for single filers over $200,000 (married joint over $250,000). - Alternative Minimum Tax (AMT): Federal AMT calculations under IRC § 55 impacting incentive stock option (ISO) exercise spread. - Section 1031 Like-Kind Exchanges: Tax deferral mechanisms for real property held for productive use in trade, business, or investment. - Qualified Small Business Stock (QSBS): Federal Section 1202 gain exclusions where state conformity varies significantly. - New Mexico's Business-Sale Deduction Prong: NMSA 1978 § 7-2-34 alternatively allows 40% of up to $1,000,000 of net capital gain from the sale of a business sourced to New Mexico, and a taxpayer takes whichever prong is greater. This calculator applies only the generally available $2,500 prong, because it does not collect a business-sale input.
Common Pitfalls
- Relying on the Repealed 40% Deduction: HB 252 (2024) replaced New Mexico's general 40%-of-all-gains deduction with a $2,500 cap for tax years beginning in 2025. Sources still serving the pre-2025 text of NMSA 1978 § 7-2-34 will understate New Mexico tax substantially.
- Failing to Track Holding Periods: New Mexico's $2,500 deduction does not turn on holding period, but the federal treatment does: assets held one year or less are taxed at ordinary federal rates rather than the long-term brackets.
- Underestimating Multi-State Apportionment: Selling real estate or business assets located in other jurisdictions triggers multi-state non-resident return filing obligations.
- Neglecting Underpayment Penalties: Substantial one-time liquidity events require prompt estimated tax payments within the quarter of sale to avoid statutory penalties.
- Mismatched Cost Basis Records: Failure to document reinvested dividends, stock splits, or structural return-of-capital distributions leads to inflated taxable gain calculations.
Frequently Asked Questions
Does New Mexico have a state capital gains tax?
How are short-term and long-term capital gains taxed in New Mexico?
Are retirement account distributions subject to capital gains tax in New Mexico?
Can capital losses offset capital gains in New Mexico?
When are estimated state tax payments required on capital gains?
Sources
- New Mexico Taxation and Revenue Department: 2026 Statutory Individual Income Tax Rate Schedules. tax.newmexico.gov
- Internal Revenue Service (IRS): Publication 544 (Sales and Other Dispositions of Assets) and Publication 550 (Investment Income and Expenses). irs.gov/publications/p544
Also consulted: NMSA 1978 § 7-2-34, as amended by HB 252 (2024): Capital gains deduction, the greater of 100% of net capital gains capped at $2,500 or 40% of up to $1,000,000 of gain from a New Mexico business sale, effective for tax years beginning in 2025.