Quick Answer: A $1,000 taxable purchase in New Mexico costs $76.75 in combined state and local sales tax, for a total of $1,076.75 out the door.
A Low State Rate Carried Upward by Local Increments
Sales tax in New Mexico is layered rather than flat. Local jurisdictions (cities, counties, and in some cases special taxing districts) are free to add their own surcharges on top of that, and the statewide average of those add-ons is 2.80%, which brings the typical combined rate to 7.68%. Combine that with the state's own 4.88% rate and the average total a shopper pays works out to 7.68%.
That puts New Mexico a bit above the roughly 7.3% average combined rate seen across the states that levy a general sales tax. Anyone comparing New Mexico to a neighboring state on affordability should look past the headline state rate alone. The local layer can matter just as much to what actually shows up at checkout. Online sellers shipping into New Mexico face the same layered math as brick-and-mortar retailers: the destination address, not the seller's location, determines which local rate stacks on top of the 4.88% state floor.
How This Is Calculated
New Mexico levies a gross receipts tax rather than a sales tax. The legal liability is the seller's, it applies to services as broadly as it applies to goods, and the rate is genuinely local: the state component is 4.875% and the average local component is 2.80%, for a combined 7.675% and $76.75 on a $1,000 transaction. Because services are inside the base, professional fees, construction and repair work that would be untaxed in most states are taxable in New Mexico.
The state and local components of the gross receipts rate are added and applied together:
The calculation goes:
- Read the purchase price. The full pre-tax amount you enter becomes the taxable base.
- No item-level exemption filtering. New Mexico deducts groceries and certain medical services from the base. Those deductions are not modeled here.
- Multiply by the state rate. This produces the state portion of the bill.
- Apply the local component. The 2.80% average covers municipal and county gross receipts increments, which vary substantially between Albuquerque, Santa Fe and rural counties.
- Add the pieces together. State tax plus local tax gives the total tax, and adding that to the purchase price gives the amount you actually pay.
Worked Example
For a $1,000 taxable purchase in New Mexico:
- Starting purchase price. The buyer rings up a $1,000.00 taxable retail purchase in New Mexico, the baseline amount before any tax is applied.
- State portion. New Mexico's statutory state sales tax rate of 4.88% applies to the full purchase amount: $1,000.00 × 4.88% = $48.75 owed to the state.
- Local portion. Local municipal, county, and special-district surcharges add an average of 2.80% on top of that: $1,000.00 × 2.80% = $28.00 more.
- Combined tax due. Summing the two pieces, $48.75 in state tax plus $28.00 in local surcharge comes to $76.75 in total sales tax owed on the transaction.
- Total out-of-pocket cost. Adding that $76.75 in tax to the $1,000.00 purchase price brings the buyer's total out-of-pocket cost to $1,076.75.
This example uses New Mexico's statewide average local rate of 2.80%; actual combined rates vary by city and county, so a real receipt could show a combined rate above or below the 7.68% average used here.
Where the Local Layer Does More Work Than Anywhere Else Here
New Mexico's combined rate is 7.68%: a 4.875% state rate plus a 2.80% stored statewide average local rate. The local component is the largest in this group of states, and it carries an unusually big share of the total.
The local toggle is the one real step on this page, and it is worth $28.00 on $1,000. With the surcharge included a $1,000 purchase carries $76.75 of tax and costs $1,076.75. With it excluded the tax falls to $48.75 and the cost to $1,048.75. The local layer is 36% of the total tax at any purchase size, which is why a New Mexico figure computed at the state rate alone is so badly wrong. On a $30,000 vehicle the switch is worth $840.00, the gap between $2,302.50 and $1,462.50.
Each additional $100 of purchase costs $7.68 with local tax included and $4.88 without. Moving the entry from $1,000 to $1,100 moves the tax from $76.75 to $84.43.
The reverse question: how much can be spent before the tax reaches $100? At $1,302 the tax is $99.93 and at $1,303 it is exactly $100.00.
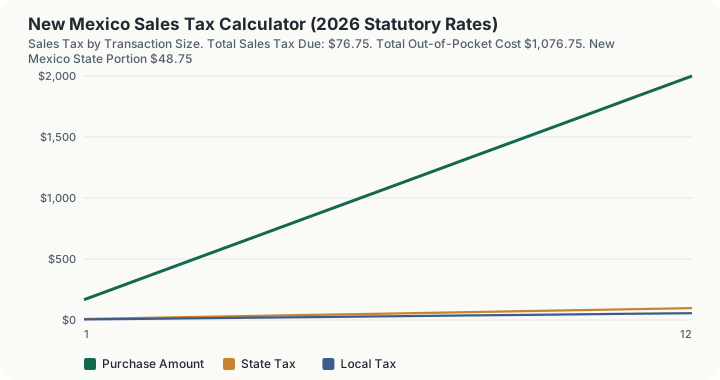
Reading the schedule. Row 1 splits a $166.67 tier into $8.13 of state tax and $4.67 of local tax. Row 12 splits $2,000.00 into $97.50 and $56.00. The two columns are components at that tier, not running totals.
Right method against wrong method, priced. Reversing a receipt is the usual failure. A total of $1,076.75 does not contain 7.68% of itself in tax. Taking 7.68% of the gross gives $82.69 and a net of $994.06, overstating the tax by $5.94 against the correct $76.75. Dividing the gross by 1.0768 returns the $1,000.00 net exactly.
A caution about the 2.80%. New Mexico's gross receipts tax rate varies substantially by location, and 2.80% is a statewide average of the local increments rather than the rate at any particular address. The calculator collects no address, so the $76.75 is a benchmark rather than a quote.
What This Does Not Account For
- The 2.80% local figure is a statewide average of local gross receipts increments, which vary substantially by location. There is no address input, so the $76.75 on $1,000 is a benchmark rather than a quote.
- New Mexico levies a gross receipts tax on the seller rather than a true sales tax on the buyer. The calculator applies the combined rate to the price you enter as though it were a buyer-side sales tax, which is how it is passed through in practice but not how the statute is framed.
- The calculator does not extract tax from a tax-inclusive total.
- Statutory exemptions on unprepared groceries, prescription medications, or manufacturing equipment.
- Special industry excise taxes (lodging hotel taxes, vehicle rental fees, alcohol/tobacco excise).
- Use tax compliance on out-of-state untaxed online purchases.
- B2B resale certificate exemptions or direct pay permit programs.
Common Pitfalls
- Confusing State and Combined Rates: Quoting the state base rate without factoring in local city and county add-on taxes.
- Overlooking Consumer Use Tax: Failing to self-report and remit use tax on untaxed out-of-state purchases on your state income tax return.
- Missing Annual Sales Tax Holidays: Many states offer annual tax-free weekends for back-to-school items, severe weather supplies, or energy-efficient appliances.
- Failing to Collect Resale Certificates: Selling wholesale without collecting valid exemption certificates exposes sellers to full sales tax liability upon audit.
Frequently Asked Questions
What is the sales tax rate in New Mexico?
Are groceries taxed in New Mexico?
How does use tax differ from sales tax?
Are digital goods and SaaS taxable in New Mexico?
Sources
- New Mexico Taxation and Revenue Department: 2026 Sales and Use Tax Rate Schedules. tax.newmexico.gov
- Streamlined Sales Tax Governing Board (SSTGB): State Taxability Matrix. streamlinedsalestax.org/for-businesses/taxability-matrix