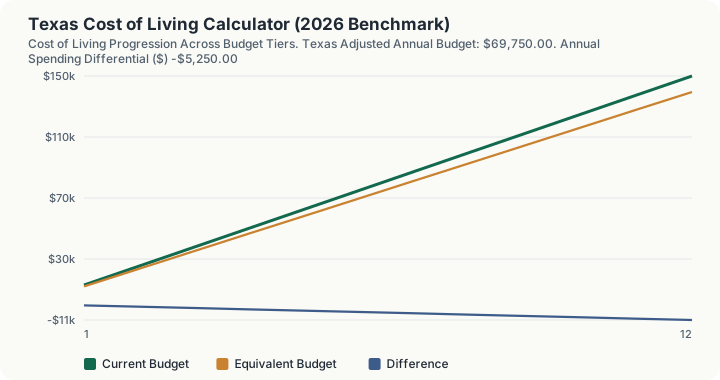
Quick Answer: Texas's cost of living is 7.0% below the U.S. national average (composite index 93.0), so a $75,000.00 national-average household budget costs about $69,750.00 a year in Texas.
Texas Against the National Basket
Texas is the second-most populous state, with no state income tax. On MERIC's composite cost-of-living index it registers 93, or 7% below the 100.0 national baseline.
Within the South, Texas is roughly mid-pack among Southern states. The composite figure is driven mainly by housing (index 84.2), with groceries (index 94.5) and utilities (index 103.5) playing smaller roles.
That combination puts Texas in the more affordable lower third of state rankings, a useful anchor point for anyone weighing a cross-state move, a remote-work relocation, or a corporate cost-of-labor adjustment against the national average. It is also worth remembering that a single statewide figure can't capture the spread between Texas's own metro and rural markets.
That translates to roughly $5,250 of annual budget movement on a $75,000 reference figure, driven largely by housing running 15.8 points below the 100.0 mark. Transportation, healthcare, and general goods and services are folded into the composite calculation too, even though MERIC does not publish them as standalone state indices.
Key Index Components for Texas:
- Composite Benchmark Index: 93.0 (Rank #34)
- Housing Cost Index: 84.2
- Utilities Cost Index: 103.5
- Grocery Cost Index: 94.5
How This Is Calculated
Texas is cheap on housing and not cheap on power. Housing reads 84.2 while utilities sit at 103.5, above the national line and the highest utility index of any state with a composite under 95. Groceries at 94.5 fall between the two, and the composite lands at 93.0, rank 34 of 50. The calculator uses that composite.
- Baseline budget. You enter annual household spending priced at the national benchmark, index 100.0.
- Composite lookup. Texas's composite index of 93.0 is read from the 2026 MERIC state table, along with its rank of #34 among the 50 states.
- Single-factor scaling.
calculateStateCostOfLivingcomputesadjustedStateCost = budget x 93.0 / 100. That single multiplication is the entire headline calculation. The housing (84.2), grocery (94.5) and utilities (103.5) sub-indices are carried in the 2026 table and are displayed on this page as context, but no code path feeds them into the headline figure or into any row of the schedule: there is no category apportionment step, no weighting step and no threshold of any kind in the function. - Differential. The dollar and percentage difference against the baseline is taken from the scaled result, which is what the headline output and the monthly view report.
- Build the 12-row multiplier schedule. The table below the result is the headline calculation repeated at twelve budget levels. Row
iprices a budget tier ofbaseline x i / 6, so the tiers climb from $12,500 at row 1 to $150,000 at row 12 on the default baseline, and every row is scaled by the same composite 93.0. Only the tier changes from row to row, which is why the table's Difference column, the row's own tier subtracted from the row's own scaled figure, works out to a constant -7.0% of the tier and grows in equal steps of -$875.00.
Worked Example
Using this calculator's baseline scenario: a household needing $75,000.00 a year to sustain a standard basket of goods (housing, groceries, utilities, transportation, and healthcare), priced at the U.S. national average (composite index 100.0).
- National baseline. $75,000.00 is the reference spending level at the national-average price level (index 100.0).
- Apply Texas's composite index. Texas's composite index of 93.0 (rank #34 nationally) means local prices run 7.0% below the national basket. Scaling: $75,000.00 × (93.0 ÷ 100) = $69,750.00.
- Dollar differential. $69,750.00 − $75,000.00 = -$5,250.00, so a household living in Texas needs its budget to shrink by that amount to match the same standard of living.
- Percentage and monthly view. That is -7.0% of the baseline, or $5,812.50/mo in Texas versus $6,250.00/mo nationally.
Texas runs meaningfully cheaper than the national baseline, with housing costs (index 84.2, 15.8 points below average) the largest single driver of the gap.
Pricing the Texas Adjustment, Forwards and Backwards
The marginal cost of the next $1,000 of budget
Sweeping baselineAnnualBudget from $75,000 to $77,000 in $1,000 steps returns $69,750.00, $70,680.00 and $71,610.00. The step is identical every time. Each additional $1,000 of national-baseline budget costs $930.00 in Texas.
That constant is not an approximation over a narrow range. The engine holds no bracket, no exemption, no cap and no phase-out, so the marginal figure is $930.00 per $1,000 at the $10,000 input minimum and the same $930.00 per $1,000 at the $10,000,000 maximum. The reported differential percentage stays pinned at -7.0% across the whole sweep for the same reason. Any page in this corpus that describes a cost-of-living cliff or a break point is describing something this engine does not contain.
The reverse question: what baseline supports $100,000 of Texas spending
The forward calculation answers "what does my basket cost here". The relocation question is the inverse: what national-baseline budget, and therefore what salary at national pricing, holds purchasing power constant at a target Texas figure. Sweeping the baseline in $100 steps, $107,500 returns $99,975.00 and $107,600 returns $100,068.00, so the $100,000 crossing sits between those two rows, and each $100 of baseline moves the Texas figure by $93.00. Read the other way, that is the salary translation: a job priced at national-average cost levels needs roughly $107,600 to fund $100,000 of Texas living costs.
Right method against wrong method, priced against South Dakota
A household spending $69,750.00 in Texas and pricing a move to South Dakota cannot add the 4.8-point index gap to its Texas spending. Subtracting index points and applying the remainder as a percentage treats the two indices as if they shared a base, and they do not: each is measured against 100.0, not against the other.
The wrong method. 97.8 minus 93.0 is 4.8 points, so add 4.8% to $69,750.00: $73,098.00.
The right method. Both figures are scaled from the same $75,000.00 national baseline: $69,750.00 in Texas and $73,350.00 in South Dakota.
The error. $252.00 on a single year, and the wrong method understates the South Dakota figure. The gap scales linearly with the budget, so a household running twice this budget carries twice the error.
Checking row six against the headline
Row 6 of the schedule prices the default $75,000 tier at the composite 93.0 and returns $69,750.00, which is the headline figure for the same $75,000 and comes out of the same compute() call. The two agree to the cent because they are the same multiplication. The housing sub-index of 84.2 is printed further up the page as a context reading and is used by neither: nothing in Texas's code path multiplies a budget by it.
Rows 5 and 7 bracket that row and confirm the shape. Row 5 returns $58,125.00 on a $62,500 tier and row 7 returns $81,375.00 on an $87,500 tier, each $11,625.00 away from row 6, because a $12,500 step in the tier always moves the scaled figure by that same amount. The column is therefore monotonic in the budget and reads as a single series, and the difference between any two rows is purely the difference in their tiers.
What This Does Not Account For
- The sub-indices do not reach the headline. Housing 84.2, groceries 94.5 and utilities 103.5 are in the 2026 table and are shown as context figures only, but
calculateStateCostOfLivingmultiplies your budget by the composite 93.0 and by nothing else. The headline is one factor, not a weighted basket. - The schedule is not a category breakdown. Every row applies the composite 93.0 to its own budget tier, so moving from row 5 ($58,125.00) to row 6 ($69,750.00) to row 7 ($81,375.00) reflects the change in tier and nothing else. No row isolates housing, groceries or utilities.
- There is no time axis. The composite is a single 2026 quarter reading, and the schedule sweeps budget levels rather than years, so nothing here projects inflation forward or discounts a future cost back.
- There is no threshold, cliff or bracket in this model. The output is strictly proportional to the input at $930.00 per $1,000 of baseline, at every budget level the inputs allow.
- The composite is a single statewide number with no county, metro or ZIP resolution, and the calculator accepts no location input finer than the state.
- Intra-state variance between major metropolitan urban centers and rural counties within Texas.
- Discretionary lifestyle choices, private schooling, and luxury expenditures.
- State income and property tax impacts on disposable take-home salary.
- Dynamic seasonal utility price surges during peak winter heating or summer cooling months.
Common Pitfalls
- Comparing State Averages Instead of Metro Areas: Living in a major metro area is often 20%-40% more expensive than the statewide average.
- Focusing Solely on Housing: Overlooking higher utility, transportation, or food costs in colder or remote regions.
- Ignoring Net Take-Home Pay: Comparing gross salary without factoring in state income and sales tax differentials.
- Failing to Adjust for Family Size: Larger households experience disproportionately higher grocery and healthcare expenditures.
Frequently Asked Questions
Is Texas expensive to live in?
What is the biggest cost factor in Texas?
How much salary do I need to maintain my lifestyle in Texas?
How often are cost of living indices updated?
Sources
- U.S. Bureau of Economic Analysis (BEA): Regional Price Parities. bea.gov/data/prices-inflation/regional-price-parities-state-and-metro-area
- U.S. Bureau of Labor Statistics (BLS): Consumer Expenditure Survey. bls.gov/cex
- Texas Comptroller of Public Accounts, the official state tax authority for Texas rates, rules and forms. comptroller.texas.gov
Also consulted: MERIC: Cost of Living Data Series (2025/2026).