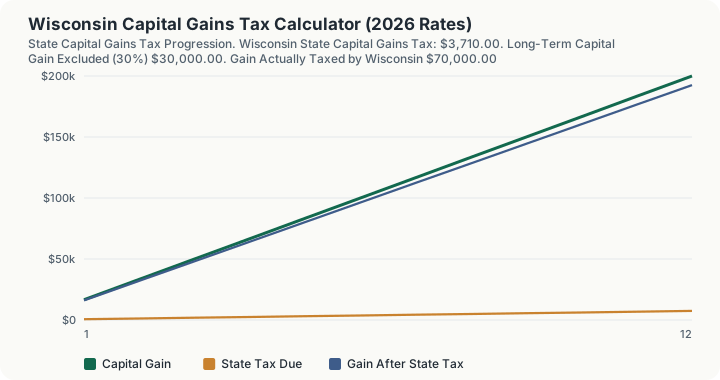
Quick Answer: On a $100,000 long-term capital gain layered on $75,000 of other income, Wisconsin's tax is $3,710.00, an effective rate of 3.71%. Wisconsin excludes 30% of net long-term capital gain under Wis. Stat. § 71.05(6)(b)9., so only $70,000 reaches the brackets. Without the exclusion the bill would be $5,300.00.
Overview
Wisconsin grants a 30% exclusion for net long-term capital gain. Under Wis. Stat. § 71.05(6)(b)9., 30% of net long-term capital gain is subtracted from Wisconsin taxable income, so 70% of the gain is exposed to the graduated brackets that run from 3.50% to a top marginal rate of 7.65%. A companion provision, Wis. Stat. § 71.05(6)(b)9m., raises the exclusion to 60% for net long-term gain on farm assets: livestock, farm equipment, farm real property, and farm depreciable property.
Two mechanical details matter. Gains and losses are netted first, and the percentage applies to the net figure. And the exclusion does not reach depreciation recapture or gain from lottery winnings. Short-term gain gets no exclusion at all.
That's because Wisconsin evaluates capital gains alongside your other taxable earnings, not as their own separate bucket: when they land on top of baseline salary or business income, they get taxed at your top marginal bracket, reaching up to 7.65%.
That matters for high-net-worth individuals, portfolio managers, corporate executives, and real estate investors alike, since state income taxes significantly affect net internal rates of return (IRR) on capital dispositions, 1031 exchange planning, installment sale structuring, and equity compensation exercises (ISOs, NSOs, and RSUs).
Institutional wealth managers and private equity underwriters have to weigh both statutory tax rates and multi-jurisdictional residency rules when running these numbers. Publicly traded securities, privately held business interests, real property, digital assets: whatever is being sold, evaluating the state-level tax exposure is a key part of pre-liquidity tax modeling and post-sale wealth preservation.
Proper capital asset planning in Wisconsin means tracking taxable events across both federal and state reporting cycles. Timing and holding structure drive net after-tax proceeds, so investors need to look closely at how federal adjusted gross income (AGI) baselines interact with state modifications before closing on any substantial transaction.
How This Is Calculated
Wisconsin subtracts 30% of net long-term capital gain from the state tax base, so 70% of a qualifying gain runs the brackets. The subtraction doubles to 60% for long-term gain on farm assets, meaning livestock, farm equipment, farm real property, and depreciable farm property. Depreciation recapture and lottery winnings gain do not qualify for either figure, and short-term gain gets nothing.
This calculator applies the general 30% subtraction; it has no farm-asset input. Gains and losses are netted before the percentage is applied, and what survives is stacked on other income.
Working through it:
- Start with the net gain. Capital losses and loss carryforwards are netted against the gain before anything else happens.
- Stack the gain on your other income. Ordinary income fills the lower brackets first and the gain sits on top of it, so the gain is taxed at whatever rates are still open above your salary. The same gain costs a high earner more than it costs a low earner. Enter other income as a taxable-income figure: the calculator does not subtract a standard deduction or personal exemption for you.
- Take the 30% exclusion (Wis. Stat. § 71.05(6)(b)9.). Subtract 30% of the net long-term gain before the remainder is stacked or bracketed, leaving 70% in the base. The 60% farm-asset rate under § 71.05(6)(b)9m. is not applied here.
- Walk the brackets. The slice of the gain that falls in each band is multiplied by that band's rate, and the pieces are added together.
- Effective rate. Total Wisconsin tax divided by the whole realized gain. On a graduated schedule this sits below the top marginal rate, because the lower slices were taxed at lower rates.
- Net proceeds. Subtract the state tax from the gain to get what you keep before federal tax.
Worked Example
Consider an investor in Wisconsin who realizes $100,000 in capital gains on top of $75,000 in baseline ordinary income for the year.
- Apply the 30% exclusion first. Wis. Stat. § 71.05(6)(b)9. removes 30% of the $100,000 net long-term gain, or $30,000, from Wisconsin taxable income. $70,000 of gain remains.
- Stack the income. The $75,000 of baseline ordinary income fills the lower brackets first, so the remaining $70,000 of gain stacks on top of it.
- Apply the marginal brackets. The $75,000 of other income already sits inside the 5.30% bracket, which runs to $332,720, and $145,000 of combined income stays inside it, so the entire $70,000 of taxable gain is taxed at 5.30%: $3,710.00.
- Effective rate. Dividing $3,710.00 by the full $100,000 realized gain gives an effective rate of 3.71%, against a 5.30% marginal bracket, because 30% of the gain never enters the base.
- Net proceeds. After paying $3,710.00 in state tax, the investor keeps $96,290.00 of the $100,000 gain, before any federal tax applies.
Had the gain been short-term, no exclusion would apply and the full $100,000 would be taxed at 5.30%, producing $5,300.00. Had it been long-term gain on farm assets, the 60% rate under § 71.05(6)(b)9m. would apply instead of 30%.
The 30% Exclusion And The 7.65% Edge
At a realized gain of $368,000. The 30% exclusion removes $110,400, leaving $257,600 that stacks on the $75,000 of other income for $332,600 of combined income, just under the $332,720 where Wisconsin's 7.65% band opens. The tax is $13,652.80 and the reported marginal bracket is 5.30%.
At a realized gain of $368,300, three hundred dollars later. The tax is $13,666.05 and the marginal bracket is 7.65%. The exclusion is what makes this edge sit where it does: because only 70% of the gain enters the base, it takes $3.33 of gain to move $1.00 of taxable income across the threshold, so the edge in gain terms lands at roughly $368,171 rather than at $257,720.
The marginal cost of the next $1,000, in both bands. At the default $100,000 gain, raising it to $101,000 moves the tax from $3,710.00 to $3,747.10: $37.10 per $1,000, which is 5.30% of the 70% that survives the exclusion. Above the edge, moving from $400,000 to $401,000 moves the tax from $15,363.58 to $15,417.13: $53.55 per $1,000, which is 7.65% of 70%. The exclusion converts both statutory rates into effective ones, and neither 5.30% nor 7.65% ever appears as a cost per dollar of gain.
The reverse question. A Wisconsin seller with $75,000 of other income can realize roughly $368,000 of long-term gain before the top bracket opens. Above that the cost per $1,000 rises by $16.45, so splitting a $700,000 realization across two years is worth about $5,700 at the margin.
Right method against wrong method, priced. The exclusion is the whole game. Treating the gain as fully taxable gives $5,300.00 against the $3,710.00 the engine returns, overstating by $1,590.00 on a $100,000 gain. Using the single schedule for a married couple at a $500,000 gain gives $20,718.58 against the $18,550.00 the joint schedule returns, overstating by $2,168.58, because the joint bracket bounds are a uniform four-thirds of the single ones and $500,000 of joint income does not reach the top band at all.
What This Does Not Account For
- The 60% farm-asset exclusion is not applied. The engine applies the general 30% exclusion under Wis. Stat. 71.05(6)(b)9. and nothing else, because no input on this page collects an asset class. A qualifying farm-asset gain is taxed here as though it were an ordinary long-term gain, and on the $100,000 default that overstates the base by $30,000.
- Depreciation recapture and lottery winnings gain do not qualify for the exclusion and are not separated out. Entering either as gain applies the 30% exclusion to something the statute excludes from it.
- Short-term gain gets no exclusion, and the calculator does not ask. Everything entered is treated as long-term. This calculator handles state statutory modeling with penny-exact precision, but a few federal and transactional complexities are still worth a closer look:
- Federal Capital Gains Taxes: Federal long-term brackets (0%, 15%, 20%) and short-term ordinary rates up to 37% under IRC § 1.
- Net Investment Income Tax (NIIT): The 3.8% surtax on net investment income under IRC § 1411 for single filers over $200,000 (married joint over $250,000).
- Alternative Minimum Tax (AMT): Federal AMT calculations under IRC § 55 impacting incentive stock option (ISO) exercise spread.
- Section 1031 Like-Kind Exchanges: Tax deferral mechanisms for real property held for productive use in trade, business, or investment.
- Qualified Small Business Stock (QSBS): Federal Section 1202 gain exclusions where state conformity varies significantly.
- Wisconsin's 60% Farm-Asset Exclusion: Wis. Stat. § 71.05(6)(b)9m. doubles the exclusion to 60% for net long-term gain on livestock, farm equipment, farm real property, and farm depreciable property. This calculator applies the general 30% rate, because it does not collect an asset-class input.
- Depreciation Recapture and Lottery Gain: Neither qualifies for the Wisconsin exclusion, so a gain that includes recapture is excluded by less than the calculator shows.
Common Pitfalls
- Overpaying by Skipping the 30% Exclusion: Wisconsin is not a state that taxes long-term capital gain at full ordinary rates. Failing to claim the Wis. Stat. § 71.05(6)(b)9. exclusion on a $100,000 long-term gain costs $1,590 at the 5.30% bracket, and more if the assets are farm assets eligible for the 60% rate.
- Failing to Track Holding Periods: The Wisconsin exclusion applies only to net long-term gain. Assets held one year or less get no exclusion at the state level and carry higher federal rates on top of that.
- Underestimating Multi-State Apportionment: Selling real estate or business assets located in other jurisdictions triggers multi-state non-resident return filing obligations.
- Neglecting Underpayment Penalties: Substantial one-time liquidity events require prompt estimated tax payments within the quarter of sale to avoid statutory penalties.
- Mismatched Cost Basis Records: Failure to document reinvested dividends, stock splits, or structural return-of-capital distributions leads to inflated taxable gain calculations.
Frequently Asked Questions
Does Wisconsin have a state capital gains tax?
How are short-term and long-term capital gains taxed in Wisconsin?
Are retirement account distributions subject to capital gains tax in Wisconsin?
Can capital losses offset capital gains in Wisconsin?
When are estimated state tax payments required on capital gains?
Sources
- Wisconsin Department of Revenue: 2026 Statutory Individual Income Tax Rate Schedules. revenue.wi.gov
- Internal Revenue Service (IRS): Publication 544 (Sales and Other Dispositions of Assets) and Publication 550 (Investment Income and Expenses). irs.gov/publications/p544
Also consulted: Wis. Stat. § 71.05(6)(b)9. and 9m.: 30% exclusion for net long-term capital gain, 60% for farm assets.