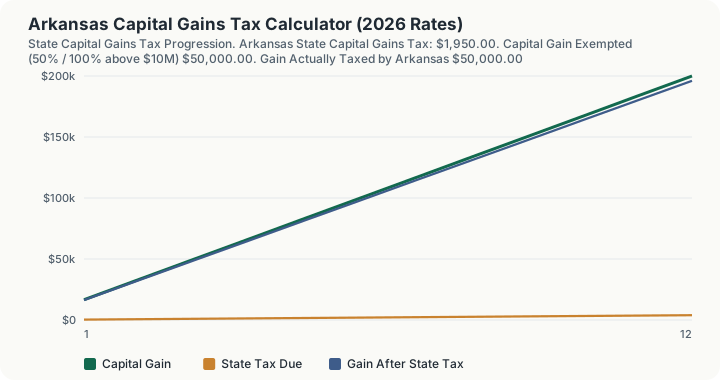
Quick Answer: On a $100,000 long-term capital gain layered on $75,000 of other income, Arkansas's tax is $1,950.00, an effective rate of 1.95%. Arkansas exempts 50% of net capital gain under Ark. Code Ann. § 26-51-815(b)(2), and 100% of gain above $10,000,000 under § 26-51-815(b)(3). Without the exemption the bill would be $3,900.00.
How Arkansas's Two Exemption Tiers Stack
Arkansas exempts 50% of net capital gain from state income tax under Ark. Code Ann. § 26-51-815(b)(2), and exempts 100% of net capital gain above $10,000,000 realized in a single tax year under § 26-51-815(b)(3). The two tiers stack: half of the first $10,000,000 is exempt, and everything above $10,000,000 is exempt in full. Only what remains runs through the graduated brackets, which start at 2.00% and top out at 3.90%.
The practical effect is a top marginal exposure of 1.95% on a long-term gain, and less than that once a single-year gain crosses $10,000,000. The exemption is for long-term gain; short-term gain is taxed as ordinary income at the full rates.
Arkansas doesn't distinguish by asset type. Stock, a business interest, real property, or digital assets all get the same 50% exemption on net capital gain, with the taxable remainder stacked on top of everything else you earned. What determines your exposure is how much other income you already have, whether the gain is long-term, and whether a single-year gain crosses the $10,000,000 line.
How This Is Calculated
Arkansas exempts half of net capital gain outright, and exempts entirely any net capital gain above $10 million realized in a single tax year. The two tiers add: 50% of the first $10 million comes out, and 100% of everything past it. Against a top rate of 3.9%, the 50% exemption caps the effective state rate on an ordinary long-term gain at about 1.95%, and the second tier means a very large sale is taxed on a shrinking share of itself.
Both exemptions are applied before the remaining gain is stacked on other income.
In order:
- Start with the net gain. Capital losses and loss carryforwards are netted against the gain before anything else happens.
- Stack the gain on your other income. Ordinary income fills the lower brackets first and the gain sits on top of it, so the gain is taxed at whatever rates are still open above your salary. The same gain costs a high earner more than it costs a low earner. Enter other income as a taxable-income figure: the calculator does not subtract a standard deduction or personal exemption for you.
- Apply both exemption tiers (Ark. Code Ann. § 26-51-815(b)(2), (b)(3)). Remove all net capital gain above $10,000,000, then remove 50% of the gain at or below that line, before anything is stacked or bracketed. Long-term gain only.
- Walk the brackets. The slice of the gain that falls in each band is multiplied by that band's rate, and the pieces are added together.
- Effective rate. Total Arkansas tax divided by the whole realized gain. On a graduated schedule this sits below the top marginal rate, because the lower slices were taxed at lower rates.
- Net proceeds. Subtract the state tax from the gain to get what you keep before federal tax.
Worked Example
Consider an investor in Arkansas who realizes $100,000 in capital gains on top of $75,000 in baseline ordinary income for the year.
- Apply the exemption first. The $100,000 gain is under the $10,000,000 threshold, so § 26-51-815(b)(2) exempts 50% of it, $50,000. $50,000 of gain remains taxable.
- Stack the income. The $75,000 of baseline ordinary income fills the lower brackets first, so the remaining $50,000 of gain stacks on top of it.
- Apply the marginal brackets. The $75,000 of other income is already past the $26,400 start of the 3.90% top bracket, so the whole $50,000 of taxable gain is taxed at 3.90%: $1,950.00.
- Effective rate. Dividing $1,950.00 by the full $100,000 realized gain gives an effective rate of 1.95%, exactly half the 3.90% top marginal bracket.
- Net proceeds. After paying $1,950.00 in state tax, the investor keeps $98,050.00 of the $100,000 gain, before any federal tax applies.
The second tier bites on very large sales. On a $12,000,000 single-year gain, the $2,000,000 above the threshold is exempt in full and half of the first $10,000,000 is exempt as well, so $7,000,000 is exempt and $5,000,000 is taxed at 3.90%, for $195,000.00, an effective rate of 1.63%.
The $10,000,000 Line: Where Arkansas Stops Charging Anything
This is the one hard edge on the page, and it is unusual: past it, the Arkansas bill stops growing entirely. Every figure below is a separate run of the calculator with other income held at the default $75,000.
At a $9,999,999 gain, one dollar short of the line. Arkansas tax = $194,999.98, an effective rate of 1.95%. The exempt portion is $4,999,999.50 and the same amount remains taxable.
At a $10,000,000 gain. Arkansas tax = $195,000.00. Exempt gain $5,000,000.00, taxable gain $5,000,000.00, effective rate still 1.95%.
At a $10,001,000 gain, a thousand dollars past the line. Arkansas tax = $195,000.00 again. The exempt figure rises to $5,001,000.00 while the taxable figure stays pinned at $5,000,000.00. That extra $1,000 of gain cost $0.00 in Arkansas tax.
At a $12,000,000 gain. Arkansas tax = $195,000.00 for the third time, with $7,000,000.00 exempt and $5,000,000.00 taxed. The effective rate has fallen from 1.95% to 1.63% without the bill moving a cent.
$195,000.00 is therefore the maximum Arkansas capital gains tax this calculator can return on a single-year long-term gain, no matter how large the sale. The extra $2,000,000 of gain between the $10,000,000 and $12,000,000 runs is worth $2,000,000 of after-tax proceeds, in full.
Marginal Cost, and the Reverse Question in Both Directions
Below the cap, each additional $1,000 of gain costs $19.50. A $99,000 gain returns $1,930.50 and a $100,000 gain returns $1,950.00. That is 3.90% charged on the half of the increment that survives the exemption, and it holds at scale: $500,000 of gain returns $9,750.00 and $1,000,000 returns $19,500.00, exactly double.
Above the cap, each additional $1,000 of gain costs $0.00. The reverse question therefore has a precise answer in Arkansas: $10,000,000 is the last dollar of gain that carries any state cost, and a filer who can push a disposition past that line in a single tax year converts a 1.95% marginal exposure into a 0.00% one.
The reverse question also runs on the other-income axis, and there the answer is $26,400. Holding the gain at $100,000 and moving other taxable income upward, the same gain costs $1,530.00 at $0 of other income (1.53% effective), $1,647.00 at $3,000, $1,748.40 at $5,600, $1,854.80 at $11,200, $1,898.00 at $16,000, and $1,950.00 at $26,400. From $26,400 upward it does not move again: the figure at $75,000 of other income is the same $1,950.00. The whole spread between a filer with no other income and a filer with $75,000 of it is $420.00, and every dollar of that spread is earned below $26,400.
At small gains with no other income the exemption and the low brackets wipe the bill out completely. With other income at $0, a $3,000 gain returns $0.00 and a $3,001 gain also returns $0.00. A $50,000 gain in the same circumstances returns $562.00, an effective rate of 1.12% against a 3.40% reported marginal bracket.
Filing Status Changes Nothing Here
Switching the filing status selector from Single to Married Filing Jointly leaves the result identical at every point tested. On the default inputs both return $1,950.00; with other income at $0 both return $1,530.00. Even at the small gains where a doubled bracket array would normally matter, the joint runs return $0.00 at a $999 gain, $0.00 at $1,000, $0.00 at $5,999, $0.00 at $6,000 and $0.00 at $6,001. Arkansas runs one regular income tax table for every filing status, and the engine reflects that: the input exists, and it does not change the arithmetic.
What This Does Not Account For
This calculator is precise about state tax, but several federal and transactional factors sit outside its scope: - Federal Capital Gains Taxes: Federal long-term brackets (0%, 15%, 20%) and short-term ordinary rates up to 37% under IRC § 1. - Net Investment Income Tax (NIIT): The 3.8% surtax on net investment income under IRC § 1411 for single filers over $200,000 (married joint over $250,000). - Alternative Minimum Tax (AMT): Federal AMT calculations under IRC § 55 impacting incentive stock option (ISO) exercise spread. - Section 1031 Like-Kind Exchanges: Tax deferral mechanisms for real property held for productive use in trade, business, or investment. - Qualified Small Business Stock (QSBS): Federal Section 1202 gain exclusions where state conformity varies significantly. - The DFA $100 income bands: Arkansas DFA computes tax from the midpoint of each $100 band of net taxable income. This engine walks the brackets on the exact income figure instead, so a result here can differ from the published table by roughly $2. - DFA's bracket-adjustment phase-out above $94,700: DFA reduces its bracket adjustment in $10 steps as income rises past about $94,700, and its own published rule for income of $100,001 and over is $3,809 plus 3.9% of the excess over $100,000. A straight bracket stack on $100,000 gives $3,480. The engine performs the straight stack, so on stacked incomes above roughly $94,700 it understates Arkansas tax by up to about $330. Neither the midpoint rule nor the phase-out is implemented anywhere in this calculator. - Loss netting: there is no capital loss input. Losses and carryforwards must be netted before you type the gain, and the engine cannot apply the $3,000 excess-loss allowance. - Arkansas standard deduction and personal tax credits: neither is subtracted from the other-income figure. Typing gross salary into that box overstates how full the lower brackets are, which matters below $26,400 of other income and is worth up to $420.00 on a $100,000 gain.
Common Pitfalls
- Overpaying by Skipping the 50% Exemption: Arkansas is not a state that taxes capital gain at full ordinary rates. Failing to claim the Ark. Code Ann. § 26-51-815(b)(2) exemption doubles the bill, and on a sale above $10,000,000 the § 26-51-815(b)(3) tier is worth far more.
- Failing to Track Holding Periods: The Arkansas exemption applies only to net long-term gain. Assets held one year or less get no exemption at the state level and carry higher federal rates on top of that.
- Underestimating Multi-State Apportionment: Selling real estate or business assets located in other jurisdictions triggers multi-state non-resident return filing obligations.
- Neglecting Underpayment Penalties: Substantial one-time liquidity events require prompt estimated tax payments within the quarter of sale to avoid statutory penalties.
- Mismatched Cost Basis Records: Failure to document reinvested dividends, stock splits, or structural return-of-capital distributions leads to inflated taxable gain calculations.
Frequently Asked Questions
Does Arkansas have a state capital gains tax?
How are short-term and long-term capital gains taxed in Arkansas?
Are retirement account distributions subject to capital gains tax in Arkansas?
Can capital losses offset capital gains in Arkansas?
When are estimated state tax payments required on capital gains?
Does filing status change the Arkansas tax on a capital gain?
Sources
- Arkansas Department of Finance and Administration: 2026 Statutory Individual Income Tax Rate Schedules. dfa.arkansas.gov
- Internal Revenue Service (IRS): Publication 544 (Sales and Other Dispositions of Assets) and Publication 550 (Investment Income and Expenses). irs.gov/publications/p544
Also consulted: Ark. Code Ann. § 26-51-815(b)(2), (b)(3): 50% exemption for net capital gain, and 100% exemption for net capital gain above $10,000,000 in a single tax year.