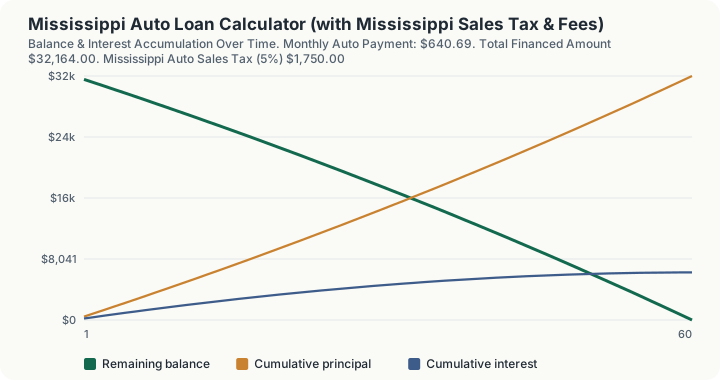
Quick Answer: A $35,000 vehicle in Mississippi with $5,000 cash down, a $391 dealer documentation fee, a 60-month term, and a 7.25% APR carries a $640.69 monthly payment. That figure includes $1,750.00 of Mississippi sales tax at the reduced 5% automotive rate and $23.00 in title and first registration fees, financing $32,164.00 in total.
Overview
Mississippi taxes a car at 5% while taxing almost everything else at 7%. That is a real statutory discount, not a rounding artifact. Miss. Code Ann. § 27-65-17(1)(b) sets a reduced rate for motor vehicles, and § 27-65-201 applies the same 5% to private-party sales through the county tag office. On a $35,000 purchase the reduced rate saves $700 against what the same money would cost you at the general rate.
There is no local add-on to worry about either. Mississippi does not authorize general county or municipal sales taxes, and while a handful of cities levy tourism and special levies, motor vehicles are not generally subject to them. So 5% is the whole purchase rate, statewide, and there is no local rate control on this calculator because there is nothing to enter.
The catch arrives later. Mississippi charges an annual ad valorem tax on vehicles, collected at the county tag office every time you renew. On a newer car it commonly runs several hundred dollars a year and dwarfs the flat renewal fees printed on your notice. Buyers who focus on the low purchase rate and budget nothing for the tag bill are the ones who get surprised, and this calculator does not model it because the amount depends on your county's millage.
Auto Loan APR by Credit Score
The APR columns below are national averages, not Mississippi figures. No primary source publishes average auto loan APR by state: Experian's report has no geographic cut, the CFPB publishes state origination volume but no rates, and the New York Fed publishes state delinquency only. The payment column is the part that is specific to Mississippi, because it runs this calculator's own Mississippi tax and fee rules at each tier's rate.
| Credit Tier | VantageScore 4.0 | Avg New APR | Avg Used APR | Est. Payment in Mississippi |
|---|---|---|---|---|
| Super prime | 781-850 | 4.55% | 6.30% | $600.37 |
| Prime | 661-780 | 6.23% | 8.77% | $625.27 |
| Nonprime | 601-660 | 9.67% | 14.03% | $678.18 |
| Subprime | 501-600 | 13.44% | 19.42% | $739.09 |
| Deep subprime | 300-500 | 16.01% | 21.77% | $782.34 |
Payment assumptions: $35,000 vehicle price, $0 trade-in, $5,000 cash down, $391 dealer documentation fee, 60-month term, new-vehicle APR applied to the Mississippi delivered price including tax and statutory fees. At the 6.39% overall new-car average the same purchase costs $627.67 a month.
The score bands are VantageScore 4.0, not FICO. The same borrower can land in a different tier under each model, so a FICO score pulled from a card issuer will not always match the band here. Source: Experian, State of the Automotive Finance Market, Q1 2026, slide 45.
What Moves Your Payment
Each row changes one input and leaves the rest at the baseline below. The dollar effects are this calculator's own output for Mississippi, not a rule of thumb.
| Factor | What Changes | Effect on Monthly Payment | Effect on Total Interest |
|---|---|---|---|
| Vehicle Price | Each extra $1,000 of price raises both the amount financed and the sales tax base, so the tax rises with it. | +$20.91 | +$204.92 |
| Trade-In Allowance | A $1,000 allowance cuts the amount financed by $1,000 and reduces the sales tax base by the same amount, so it saves tax as well as principal. | -$20.92 | -$204.92 |
| Cash Down Payment | A $1,000 larger down payment cuts the amount financed by $1,000. It never reduces the sales tax, which is assessed on the price, not on what you borrow. | -$19.92 | -$195.16 |
| Dealer Doc Fee | A $100 higher documentation fee adds $100 to the amount financed. It sits outside the sales tax base in Mississippi, so it does not raise the tax. | +$1.99 | +$19.52 |
| Longer Term | Stretching the same balance from 60 months to 72 months spreads the principal over twelve more payments at the same rate. | -$88.46 | +$1,319.64 |
Baseline: $35,000 vehicle price, $0 trade-in, $5,000 cash down, $391 documentation fee, 60 months at 7.25% APR, giving a $640.69 payment and $6,277.20 of total interest.
How This Is Calculated
Mississippi taxes a car at a reduced 5% rate rather than its 7% general sales tax rate. Four steps.
1. Net taxable base. Where a motor vehicle is taken in trade as credit or part payment on the sale of a motor vehicle, tax is due only on the net difference. There is no cap on the allowance.
The documentation fee is held outside this base. See the note below on why.
2. Sales tax. One reduced automotive rate, statewide.
3. Title and first registration. A fixed $23.00, being the $9 certificate of title and the $14 first registration. Renewals are $12.75.
4. Amount financed and amortization. The trade-in works twice: it lowered the base in step one and it reduces what you borrow here.
That balance amortizes as a fixed-rate installment loan:
where $P$ is the financed amount, $i$ is the monthly rate (APR divided by 12), and $n$ is the term in months. Each period's interest is the outstanding balance times $i$, the remainder reduces principal, and the schedule reconciles to zero at maturity.
A note on the doc fee. Whether Mississippi applies the 5% automotive rate to a dealer documentation fee is not stated in the published Department of Revenue guidance that could be verified for this calculator. Rather than guess a rule and bury the guess in the output, the fee is added to your delivered price but kept out of the taxable base. If your dealer does tax it, add 5% of the fee to the tax figure shown: on a $391 fee that is $19.55. Ask before you sign, because the answer belongs on the buyer's order either way.
Worked Example
Mississippi charges 5% on cars against a 7% general rate, one of the wider automotive discounts in the country, and it keeps the dealer doc fee outside the base. Both show up in the first two steps.
- Vehicle price: $35,000
- Trade-in allowance: $0
- Cash down: $5,000
- Dealer doc fee: $391
- Term: 60 months at 7.25% APR
Step 1 -- The taxable base. Net difference after any trade-in, with the doc fee left out: $35,000 - $0 = $35,000.00
Step 2 -- Automotive sales tax at the reduced 5% rate. $35,000.00 x 5% = $1,750.00
Step 3 -- Title and first registration, outside the base. $9.00 title + $14.00 registration = $23.00
Step 4 -- Total delivered price. $35,000 + $391.00 doc fee + $1,750.00 + $23.00 = $37,164.00
Step 5 -- Amount financed. $37,164.00 - $0 trade-in - $5,000 cash down = $32,164.00
Step 6 -- The monthly payment. $32,164.00 at 7.25% over 60 months = $640.69
Step 7 -- Month 1. $32,164.00 x (7.25% / 12) = $194.32 interest, $446.37 principal, balance $31,717.63
Step 8 -- Month 2. $31,717.63 x (7.25% / 12) = $191.63 interest, $449.06 principal, balance $31,268.57. Cumulative interest: $385.95
Step 9 -- The accumulation. By month 12, $2,150.27 of interest paid and $26,625.99 outstanding. Across the term, $6,277.20
Add a $10,000 trade-in and the base falls to $25,000, tax to $1,250.00, and the payment to $431.53. The trade-in saved $500 in tax on top of the $10,000 it took off the loan. Double the trade to $20,000 and the tax saving doubles to $1,000, because Mississippi puts no ceiling on the credit.
The 5% rate cuts both ways here. It makes the purchase cheaper, and it also makes the trade-in credit less valuable than it would be in a higher-rate state. A $10,000 trade-in that saves $500 in Mississippi would save $687.50 in Minnesota. If you are weighing a dealer trade against a private sale, the private sale only needs to beat the dealer's offer by 5% of that offer to come out ahead, which is a lower bar than in most states.
What This Does Not Account For
- Annual motor vehicle ad valorem tax. This is the big one. Assessed value is 30% of the vehicle's original MSRP, depreciated over ten years, multiplied by your county and municipal millage rate, less the 1994 Legislative Tag Credit. It is collected every year at tag renewal and on a newer vehicle it commonly runs into the hundreds of dollars. Millage varies by county, so no figure can be quoted here.
- The Legislative Tag Credit. It reduces the ad valorem bill by 5% of assessed value but is subject to statutory limits that vary, so it should not be treated as an unlimited discount.
- The $15 annual Road and Bridge Privilege Tax and the $12.75 annual registration renewal, both recurring rather than part of the purchase.
- Whether the doc fee is taxed, as described above.
- County-level tag office fees, which some counties add on top of the state schedule.
- Negative equity, GAP insurance, extended warranties, and aftermarket add-ons, unless you fold them into the vehicle price yourself.
Common Pitfalls
- Applying the 7% general rate to a car. This is the most common Mississippi error and it costs you $700 of imagined tax on a $35,000 purchase. The automotive rate is 5% under § 27-65-17(1)(b), and it applies to a dealer sale and a private sale alike.
- Budgeting nothing for the tag bill. The purchase tax is low, the annual ad valorem tax is not. Ask your county tax collector for an estimate on the specific vehicle before you commit, especially on a new car where the depreciation schedule has not started working in your favor.
- Believing there is a $425 doc fee cap. That claim circulates online and could not be corroborated in the Mississippi code. There is no statutory cap identified, which means the fee is negotiable and the $391 market average is a starting point rather than a ceiling.
- Assuming a private purchase avoids the tax. It does not. Miss. Code Ann. § 27-65-201 imposes the same 5% use tax on a casual sale, collected when you title the vehicle.
- Rolling negative equity forward. If you owe more than the trade is worth, the shortfall is added to the new loan. It raises the principal and the total interest, and it does not increase your tax credit, which is based on the allowance rather than your equity.
- Judging a loan by the monthly payment. Stretching this $32,164.00 balance from 60 to 72 months drops the payment to $552.23 and raises total finance charges from $6,277.20 to $7,596.87.
Frequently Asked Questions
What is Mississippi's sales tax rate on cars?
Why is the car rate lower than the general rate in Mississippi?
Does a trade-in reduce sales tax in Mississippi?
Is there a cap on dealer documentation fees in Mississippi?
How much are Mississippi title and tag fees?
How is the annual ad valorem tax calculated in Mississippi?
Sources
- Mississippi Department of Revenue, motor vehicle ad valorem tax guidance (30% assessment ratio, ten-year depreciation schedule, 1994 Legislative Tag Credit) dor.ms.gov
- Consumer Financial Protection Bureau, Truth in Lending Act (Regulation Z, 12 CFR § 1026.22) disclosure requirements for installment credit. ecfr.gov/current/title-12/chapter-X/part-1026
Also consulted: Miss. Code Ann. § 27-65-17(1)(b) (reduced 5% rate on motor vehicles, against the 7% general rate); Miss. Code Ann. § 27-65-201 (5% use tax on casual and private-party motor vehicle sales); Miss. Code Ann. § 27-65-3(i) and § 27-65-201 (tax computed on the net difference where a motor vehicle is taken in trade); Mississippi Department of Revenue, motor vehicle title and registration fee schedule; Experian, State of the Automotive Finance Market, Q1 2026, slide 45 (average new and used auto loan APR by VantageScore 4.0 credit tier; national, no state level cut published).
Mississippi Department of Revenue pages refuse automated retrieval. The 5% rate, the $9 title fee and the ad valorem formula are corroborated across the DOR ad valorem guidance and published statute text but were not read from a directly retrieved DOR document. The specific subsection for the dealer-sale rate is inferred; § 27-65-201 for casual sales was verified. Documentation fee taxability remains unverified and is treated as described above.