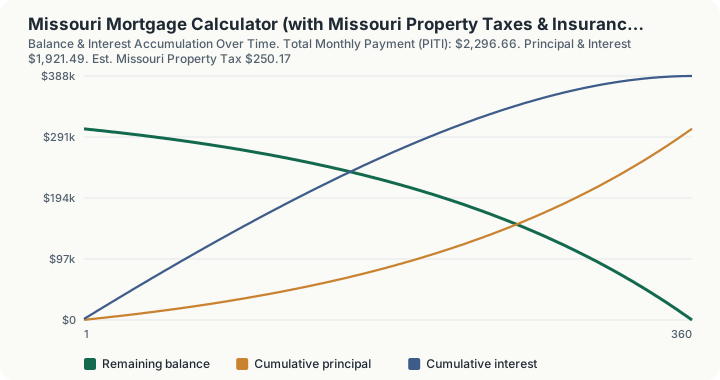
Quick Answer: A $380,000 Missouri home with 20% down and a 6.5% fixed rate carries a total monthly payment (principal, interest, property tax, and insurance) of roughly $2,297.
Overview
Missouri property taxes are assessed by county assessors and vary widely across the state, but the statewide effective rate averages close to 0.79% of assessed home value, which is below the national average. This calculator uses that statewide effective rate as its default so buyers evaluating a Missouri purchase get a realistic full-payment picture rather than just principal and interest.
A mortgage quote that only shows principal and interest can understate your real monthly obligation by several hundred dollars. Missouri buyers commonly escrow property taxes and homeowners insurance with their lender, so the actual amount due each month is the full PITI figure: Principal, Interest, Taxes, and Insurance. This calculator builds that complete number using your home price, down payment percentage, and interest rate, then layers in a Missouri-specific property tax estimate and a standard insurance placeholder.
How This Is Calculated
The calculation runs in four stages.
- Loan principal. Home price minus the cash down payment (home price times your down payment percentage) determines how much you actually borrow.
- Principal and interest. The loan principal is amortized over a standard 360-month (30-year) term at your entered annual interest rate using the standard fixed-rate mortgage formula.
- Property tax estimate. Missouri's statewide effective property tax rate of 0.79% is applied to the home's purchase price and divided by 12 to produce a monthly escrow contribution.
- Insurance estimate. A flat $125 monthly placeholder represents a typical homeowners insurance premium; your actual policy cost will depend on your insurer, coverage level, and home characteristics.
The core amortization formula for monthly principal and interest $M$ on principal $P$ at monthly rate $r$ over $n$ periods is:
Worked Example
Using the calculator's baseline inputs:
- Home price: $380,000
- Down payment: 20% ($76,000)
- Interest rate: 6.5% APR
- Term: 30 years (360 months)
The loan principal after the down payment is $380,000 - $76,000 = $304,000. Amortized over 360 months at 6.5%, the principal and interest payment comes to approximately $1,921.49 per month, verified against the calculator's test vectors. Missouri's 0.79% effective property tax rate applied to the $380,000 purchase price gives $380,000 × 0.79% ÷ 12 = $250.17 per month in escrowed property tax. Adding the $125 insurance placeholder, the full PITI payment is $1,921.49 + $250.17 + $125.00 = approximately $2,296.66 per month.
Which of the Three Inputs Actually Moves the Payment
The calculator takes a price, a down payment percentage and a rate. Sweeping each one separately shows that they are not close to equally important.
The marginal cost of the next rate step. One eighth of a percentage point costs $25.06 a month. At 6.5% the engine returns principal and interest of $1,921.49 and a total PITI of $2,296.66; at 6.625% those become $1,946.55 and $2,321.72, and at 6.375%, $1,896.56 and $2,271.73. The lifetime figure is where rate dominates everything else: total interest is $387,732.82 at 6.5%, $396,756.31 at 6.625%, $317,388.26 at 5.5% and $461,220.45 at 7.5%. The two-point spread of $143,832.19 is more than a third of the original $380,000 purchase price.
The marginal cost of the next unit of down payment. Moving from 20% down to 10% raises the loan principal from $304,000.00 to $342,000.00, the PITI from $2,296.66 to $2,536.84, and total interest from $387,732.82 to $436,202.14, an extra $48,466.91 of finance cost for $38,000 less equity. Moving to 25% down cuts the loan to $285,000.00 and the PITI to $2,176.56. With nothing down the engine returns $2,777.03 of PITI and $484,667.97 of interest.
The reverse question. Buyers working from a monthly ceiling can read the price straight off the sweep: a PITI at or below $2,068.06 corresponds to a $340,000 purchase at 20% down and 6.5%, and $1,839.46 corresponds to $300,000. Each $40,000 of price costs about $229 a month at these terms, of which roughly $202 is principal and interest and $26 is Missouri property tax.
Where the escrow line comes from, and what it ignores. The config multiplies the purchase price by a hard-coded 0.79% and divides by twelve, giving $250.17 a month at $380,000 and $263.33 at $400,000. Missouri actually assesses residential property at 19% of market value and applies locally set levies to that assessed figure, so this is a statewide-average shortcut rather than a county computation, and no reassessment ever occurs in the schedule: the same $250.17 appears in month 1 and in month 360.
Two constants that will not survive contact with a real quote. Hazard insurance is fixed at $125.00 a month regardless of price, rate or location, so the same insurance line appears on a $300,000 house and a $2,000,000 one. And no mortgage insurance is computed at any down payment: the $2,536.84 figure for a 10%-down purchase contains no PMI, which on a $342,000 conventional loan would add materially to the monthly cost and would make the 20%-versus-10% gap of $240.18 a substantial understatement.
What This Does Not Account For
- County-specific assessment ratios. Missouri assesses residential property at 19% of market value for tax calculation purposes, and mill levies differ significantly by county, school district, and municipality, so your actual tax bill may diverge from the statewide average this calculator uses.
- Private mortgage insurance (PMI). Down payments below 20% typically trigger PMI, an additional monthly cost not included in this model.
- HOA dues. Many Missouri subdivisions and condominium developments carry homeowners association fees that add to the true monthly housing cost.
- Closing costs and prepaid escrow reserves. Upfront cash needed at closing, including prepaid tax and insurance reserves, is not modeled here.
- Rate locks and point buydowns. The interest rate you actually close at may differ from a quoted rate depending on discount points purchased or market movement before closing.
Common Pitfalls
- Budgeting only for principal and interest. Missouri buyers who plan around the P&I figure alone are often surprised when their actual escrowed payment is 15% to 20% higher.
- Assuming the statewide average applies to your county. St. Louis City, St. Louis County, and Jackson County often carry higher effective tax burdens than rural Missouri counties.
- Skipping the PMI conversation. Buyers putting down less than 20% should ask their lender for the PMI-inclusive payment, since this calculator's default assumes 20% down.
- Comparing 15-year and 30-year quotes without adjusting the term. This calculator models a standard 30-year amortization; a 15-year loan produces a materially higher monthly payment but far less total interest.
- Ignoring insurance cost variability. Missouri's exposure to severe storms and tornadoes can push homeowners insurance premiums above the flat $125 placeholder used here, particularly in higher-risk counties.
Frequently Asked Questions
What is the average property tax rate in Missouri?
How is Missouri property assessed for tax purposes?
Does this calculator include PMI for less than 20% down?
Why is the insurance estimate a flat $125 per month?
Can I use this calculator to compare a 15-year loan against a 30-year loan?
Sources
- Consumer Financial Protection Bureau: Regulation Z (Truth in Lending Act) and mortgage disclosure standards. ecfr.gov/current/title-12/chapter-X/part-1026
- Federal Reserve Bulletin: Historical mortgage interest rate benchmarks. federalreserve.gov
Also consulted: Missouri State Tax Commission: Real property assessment ratios and county mill levy data.