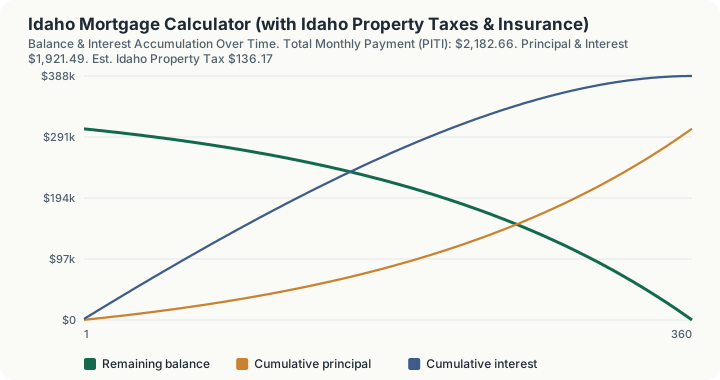
Quick Answer: On a $380,000 Idaho home with 20% down at 6.5% APR over 30 years, principal and interest run about $1,921.49 a month, and Idaho's roughly 0.43% effective property tax rate plus a $125 insurance estimate bring the full PITI payment to about $2,182.66.
Overview
Idaho's effective property tax rate, 0.43% in this calculator, sits below the national average, which hovers closer to 1%. That relatively favorable tax environment has become one of several factors drawing new residents to Idaho over the past several years, alongside lower overall living costs than the West Coast states many of those new residents are leaving. The result has been rapid home price appreciation in fast-growing markets like the Boise metro area and the wider Treasure Valley, even as the underlying property tax rate itself has stayed comparatively low.
Idaho funds local government primarily through property tax revenue collected at the county level, and the state has no general local sales tax to offset that reliance the way some other low-property-tax states do. Idaho's homeowner's exemption, available to owner-occupants, further reduces the taxable value on a primary residence, which is part of why the effective statewide average used here can run below the nominal levy rate a homeowner might see quoted by a county assessor.
This calculator produces a full PITI (Principal, Interest, Taxes, Insurance) estimate. A $380,000 baseline home price is used, roughly representative of a mid-range Boise-area purchase, though Idaho's home prices vary considerably between fast-growing metro areas and more rural parts of the state.
How This Is Calculated
- Compute the loan principal. Home price minus down payment: $380,000 × (1 − 20%) = $304,000.00 financed.
- Amortize principal and interest. The $304,000.00 balance runs through the platform's amortization primitive at a monthly rate of 6.5% ÷ 12 over 360 months, producing a monthly principal-and-interest payment of approximately $1,921.49.
- Estimate monthly property tax. Idaho's 0.43% effective annual rate is applied to the full home price and divided by twelve: $380,000 × 0.0043 ÷ 12 = $136.17 per month.
- Add a flat insurance estimate. A $125 monthly placeholder represents typical homeowners insurance; Idaho's wildfire-exposed foothill and rural properties can carry higher actual premiums.
- Sum to PITI. Combined, the estimated monthly housing payment comes to approximately $2,182.66.
The core payment formula is $PMT = P \times \dfrac{i}{1-(1+i)^{-n}}$, where $P = \$304{,}000.00$, $i = 6.5\%/12$, and $n = 360$, computed with Decimal.js arbitrary-precision arithmetic so the 360-row schedule reconciles exactly to the total interest figure.
Worked Example
Baseline scenario, matching this calculator's verified test vectors:
- Home price: $380,000.00
- Down payment: 20% ($76,000.00)
- Loan principal: $304,000.00
- Interest rate: 6.5% APR, 30-year fixed
- Monthly principal & interest: approximately $1,921.49
- Estimated Idaho property tax (0.43% effective rate): $136.17/month
- Estimated insurance: $125.00/month
- Total monthly PITI: approximately $2,182.66
- Total interest paid over 30 years: approximately $387,733
Running the calculator's built-in "Higher Price (+25%)" scenario against the same 0.43% effective rate raises the home price to $475,000, which is not far from recent median prices in parts of the Boise metro area, and shows how quickly the property tax and insurance components scale alongside the loan payment as home values climb.
What Each Input Is Worth, in Dollars
The schedule walks 360 months at fixed inputs. Holding the months still and moving the inputs gives the figures below, each of them the same calculation run again.
An eighth of a point of rate. Moving from 6.5% to 6.625% takes monthly principal and interest from $1,921.49 to $1,946.55, and PITI from $2,182.66 to $2,207.72. That is $25.06 a month, and lifetime interest rises from $387,732.82 to $396,756.31, a difference of $9,021.08 on a $304,000 loan. A full point to 7.5% takes the payment to $2,125.61 and lifetime interest to $461,220.45.
Ten points of down payment. At 10% down the principal is $342,000 and PITI is $2,422.84. At 20% it is $2,182.66. The $38,000 of extra cash buys $240.18 a month and cuts lifetime interest from $436,202.14 to $387,732.82, a saving of $48,466.91.
Ten thousand dollars of price. Taking the home from $380,000 to $390,000 at the same 20% down moves PITI from $2,182.66 to $2,236.80. Of that $54.14, $50.56 is principal and interest on the larger loan and $3.58 is the Idaho property tax line, which rises from $136.17 to $139.75 because the engine applies the 0.43% state average effective rate directly to the purchase price.
The Idaho tax line is a state average, not your county's. The $136.17 a month is $380,000 multiplied by 0.0043 and divided by twelve. It contains no county levy, no school district rate and no homeowner's exemption, which in Idaho removes 50% of a primary residence's value up to a statutory cap and would materially reduce this line for an owner-occupant. Treat it as a benchmark for what an Idaho home of this value typically carries, not as a quote.
No mortgage insurance appears at any down payment. Set the down payment to 10% and the engine still returns a $0.00 PMI figure on every row of the 360-month schedule. A real Idaho lender would charge mortgage insurance on a 90% loan until it amortised to 78% of the original value, and there is no input on this page that can express it. The $125.00 insurance line is likewise a flat estimate rather than a rate applied to the property, and neither HOA dues nor closing costs are included.
What This Does Not Account For
- County-specific levy rates. Idaho's 44 counties, along with overlapping school and taxing districts, each set their own levy rates; 0.43% is a statewide effective average, not any single county's actual rate, and fast-growing Ada and Canyon counties can differ from more rural counties.
- Homeowner's exemption details. Idaho's owner-occupant homeowner's exemption reduces taxable value on a primary residence up to a statutory cap; this calculator does not separately model exemption eligibility or the current cap amount.
- Wildfire and rural insurance premiums. The flat $125 monthly estimate does not reflect the higher premiums common in Idaho's wildland-urban interface areas, which have seen increased wildfire risk in recent years.
- Private mortgage insurance (PMI). Down payments below 20% typically require PMI on a conventional loan, not included in this estimate.
- HOA dues. Newer Treasure Valley subdivisions frequently carry homeowners association fees not reflected in this calculator.
Common Pitfalls
- Assuming Idaho's low property tax rate holds steady as home values rise. A low percentage rate applied to a rapidly appreciating home price can still produce a fast-growing dollar tax bill; Boise-area buyers have seen this play out over the past several years.
- Overlooking the homeowner's exemption filing requirement. Failing to file for Idaho's owner-occupant exemption after closing can mean paying tax on the full assessed value rather than the reduced exempted value for the first tax year.
- Underestimating wildfire insurance exposure. Properties near Idaho's forested foothills and wildland-urban interface zones often carry insurance premiums above the flat $125 estimate used here, and some carriers have restricted or repriced coverage in higher-risk zones.
- Using a stale statewide median as the price input. Idaho home prices have risen quickly in Ada and Canyon counties specifically; a national or older statewide median may understate a realistic current Boise-area purchase.
- Forgetting PMI on low-down-payment scenarios. The built-in 5%-down scenario toggle does not add PMI automatically, so real payments at low down payments will run higher than the raw comparison suggests.
Frequently Asked Questions
What property tax rate does this calculator use for Idaho?
Why has Idaho seen so much home price growth if property taxes are low?
Does this calculator apply the homeowner's exemption?
Does this account for wildfire insurance risk?
How much does county matter within Idaho?
Sources
- Idaho State Tax Commission: Property tax statistics, homeowner's exemption guidance. tax.idaho.gov
- Federal Housing Finance Agency (FHFA): House Price Index, Idaho and Boise metro data. fhfa.gov
Also consulted: Idaho Department of Labor: Population and migration trend reports.