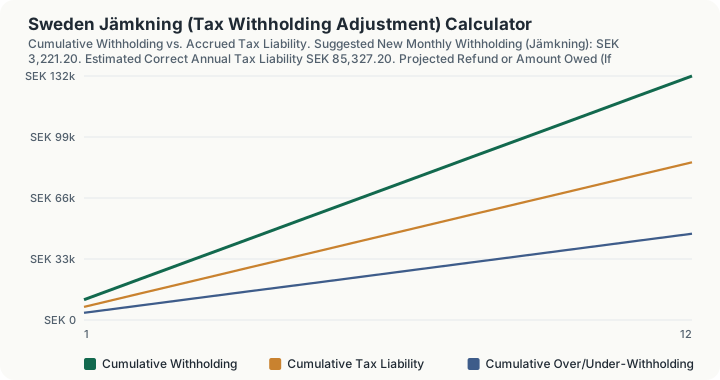
Quick Answer: On SEK 450,000 of annual income in Stockholm kommun, withholding SEK 11,000 per month projects a correct annual tax liability of SEK 85,327.20 but a total withholding of SEK 132,000.00 if unchanged, a SEK 46,672.80 over-withholding. With 6 months already paid, jämkning suggests dropping the remaining 6 months to SEK 3,221.20 per month, SEK 7,778.80 less per month, to land close to SEK 0 at filing.
Overview
Jämkning is the Swedish tax system's built-in mechanism for correcting your monthly preliminärskatt (preliminary tax withholding) mid-year instead of waiting for the year-end reconciliation. It exists because the standard payroll withholding tables (skattetabeller) that your employer applies assume a fairly typical, steady income pattern for someone living in your kommun; anyone whose real situation departs from that assumption, a bonus, a second job, a big deduction, a move between kommuner, moving in or out of statlig inkomstskatt territory, ends up either overpaying all year and waiting for a refund the following spring, or underpaying and facing a balance (plus, in bad cases, interest) at filing.
This calculator is aimed squarely at Swedish taxpayers, not any other country's payroll system. It estimates your full-year kommunalskatt (municipal tax) and statlig inkomstskatt (national income tax) liability from your expected annual income and kommun, compares that to what your current monthly withholding will add up to across the year, and tells you exactly how much to change your remaining monthly withholding to bring the year-end gap toward zero. That new monthly figure is precisely what you enter into Skatteverket's own jämkning application (ansökan om jämkning) or hand to your employer once approved.
Getting this right matters more than it might seem. A large refund is an interest-free loan to the Swedish state, money that could have been in your account and earning you something all year. A large balance due at filing can, in some circumstances, trigger a kvarskatteränta (late-payment interest charge) if it is large enough and paid late enough. Jämkning, done correctly, is how you avoid both outcomes.
How This Is Calculated
- Grundavdrag (basic deduction). Your fastställd förvärvsinkomst (established earned income, i.e. gross annual income for this purpose) is reduced by a grundavdrag that itself varies with income: it is small at very low incomes, rises through the middle of the income distribution, peaks around SEK 45,600 for incomes roughly between SEK 161,000 and SEK 185,000, then tapers back down to a floor of SEK 17,400 for high earners.
- Kommunalskatt (municipal tax). Your taxable income is taxed at your kommun's combined municipal-plus-region rate, a flat percentage that varies by kommun (see the companion Net Salary by Kommun Calculator for a comparison across 8 major kommuner).
- Jobbskatteavdrag (earned income tax credit). A tax reduction applied directly against the municipal tax bill (never against the state tax bill), sized to your income and, in this calculator's modeling, scaled to your local kommunal rate relative to the national average. This is one of the two figures in this calculator flagged as an approximation; see "What This Does Not Account For" below.
- Statlig inkomstskatt (national income tax). A flat 20% on the portion of taxable income above the 2026 skiktgräns of SEK 643,000. Most taxpayers never reach this threshold.
- The withholding gap. Multiplying your current monthly withholding by 12 gives the projected annual withholding if nothing changes; subtracting the correct annual tax liability from that gives your projected refund (positive) or amount owed (negative).
- The jämkning adjustment. Subtracting what has already been withheld this year from the correct annual liability gives the remaining liability for the rest of the year; dividing that by the number of months left gives the new monthly withholding that closes the gap to zero by year-end.
Worked Example
Using the calculator's default inputs:
- Annual Gross Income: SEK 450,000.00
- Kommun: Stockholm (30.55% combined kommunalskatt)
- Current Monthly Withholding: SEK 11,000.00
- Months Already Paid at This Rate: 6
Step by step:
- Grundavdrag at SEK 450,000 falls in the declining segment of the schedule: SEK 19,005.69. Taxable income = 450,000 − 19,005.69 = SEK 430,994.31.
- Municipal tax before credit: 430,994.31 × 30.55% = SEK 131,668.76.
- Jobbskatteavdrag at this income and Stockholm's rate: SEK 46,341.56. Municipal tax after credit: 131,668.76 − 46,341.56 = SEK 85,327.20.
- Taxable income (430,994.31) is below the SEK 643,000 skiktgräns, so statlig inkomstskatt is SEK 0. Correct annual tax liability: SEK 85,327.20.
- Projected annual withholding if unchanged: 11,000 × 12 = SEK 132,000.00. Gap: 132,000 − 85,327.20 = SEK 46,672.80 projected refund (over-withheld).
- Already withheld through month 6: 11,000 × 6 = SEK 66,000.00. Remaining liability: 85,327.20 − 66,000 = SEK 19,327.20 over the remaining 6 months.
- Suggested new monthly withholding: 19,327.20 ÷ 6 = SEK 3,221.20, a reduction of SEK 7,778.80 per month from the current SEK 11,000.
Carrying the Over-Withholding Month by Month
Step 8 -- After month one. Withheld SEK 11,000.00, liability accrued SEK 7,110.60, over-withheld SEK 3,889.40
Step 9 -- After month two. Withheld SEK 22,000.00, liability SEK 14,221.20, over-withheld SEK 7,778.80
Step 10 -- After month six, where this taxpayer stands today. Withheld SEK 66,000.00, liability SEK 42,663.60, over-withheld SEK 23,336.40
Step 11 -- After month twelve, if nothing is changed. Withheld SEK 132,000.00, liability SEK 85,327.20, over-withheld SEK 46,672.80
SEK 23,336.40 is already sitting with Skatteverket, and it will not come back until the refund lands the following summer. That figure is the case for filing jamkning rather than waiting: the over-withholding compounds at SEK 3,889.40 a month, none of it earns anything, and the only mechanism for stopping it mid-year is the adjustment application itself. Filing in month one rather than month six would have kept nearly SEK 20,000 in the account.
What This Does Not Account For
- Jobbskatteavdrag is modeled as an approximation, not the exact statutory formula. The precise Inkomstskattelagen formula for jobbskatteavdrag ties it to prisbasbelopp and your kommunal rate through a piecewise calculation that could not be located in a directly quotable primary-source sentence during this build. This calculator models it as a linear ramp reaching a verified maximum of approximately SEK 52,392/year (for those under 66) by roughly SEK 480,000 of income, scaled by your kommun's rate relative to the 32.38% national average. Your actual jobbskatteavdrag, and therefore your actual tax liability, may differ by a modest amount from what Skatteverket's own tables would show.
- Grundavdrag is a linear approximation of Skatteverket's official stepped table, not a cell-for-cell reproduction of the real table's SEK-100 roundings within each 500 kr income band. Differences are typically within roughly SEK 100-300 of the official figure.
- Only 8 kommuner are modeled directly. If your kommun is not one of the 8 offered, use the closest-rate kommun as a stand-in, or substitute your own kommun's combined rate manually when interpreting the results.
- Capital income, benefits-in-kind, and pension income are not modeled; this calculator assumes ordinary arbetsinkomst (employment income) only.
- This calculator does not submit anything to Skatteverket. The suggested monthly figure is what you would enter on an actual jämkning application (via Skatteverket's e-service or the paper form) or communicate to your employer's payroll department; this tool has no connection to Skatteverket's systems.
- Church fee (kyrkoavgift) and burial fee (begravningsavgift) are excluded from the kommunalskatt rate used here, since they are either membership-dependent or a separate statutory fee, not part of income tax proper.
Common Pitfalls
- Applying for jämkning based on last year's income instead of this year's projection. Jämkning corrects for what you expect to earn and owe THIS year; a raise, a new job, a house sale, or a change in kommun since last year all change the correct number.
- Forgetting that jämkning approval doesn't automatically update payroll. Once Skatteverket approves a jämkningsbeslut, you (or your employer, depending on how it was filed) still need to make sure payroll actually applies the new withholding amount.
- Treating a refund as free money rather than a sign to adjust. A consistently large refund year after year means you are over-withholding by roughly the same amount every year; jämkning fixes that going forward instead of only after the fact.
- Ignoring kvarskatteränta on large balances due. If your balance due at filing is large enough, Skatteverket charges interest from partway through the following year; jämkning during the year avoids this entirely.
- Not re-checking jämkning after a kommun move. Since kommunalskatt varies by kommun, moving to a higher- or lower-tax kommun mid-year changes your correct annual liability even if your income doesn't change at all.
Frequently Asked Questions
What is jämkning, exactly?
How do I actually apply for jämkning?
Why does my jobbskatteavdrag change if I move kommun?
Can jämkning make my withholding negative?
Does jämkning affect my final tax bill?
Sources
- Skatteverket: "När ska man betala statlig inkomstskatt och hur hög är den?" (2026 skiktgräns of SEK 643,000 and 20% rate, quoted directly). skatteverket.se
Also consulted: Skatteverket: "Kommunala skattesatser 2026" (skattesatser-kommuner-2026.xlsx), official published kommunalskatt data by kommun; Skatteverket: "Tabell för grundavdrag inkomstår 2026" (Bilaga 1), official grundavdrag table, read in full across all 4 pages; Skatteverket: "Jobbskatteavdrag" explainer page; ekonomifakta.se corroborating figures for the 2026 maximum credit and the abolition of the high-income phase-out from 1 January 2026 (jobbskatteavdrag modeled as an approximation; see "What This Does Not Account For").