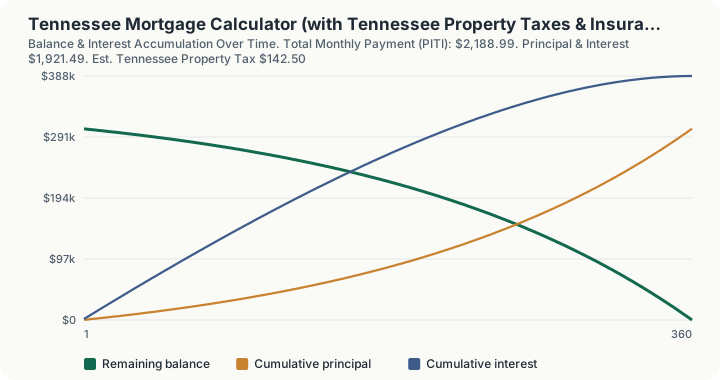
Quick Answer: A $380,000 Tennessee home with 20% down at 6.5% APR carries a total monthly payment (PITI) of approximately $2,188.99, made up of $1,921.49 in principal and interest, $142.50 in property tax, and $125 in insurance.
Overview
Tennessee combines two features that matter a great deal to homebuyers: no state income tax on wages, and a relatively low effective property tax rate. This calculator applies a 0.45% effective property tax rate, reflecting Tennessee's residential assessment ratio of 25% of appraised value applied against local county and municipal tax rates, which together tend to produce lower effective bills than many states with comparable home prices.
Because Tennessee fully repealed its Hall income tax on interest and dividends in 2021 and has never taxed wage income, homeowners here keep their full paycheck at the state level while also facing one of the lighter property tax burdens in the country. That combination is a notable contrast with South Carolina, which pairs a low property tax rate with an active state income tax, and South Dakota, which has no income tax but a meaningfully higher property tax rate.
The mortgage payment math, principal and interest amortized over a 30-year fixed term, uses the same engine applied across every mortgage calculator on this platform. State-specific property tax rates and surrounding context are the only variables that change.
How This Is Calculated
- Down payment and loan principal. Down payment percentage is applied to the home price; the remainder becomes the loan principal.
- Principal and interest (P&I). The loan principal is amortized over 360 months (30 years):
- Property tax. Home price is multiplied by Tennessee's 0.45% effective rate and divided by 12 for a monthly figure.
- Insurance. A flat $125 monthly homeowners insurance estimate is added.
- Total PITI. Principal, interest, tax, and insurance are summed into the headline monthly payment.
Worked Example
Using the calculator's default inputs:
- Home Price: $380,000.00
- Down Payment: 20% ($76,000.00)
- Interest Rate: 6.5%
- Term: 360 months (30 years)
Step by step:
- Loan principal: $380,000 − $76,000 = $304,000.00
- Monthly principal and interest at 6.5% over 360 months: $1,921.49
- Tennessee property tax: $380,000 × 0.45% = $1,710.00 per year, or $142.50 per month
- Homeowners insurance estimate: $125.00 per month
- Total monthly PITI: $1,921.49 + $142.50 + $125.00 = $2,188.99
- Total interest paid over the full 30-year term: $387,732.82
Where This Payment Actually Moves
The twelve-row table on this page shows the first year of a 360-row schedule the engine generates in full. Four numbers from that schedule and from sweeping the three inputs describe almost everything a buyer wants to know here.
The crossover, which is real and computed. Payment 1 splits $1,921.49 into $274.82 of principal and $1,646.67 of interest: six dollars of interest for every dollar of equity. The two halves do not cross until payment 232, where the split is $957.19 of principal against $964.30 of interest and interest is still ahead by $7.13. Payment 233 is the first month principal wins, at $962.37 of principal against $959.12 of interest. That is nineteen years and five months into a thirty-year loan. By that month the schedule has already booked $319,812.26 of cumulative interest and the remaining balance is $176,105.09, still more than half the original $304,000 principal.
The cost of the next eighth of a point. Sweeping interestRate in its own 0.125 step, principal and interest runs $1,871.78 at 6.25%, $1,896.56 at 6.375%, $1,921.49 at 6.5%, $1,946.55 at 6.625% and $1,971.74 at 6.75%. Moving from 6.5% to 6.625% costs $25.06 a month, and over the full term it costs $9,021.08 in total interest, $387,732.82 rising to $396,756.31. Half a point, 6.25% to 6.75%, is $99.96 a month and $35,984.97 in lifetime interest on the same $304,000.
The reverse question: what price hits a target payment? Sweeping homePrice at 20% down and 6.5%, total PITI runs $1,971.73 at $340,000, $2,080.36 at $360,000, $2,188.99 at $380,000 and $2,297.62 at $400,000. Each $10,000 of purchase price adds a constant amount to PITI because both moving parts, the 80% financed principal and the 0.45% property tax, scale linearly with price. To hit a target monthly figure, read it off that ladder rather than solving for it.
The 20% down payment line, and why nothing happens there. This is the boundary buyers expect to matter, and in this engine it does not. Sweeping downPaymentPercent across 19.5%, 20% and 20.5%, total PITI runs $2,201.00, $2,188.99, $2,176.98: a smooth $12.01 per half-point of down payment, with no discontinuity at twenty. At 5% down the figure is $2,549.27 on a $361,000 principal. The engine calls generateAmortizationSchedule without a monthlyPMIAmount, so the PMI column of the computed schedule is $0.00 at every down payment from 0% to 100%. Private mortgage insurance is genuinely not modelled, which means every sub-20% figure on this page understates the real payment by whatever a lender would charge.
Right method against wrong method, priced. The common error is applying the quoted rate to the purchase price instead of to the loan principal. Running this calculator at 0% down, so that the financed amount equals the full $380,000, returns $2,401.86 in monthly principal and interest against the correct $1,921.49. That is $480.37 a month overstated, and $484,667.97 of total interest against $387,732.82, an overstatement of $96,933.85 across the term, purely from pricing the rate against the wrong base.
Two limitations sit inside this section rather than beside it. The 0.45% property tax rate is a literal in this calculator's config, not a lookup against the platform's state property tax table. It happens to match the 0.45% the table currently carries for Tennessee, but a correction to that table would not reach this page. And the tax line is computed off the full purchase price, not off the loan balance or any reassessed value: the property tax figure stays at $142.50 a month at 5%, 19.5%, 20% and 20.5% down, and it never falls as the balance amortises.
What This Does Not Account For
- County and municipal rate variation. Tennessee's 95 counties, plus cities that levy their own municipal property tax on top of the county rate, produce a wide range of effective rates; 0.45% is a statewide approximation.
- The 25% residential assessment ratio mechanics. Only 25% of a home's appraised value is taxable in Tennessee, a different structure than states that tax closer to full market value; the 0.45% figure already reflects that ratio, but local mill rates still vary.
- Property tax relief for elderly, disabled, and veteran homeowners. Tennessee offers property tax relief programs for qualifying low-income elderly, disabled, and disabled veteran homeowners that can reduce the effective bill below this calculator's statewide estimate.
- PMI for down payments under 20%. This calculator does not add private mortgage insurance, typically required when the down payment is below 20%.
- HOA dues, flood insurance, or closing costs. None of these are modeled.
- Local sales tax impact on cost of living. Tennessee's 7% state sales tax plus local option tax (among the highest combined sales tax rates in the country) partially offsets the income tax and property tax savings modeled elsewhere on this platform, but is outside the scope of a mortgage payment calculator.
Common Pitfalls
- Assuming a single statewide property tax rate applies everywhere in Tennessee. Nashville, Memphis, and smaller municipalities layer city property tax on top of county rates, which can push the effective rate meaningfully above or below the 0.45% statewide estimate depending on location.
- Forgetting that Tennessee's overall tax picture includes a high sales tax. No income tax and low property tax are real advantages, but Tennessee's combined state and local sales tax rate is among the highest in the country, which affects overall cost of living beyond the mortgage payment.
- Ignoring reassessment cycles. Tennessee counties reassess property values periodically (commonly every four to six years), which can change your tax bill independent of your mortgage rate.
- Overlooking the down payment threshold for PMI. Below 20% down, expect an additional PMI line item not reflected in this calculator's output.
- Not applying for available property tax relief. Eligible elderly, disabled, and veteran homeowners in Tennessee can significantly reduce their tax bill but must actively apply through their county trustee's office.
Frequently Asked Questions
Does Tennessee have a state income tax?
Why is Tennessee's property tax rate lower than South Dakota's?
Are there property tax relief programs for Tennessee homeowners?
How much does Tennessee's property tax rate vary by county and city?
What happens if I put down less than 20%?
Does Tennessee's lack of income tax fully offset its higher sales tax?
Sources
- Tennessee Department of Revenue: Property tax relief program guidance. tn.gov/revenue.html
- Consumer Financial Protection Bureau: Regulation Z mortgage disclosure standards and PMI requirements. ecfr.gov/current/title-12/chapter-X/part-1026
Also consulted: Tennessee Comptroller of the Treasury: Division of Property Assessments, assessment ratios and county tax rate data.