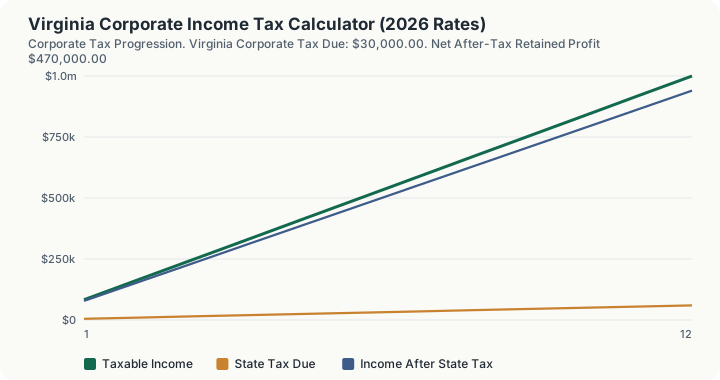
Quick Answer: On $500,000 of pre-apportioned taxable income, Virginia's flat 6.00% corporate income tax rate produces $30,000.00 in state tax due and $470,000.00 in net after-tax profit.
Overview
For a corporation comparing Mid-Atlantic locations, Virginia's flat 6.00% corporate income tax rate sits below both Maryland's 8.25% and Delaware's 8.70%, and it ties Michigan, a state with no border in common, as the only two states in this dataset levying exactly 6.00%.
Virginia applies the 6.00% rate uniformly to all apportioned C-corporation income, with no bracket thresholds. That places Virginia modestly above the national median for taxing states, a middling figure that neither stands out as unusually low like North Carolina's 2.00% nor unusually high like New Jersey's 9.00%.
Virginia's 6.00% rate turns the calculator's $500,000 example into $30,000.00 of state tax, identical to what Michigan would generate on the same income, and well below the $41,250.00 the same base would owe under Maryland's 8.25% rate just across the Potomac.
How This Is Calculated
Virginia has held its corporate rate at 6.00% since 1972, the longest unchanged corporate rate in the country, while nearly every neighbouring state has cut or restructured. Virginia is also a separate-entity state by default, with consolidated and combined returns available only by election and effectively locked in once made, so the filing method chosen at the start of a Virginia presence tends to govern for the life of it.
- Read the income field as the taxable base. The single income input is taken as Virginia taxable corporate income exactly as typed. The code applies no modification, allocation or deduction to it before the rate stage; it is the base.
- Apply the single statutory rate. Virginia's 6.00% rate is multiplied against that figure with no bracket lookup, because the schedule has one band running from the first dollar: $500,000 x 6.00% = $30,000.00.
- Subtract credits and floor the result at zero. The credits field is subtracted from the step-2 figure and the difference is clamped at $0.00, so no credit entry can drive the liability negative. With the field at its $0 default the $30,000.00 stands; enter $12,000 of credits and the page returns $18,000.00, a reduction of exactly the credit entered because the subtraction is a straight one.
- Derive the reported rates from those two numbers. The effective rate is the tax divided by the income entered, 6.00% here, and the top statutory bracket is reported separately as 6.00%. Net after-tax retained profit is the income less the tax, $470,000.00. Those four outputs are the whole of what the engine produces.
Worked Example
Using this calculator's baseline scenario: a corporation with $500,000 in taxable income apportioned to Virginia.
- Start with apportioned taxable income. The corporation has already apportioned $500,000 of its total taxable income to Virginia using the state's statutory apportionment formula, before any state-level tax is applied.
- Apply Virginia's flat statutory rate. Virginia taxes all C-corporation income at a single flat rate of 6.00%, regardless of income size, so no bracket lookup is required: $500,000 × 6.00% = $30,000.00.
- Virginia corporate tax due: $30,000.00.
- Net retained profit. Subtracting the state tax liability from taxable income leaves $500,000 − $30,000.00 = $470,000.00 in after-tax profit retained by the corporation, before any separate federal tax liability is applied.
Because Virginia uses a single flat rate rather than graduated brackets, the 6.00% effective rate is identical to the marginal rate at every income level: a corporation earning $50,000 and one earning $50 million both face the same 6.00% state rate on their apportioned income.
Flat Six Percent, Priced Per Thousand
There is no threshold anywhere in this calculation. Virginia taxes corporate income at a single 6.00% rate with no brackets, no minimum, no cap and no phase-out, so the sweep is a straight line. At $100,000 of apportioned income the tax is $6,000.00; at $500,000 it is $30,000.00; at $5,000,000 it is $300,000.00. The reported effective rate is 6.00% at all three, identical to the marginal rate.
The marginal cost of the next $1,000. Raising income from $500,000 to $501,000 moves the tax from $30,000.00 to $30,060.00. Each additional $1,000 of apportioned income costs $60.00, and it costs that at every income level the calculator accepts.
The one input that can move the effective rate. Credits are the only thing on this page that makes the effective rate differ from 6.00%. Enter $10,000 of credits against the $500,000 baseline and the tax falls from $30,000.00 to $20,000.00, with the reported effective rate dropping to 4.00% while the marginal rate stays at 6.00%. That gap between effective and marginal is entirely the credit; nothing in the rate schedule produces it.
The reverse question. How much credit extinguishes the bill? Exactly $30,000.00, the tax on $500,000 at 6.00%. Enter $50,000 of credits and the tax is $0.00 with an effective rate of 0.00%.
Right method against wrong method, priced. The engine takes the greater of zero and tax less credits. A $50,000 credit against a $30,000.00 liability therefore produces $0.00 and not a $20,000 refund: the excess is discarded in this code path, not carried forward and not refunded. Modelling a credit-rich year by subtracting the credit from income rather than from tax gets the wrong answer in the other direction, because $10,000 removed from the base is worth $600.00 at 6.00% rather than the full $10,000 the engine credits against tax.
What This Does Not Account For
- Federal Taxable Income Starting Point. Net corporate earnings are determined under IRC § 63 before Virginia modifications. This calculator starts one step later: the income box is read as the finished Virginia taxable figure and nothing is derived from a federal return.
- Virginia Additions & Subtractions. The Virginia tax deducted federally is added back, and the state applies its own fixed-date conformity adjustments and related-party addbacks. No addback and no subtraction is computed anywhere in this page's code path, so enter an income figure that already reflects them.
- Apportionment Factor Allocation. Virginia apportions on a three-factor formula with a double-weighted sales factor as the general rule, with single sales factor apportionment mandated or elective for specified industries. The engine performs no apportionment of any kind. The word does not appear in the primitive this page binds to; the figure you type is taken as the Virginia figure and multiplied by the rate as it stands.
- Net Operating Loss (NOL) Deductions. Allowable Virginia NOL carryforwards reduce the base before the rate is applied. No loss deduction is applied by this calculator. If a carryforward is available, subtract it yourself before entering the income.
- Filing Method Verification. The elected filing method, separate, consolidated, or combined, is confirmed, since Virginia binds a group to its election and changing it requires the Department's permission. No group, election or filing-method test is applied here. The code reads one income figure and one credit figure and nothing else.
- Credits in excess of tax are discarded. $50,000 of credits against the $30,000.00 baseline returns $0.00; the excess is neither refunded nor carried forward in this code path.
- No apportionment is performed. The income entered is assumed already apportioned to Virginia, and the single-sales-factor election Virginia offers certain industries changes that input rather than anything computed here.
- Federal corporate income tax (21% under IRC § 11).
- Specialized gross receipts taxes (e.g. Ohio CAT, Washington B&O, Texas Franchise Tax) where applicable.
- Minimum entity franchise tax fees or annual report filing charges.
- Base Erosion and Anti-Abuse Tax (BEAT) or Global Intangible Low-Taxed Income (GILTI) provisions.
- Local municipal corporate earnings taxes (e.g. NYC General Corporation Tax).
Common Pitfalls
- Mistaking the Flat Rate for the Final Bill: Assuming Virginia's 6.00% rate applies directly to book income rather than to apportioned taxable income after state additions, subtractions, and NOL adjustments.
- Improper Apportionment Sourcing: Applying market-based sourcing vs cost-of-performance rules incorrectly for service revenue apportioned to Virginia.
- Ignoring Unitary Group Combined Reporting: Failing to account for Virginia's mandatory combined return requirements across related entities.
- Neglecting State NOL Carryforward Caps: Overlooking Virginia's annual percentage limitations on net operating loss deductions, which matter more once the 6.00% rate is applied to a larger taxable base.
Frequently Asked Questions
Does Virginia have a corporate income tax?
When are Virginia corporate tax returns due?
Does Virginia tax S-corporations and LLCs?
How is multi-state corporate income apportioned to Virginia?
Sources
- Virginia Department of Taxation: Corporate Tax Statutes and Guidance (2026). tax.virginia.gov
- Multistate Tax Commission (MTC): Uniform Apportionment and Allocation Guidelines. mtc.gov