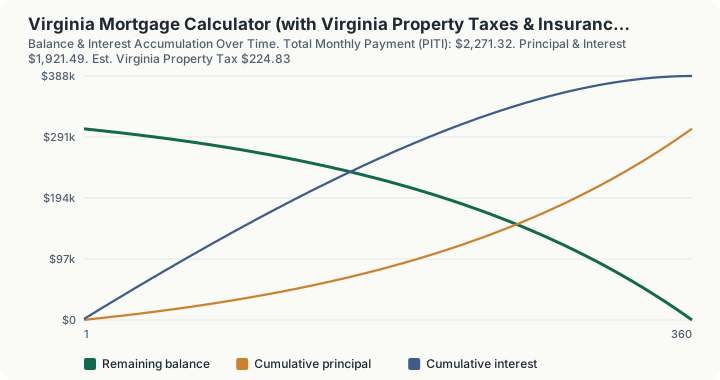
Quick Answer: On a $380,000 home with 20% down and a 6.5% fixed rate, the loan principal is $304,000, the principal and interest payment is about $1,921 a month, and Virginia's moderate 0.71% effective property tax rate brings the estimated total PITI payment to roughly $2,271.
Overview
Virginia's effective property tax rate sits close to the national median, generally in the 0.8% range statewide, though the figure masks substantial variation between jurisdictions. Rural and small-city localities often assess well below the state average, while high-demand Northern Virginia counties near Washington, D.C., such as Fairfax, Arlington, and Loudoun, can run higher due to larger assessed home values even at similar or lower millage rates. This calculator uses a 0.71% blended effective rate suitable for general estimation across the Commonwealth, giving buyers a reasonable middle-ground figure before they pull the specific rate for the county or independent city where they are purchasing.
Because Virginia is a Commonwealth of independent cities as well as counties, each with its own taxing authority, two homes of identical value ten miles apart can carry different tax bills depending on which jurisdiction they sit in. This calculator's 30-year amortization combined with a property tax and flat insurance estimate produces a PITI figure that closely mirrors how a Virginia-licensed lender structures a monthly payment and escrow account, giving buyers a solid starting point before requesting a formal Loan Estimate.
How This Is Calculated
- Down payment and loan principal. Home Price times the down payment percentage gives the cash down; the remainder becomes the loan principal. At $380,000 with 20% down, that is $76,000 down and $304,000 financed.
- Principal and interest. The loan principal amortizes over 360 monthly periods (30 years) using the standard mortgage payment formula, PMT = P x [r(1+r)^n] / [(1+r)^n - 1], where r is the monthly rate (annual APR / 12).
- Property tax. Home Price times 0.71% gives the estimated annual property tax, divided by 12 for the monthly escrow contribution.
- Insurance. A flat $125 monthly estimate represents typical homeowners insurance, added to complete the PITI total.
Worked Example
Using the platform's verified baseline: a $380,000 home, 20% down, and a 6.5% fixed rate.
- Home price: $380,000.00
- Down payment (20%): $76,000.00
- Loan principal: $304,000.00
- Monthly rate: 6.5% / 12 = 0.54167%
- Principal and interest (verified): $1,921.49
- Estimated monthly property tax (0.71% annual / 12): $224.83
- Estimated monthly insurance: $125.00
- Estimated total monthly PITI: approximately $2,271.32
- Total interest paid over 30 years: roughly $387,733
Buyers evaluating the built-in higher-price scenario, which models a 25% increase to $475,000, will see the property tax line scale proportionally along with the principal and interest payment, since both are calculated as a function of home price rather than as fixed dollar amounts.
What An Eighth Of A Point Costs Over 360 Months
The rate step, at one eighth of a point. Holding the $380,000 price and 20% down fixed, the engine returns a principal and interest payment of $1,896.56 at 6.375%, $1,921.49 at 6.500%, $1,946.55 at 6.625% and $2,022.52 at 7.000%. One eighth of a point therefore costs about $25 a month. Over the full 360 payments the same eighth is worth far more: total interest runs $378,763.14 at 6.375%, $387,732.82 at 6.500% and $396,756.31 at 6.625%, so the step from 6.375% to 6.500% costs $8,972.09 and the next one $9,021.08. Going from 6.5% to 7.0% costs $36,371.80 of interest, which is more than the down payment difference between 20% and 25%.
The down payment step, priced against the tax line. At 20% down the Virginia PITI is $2,271.32. At 5% down it is $2,631.60, at 0% down $2,751.69, and at 25% down $2,151.22. The whole of that movement is principal and interest: the property tax line stays at $224.83 in every one of those four scenarios, because the engine applies the 0.71% rate to the purchase price and the purchase price does not change when the down payment does. Total interest moves from $387,732.82 at 20% down to $460,432.24 at 5% and $484,667.97 at 0%, so the fifteen points of equity between 5% and 20% are worth $72,700.34 of interest over the term.
The price step, and the only line that responds to it. Raising the price from $380,000 to $400,000 moves the Virginia PITI from $2,271.32 to $2,384.29 and the tax line from $224.83 to $236.67. Dropping to $300,000 gives $1,819.46 with a tax line of $177.50. At $475,000, which is the calculator's higher-price scenario, PITI is $2,807.90 with $281.04 of monthly tax. Price is the only input that moves the escrow figure at all; rate and down payment leave it untouched.
The reverse question. A buyer with a fixed monthly budget can read those anchors backwards. In Virginia at 6.5% with 20% down, $1,819.46 a month supports a $300,000 purchase, $2,271.32 supports $380,000, $2,384.29 supports $400,000 and $2,807.90 supports $475,000. Each additional $20,000 of purchase price costs roughly $112.97 a month at these inputs, of which $11.84 is the tax line and the rest is principal and interest.
Right method against wrong method, priced. The 5%-down scenario is the trap on this page. Moving from 20% down to 5% raises the reported PITI from $2,271.32 to $2,631.60, a difference of $360.28 a month, and a buyer comparing the two figures will conclude that is the cost of the smaller down payment. It is not. No private mortgage insurance is added anywhere in this code path, at any loan-to-value ratio, so the 5%, 0% and 20% figures are all quoted PMI-free. A real 5%-down loan carries a PMI charge on top of $2,631.60, and the engine has no input that would produce it.
What This Does Not Account For
- No private mortgage insurance is computed at any loan-to-value ratio. The 0%-down scenario returns $2,751.69 and the 20%-down scenario $2,271.32, and neither carries a PMI line. The gap between them is principal and interest only.
- The property tax line is the 0.71% effective rate applied to the purchase price, once. It is not applied to an assessed value, it is never reassessed, and it is held constant for all 360 months. The figure is $224.83 a month in month one and $224.83 a month in month 360.
- The $125 monthly insurance figure is a flat placeholder, not a quote. It does not vary with price, location or coverage, so it is identical at the $300,000 and $475,000 scenarios.
- The term is fixed at 360 months and the rate at a single APR. No 15-year option, no adjustable rate and no extra-payment input exists on this page, so every total-interest figure above assumes the loan runs to term unchanged.
- Locality-specific millage variance. Virginia's counties and independent cities set their own property tax rates, and Northern Virginia jurisdictions in particular can differ meaningfully from the 0.71% statewide blended figure this calculator uses.
- Virginia's Grantor's Tax and Recordation Tax. Home sales in Virginia trigger a Grantor's Tax paid by the seller and a Recordation Tax on the deed of trust paid largely by the buyer at closing; both are one-time closing costs, not part of the ongoing monthly PITI this calculator models.
- Private mortgage insurance (PMI). Down payments below 20% typically require PMI, which is not included in this calculator's output.
- Northern Virginia congestion relief and regional fees. Certain Northern Virginia localities apply additional transportation-related fees at various points in a real estate transaction that are not modeled here.
- HOA and condo association dues. Common in many Northern Virginia and Hampton Roads communities, these are excluded from this calculation.
Common Pitfalls
- Applying the statewide average to a Northern Virginia purchase. Buyers in Fairfax, Arlington, or Loudoun counties should pull the actual local rate rather than relying solely on the 0.71% blended figure, since assessed values in those markets run meaningfully higher than the state average.
- Forgetting the Grantor's and Recordation taxes are closing costs, not monthly costs. These one-time Virginia-specific taxes can add thousands of dollars to a closing but do not appear in the recurring PITI payment this calculator estimates.
- Underestimating PMI on the 5% down payment scenario. That built-in scenario significantly increases the loan principal; an actual 5% down transaction would also typically carry a PMI premium not reflected in this tool's output.
- Assuming property tax stays flat when comparing home prices. The built-in higher-price scenario shows that both the loan payment and the property tax line scale together as home price increases, so a bigger budget increases the total monthly obligation on two fronts at once.
- Overlooking flood insurance in tidewater and coastal Virginia. The flat $125 monthly insurance estimate does not include separate flood insurance, which is often required in Hampton Roads and other low-lying coastal areas.
Frequently Asked Questions
Why does Virginia's property tax rate vary so much by location?
What is Virginia's Grantor's Tax and does this calculator include it?
Does this calculator include Virginia's Recordation Tax?
How accurate is the 0.71% property tax estimate for my specific county?
Should I add flood insurance to the estimate in coastal Virginia?
Sources
- Virginia Department of Taxation, local property tax rate resources. tax.virginia.gov
- Consumer Financial Protection Bureau (CFPB), Regulation Z and mortgage disclosure standards. ecfr.gov/current/title-12/chapter-X/part-1026
Also consulted: Virginia Department of Housing and Community Development, transfer and recordation tax guidance.