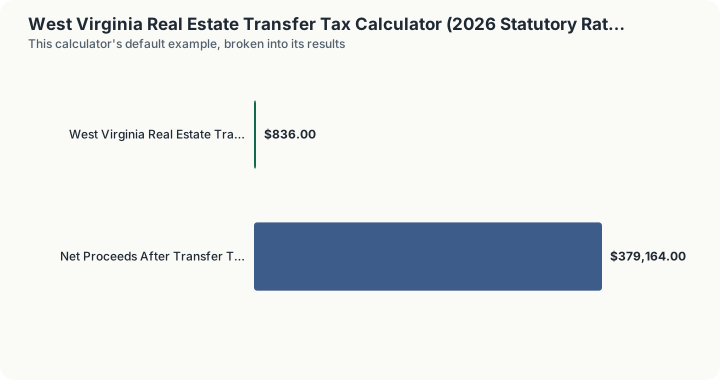
Quick Answer: A $380,000 home sale in West Virginia owes $836.00 in state excise tax on the transfer of real property, a flat 0.22% rate applied to the full sale price with no brackets or high-value surcharge.
Overview
West Virginia's excise tax on the transfer of real property runs $1.10 per $500 of value, 0.22% of the sale price, under W. Va. Code Section 11-22-2, a single flat statewide rate with no county or municipal add-on anywhere in the state. That places West Virginia at a bit more than double the 0.1% rate shared by Alabama, Georgia, Kentucky, and South Dakota, while still sitting well below neighboring Virginia's combined 0.35% to 0.43% range.
State law does not require a specific party to pay the tax; it is customarily handled as a negotiated item in the purchase agreement, and local custom can vary by county. Because the rate is flat, a $380,000 West Virginia sale owes exactly $836, scaling in precise proportion to price with no bracket threshold to track.
County clerks across all 55 West Virginia counties apply that same 0.22% calculation, so the tax due depends only on the sale price entered, not on which part of the state the property is located in.
How This Is Calculated
West Virginia's state excise tax on real property transfers is $1.10 per $500 of value, a flat 0.22%, and county authority to add to it varies enough that this baseline models the state rate only.
The engine reads the 0.0022 rate under W. Va. Code 11-22-2 and multiplies the full sale price by it, reporting tax due, effective rate, and net proceeds. There is no bracket schedule and no value threshold in the state rate, so the effective rate reads 0.220% at every price. Check your county's additional excise tax before treating this as the full closing figure.
Worked Example
The excise tax on transfer of real property, calculated on the baseline $380,000 sale.
Step 1 -- The consideration. Contract sale price = $380,000
Step 2 -- The statutory rate. W. Va. Code 11-22-2, $1.10 per $500 of value = 0.22%
Step 3 -- Apply the rate. $380,000 x 0.0022 = $836.00
Step 4 -- Cross-check by the per-$500 method. 760 x $1.10 = $836.00
Step 5 -- Net proceeds after the excise tax. $380,000.00 - $836.00 = $379,164.00
Step 6 -- The effective rate. $836.00 / $380,000 = 0.220%
The calculator's higher scenario at $1,500,000.
Step 7 -- The luxury sale. $1,500,000 x 0.0022 = $3,300.00
Step 8 -- The effective rate, unchanged. $3,300.00 / $1,500,000 = 0.220%
West Virginia's counties may add their own excise on top of the state rate, and many do, but the additional amounts are set locally and are not part of the statewide figure this calculator models, so treat Steps 3 and 7 as the state-level floor. What the two effective-rate steps establish is that no bracket or high-value tier exists at the state level: a $40,000 rural parcel and a $4,000,000 commercial building are both taxed at 0.22%, and the tax scales in an exact straight line between them. The grantor customarily pays, making Step 5 the seller's figure.
The Per-$500 Statute Against The Percentage Engine
The marginal cost of the next $10,000 of sale price. Moving the price from $380,000 to $390,000 moves the tax from $836.00 to $858.00. Every additional $10,000 of consideration costs $22.00, at every price, because the engine multiplies the full sale price by 0.0022 with no bracket, no exemption floor and no high-value surcharge anywhere in the code path.
The price ladder, end to end. $250,000 owes $550.00. $380,000 owes $836.00. $500,000 owes $1,100.00. $750,000 owes $1,650.00. $1,000,000 owes $2,200.00. $1,500,000 owes $3,300.00. $2,000,000 owes $4,400.00. The reported effective rate is 0.220% at every one of those prices and the mansion-tax output is $0.00 at all of them: West Virginia carries no mansionCliff entry, so the surcharge line exists on the page only because the calculator shares a configuration with the states that have one.
The reverse question. A seller working to a closing-cost budget can invert the line directly. $2,200.00 of tax corresponds to a $1,000,000 sale, $1,100.00 to $500,000, and $550.00 to $250,000. To keep the transfer charge under $1,100.00, the price has to stay under $500,000, and there is no threshold anywhere in that range where the answer would change shape.
Right method against wrong method, priced. The statute is not written as a percentage. It reads $1.10 per $500 of value, under W. Va. Code 11-22-2, and a register of deeds applying it literally counts whole increments and rounds up. This engine does not: it multiplies by 0.0022 and reports the exact product. On the $380,000 default the two methods agree exactly, because $380,000 is a whole number of increments: 760 whole $500 increments at $1.10 each is $836.00. On a price that is not, they diverge. A $380,100 sale returns $836.22 from this calculator, while 760.2 increments rounded up to 761 at $1.10 each gives $837.10. The gap is $0.88, small in dollars and reliably present on any sale price that is not a round multiple of the statutory increment.
Where the flat rate leaves the seller exposed. The 0.22% is the state rate only. West Virginia counties are authorised to impose an additional excise tax of their own, and none of them is in this table: the engine holds a single statewide entry with an avgLocalRate of zero. A county charging its own $1.10 per $500 would double the figure on this page, and the calculator would not know.
What This Does Not Account For
- County-level excise taxes are not modelled. The engine holds one statewide 0.22% entry with a local rate of zero, and a county imposing its own additional excise would not change the figure on this page.
- The engine multiplies rather than counting increments. A price that is not a whole multiple of $500 returns the exact product, not the rounded-up figure a recorder would charge: $380,100 returns $836.22 against a recorder's $837.10.
- Statutory exemptions are not tested. Whatever value is entered is taxed.
- There is no schedule on this page. The configuration returns an empty table, so the price sweep above was produced by re-running the calculator rather than read off a chart.
- County-authorized additional excise tax. Some West Virginia counties are authorized under state law to levy an additional local excise tax on real property transfers on top of the state rate, which this calculator's baseline does not include since it is not uniform statewide. Buyers and sellers should confirm with the county clerk whether a local add-on applies.
- Exemptions for certain transfer types. Transfers between spouses, transfers into certain trusts, and transfers incident to a will or intestate succession may be exempt from the excise tax under West Virginia law. This calculator assumes a standard arm's-length taxable sale.
- County clerk recording fees. West Virginia county clerks charge separate flat recording fees per document, unrelated to sale price, which this calculator does not include.
- Title insurance and attorney or closing agent fees. The excise tax is only one line item on a West Virginia closing statement; title search fees, closing costs, and survey fees are separate and not modeled here.
Common Pitfalls
- Assuming the state rate is the whole story. Because some West Virginia counties can add a local excise tax, using only the 0.22% state rate can understate the true cost in a county that has adopted the additional local tax; confirming with the county clerk avoids a surprise at closing.
- Forgetting who customarily pays. West Virginia law does not mandate which party pays the excise tax; it is customarily handled as a negotiated item in the purchase agreement, and practice can vary by county.
- Applying an out-of-state rate by habit. Buyers and agents relocating from bracket-heavy states sometimes overestimate West Virginia's tax by applying a marginal rate structure that does not exist in the state-level tax.
- Confusing the excise tax with mortgage or deed-of-trust recording costs. The excise tax modeled here applies to the transfer of the property itself, not to any separate loan document recorded alongside the deed.
Frequently Asked Questions
What is West Virginia's real estate transfer tax rate?
Who pays the real estate excise tax in West Virginia?
Does West Virginia have a mansion tax on expensive homes?
Do West Virginia counties add their own transfer tax on top of the state rate?
Are any property transfers exempt from West Virginia's excise tax?
Sources
- West Virginia State Tax Department: Excise Tax on Transfer of Real Property guidance under W. Va. Code 11-22-2. tax.wv.gov