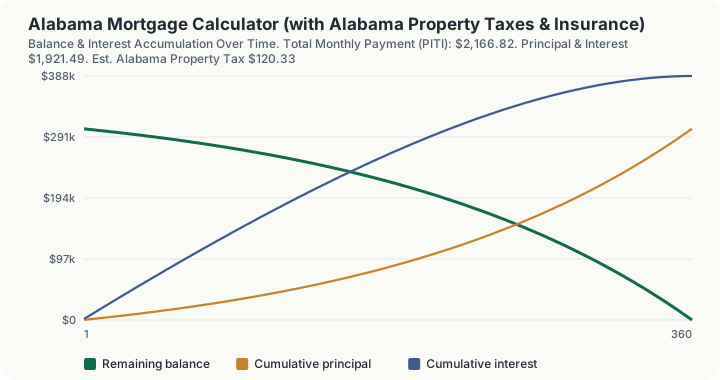
Quick Answer: A $380,000 home in Alabama with 20% down at a 6.5% interest rate carries a total monthly payment of about $2,166.82, including principal and interest, Alabama's low 0.38% effective property tax rate, and an estimated $125 monthly homeowners insurance premium.
Overview
Homebuyers relocating to Alabama from higher-tax states often expect their whole cost of living to drop, and on the property tax line that expectation actually holds up. Alabama's constitution caps millage rates well below what most states allow, and the state leans on sales and income tax instead of property tax to fund public services. The result is one of the lowest effective property tax rates in the country. This calculator applies a 0.38% effective statewide rate, in line with published averages for Alabama, so the tax portion of a monthly PITI payment stays modest even on a mid-priced home.
The tool takes a home price, a down payment percentage, and an interest rate, then works out a complete PITI (Principal, Interest, Taxes, Insurance) figure rather than a bare loan payment: standard 30-year fixed principal and interest, the modeled Alabama property tax, a flat insurance placeholder, plus total interest paid over the full loan term.
Alabama also offers a homestead exemption for owner-occupants and further relief for homeowners 65 and older, neither of which this calculator applies, so an eligible buyer's real bill may land somewhat below this estimate. Paired with a broadly low cost of living across most of the state, that keeps Alabama's monthly carrying costs, taxes included, well under what a similarly priced home would run in the Northeast or Illinois. Treat this as a baseline rather than a final number: coastal Baldwin and Mobile counties layer their own municipal millage on top of the state rate.
How This Is Calculated
The engine runs a 30-year fixed-rate amortization plus a monthly escrow estimate, using the amortization primitive:
- Down payment and loan principal. Down Payment = Home Price × Down Payment %. Loan Principal = Home Price − Down Payment.
- Principal & interest. The loan principal is amortized over a fixed 360-month (30-year) term using the standard annuity payment formula:
where P is the loan principal, i is the monthly rate (APR ÷ 12), and n is 360 months.
- Property tax estimate. Monthly Property Tax = Home Price × 0.38% ÷ 12, reflecting Alabama's low effective statewide property tax rate applied to the full purchase price as an assessed-value proxy.
- Insurance estimate. A flat $125 monthly homeowners insurance estimate is added.
- Total PITI. Total Monthly Payment = Principal & Interest + Monthly Property Tax + Monthly Insurance.
Worked Example
Using the calculator's own baseline inputs, which match its published test vector:
- Home Purchase Price: $380,000
- Down Payment: 20%
- Interest Rate (APR): 6.5%
Step by step: - Down payment: $380,000 × 20% = $76,000.00 - Loan principal: $380,000 − $76,000 = $304,000.00 - Monthly rate: 6.5% ÷ 12 = 0.5417% per month - Principal & interest (360 months): $1,921.49 - Monthly Alabama property tax: $380,000 × 0.38% ÷ 12 = $120.33 - Monthly insurance estimate: $125.00 - Total monthly payment (PITI): $1,921.49 + $120.33 + $125.00 = $2,166.82 - Total interest paid over 30 years: $387,735.24
This matches the calculator's verified test vector: a $304,000 loan principal, a $1,921.49 principal-and-interest payment, and a 360-row amortization schedule. Notice that property tax contributes only about 6% of the total payment here, a direct result of Alabama's below-average effective tax rate; the same home price and down payment in a state with a 2% effective rate would add roughly $633/month in tax alone.
What This Does Not Account For
- County-level millage variation. Alabama's 0.38% figure is a statewide average; actual millage rates set by individual counties and school districts vary, and homes inside incorporated cities often carry additional municipal millage on top of the county rate.
- Homestead exemptions. Alabama offers a homestead exemption that reduces the taxable assessed value for owner-occupied primary residences, and an additional exemption for homeowners 65 and older; this calculator does not apply either exemption, so actual bills for eligible owners may be lower than shown.
- Private Mortgage Insurance (PMI). With less than 20% down, most conventional loans require PMI until a homeowner reaches 20-22% equity; this calculator's flat $125 insurance estimate covers only homeowners insurance, not PMI.
- HOA dues, flood insurance, and closing costs. Homeowners association fees, flood zone insurance premiums (relevant along Alabama's Gulf Coast), and one-time closing costs are not included in this monthly estimate.
- Rate locks, points, and loan-specific fees. The interest rate entered is treated as the note rate for the life of the loan; origination fees, discount points, and rate-lock costs are not modeled.
Common Pitfalls
- Assuming Alabama's low property tax rate applies everywhere in the state uniformly. City and county millage rates layer on top of the state base rate and vary by school district and municipality; always confirm the actual millage for the specific parcel before finalizing a budget.
- Forgetting to apply for the homestead exemption after closing. New Alabama homeowners who fail to file for the homestead exemption can end up paying meaningfully more property tax than necessary on their primary residence.
- Underestimating insurance costs along the Gulf Coast. Coastal Alabama counties near Mobile and Baldwin can carry significantly higher windstorm and flood insurance premiums than this calculator's flat $125 statewide estimate reflects.
- Ignoring PMI on a low down payment. A down payment below 20% typically triggers a separate PMI charge not included in this tool's insurance line item, which can meaningfully understate the true total payment.
- Comparing a 15-year and 30-year quote using only the monthly payment. A 15-year term at the same rate produces a higher monthly payment but dramatically less total interest over the life of the loan; this calculator models the standard 30-year term only.
Frequently Asked Questions
Why is Alabama's property tax rate so much lower than other states?
Does this calculator apply Alabama's homestead exemption?
Is PMI included in the insurance estimate?
How much does a larger down payment change the monthly payment?
Why is total interest over 30 years so much larger than the loan principal?
Sources
- Alabama Department of Revenue, Property Tax Division: statewide millage rates and homestead exemption guidance. revenue.alabama.gov
- Consumer Financial Protection Bureau (CFPB): Qualified Mortgage standards and PMI disclosure requirements. consumerfinance.gov
Also consulted: Alabama Department of Insurance: homeowners and windstorm insurance market data for Gulf Coast counties.