Quick Answer: On a $380,000 Delaware home with 20% down at 6.5%, the total monthly payment lands near $2,195, with property tax contributing just $149 of that thanks to Delaware's 0.47% effective rate, one of the lowest in the nation.
Overview
Delaware routinely appears near the bottom of national property tax rankings, and the gap between Delaware and high-tax neighbors like Connecticut or New Jersey is large enough to change monthly affordability math meaningfully. This calculator applies Delaware's 0.47% effective property tax rate to the home's purchase price, adds a flat monthly homeowners insurance estimate, and produces a full PITI (Principal, Interest, Taxes, Insurance) payment so buyers can see how much of their monthly cost is actually financing versus the comparatively light ongoing carrying cost that draws many retirees and out-of-state buyers to Delaware in the first place.
Delaware's low property tax exists alongside a state income tax, unlike Florida, so the state is not a pure no-tax destination. But for a mortgage payment specifically, the property tax side of the equation is unusually favorable, and this calculator isolates that effect so a buyer comparing Delaware against a higher-tax state can see the monthly dollar difference rather than a vague statement that "Delaware taxes are low."
How This Is Calculated
- Down payment and loan principal. The down payment percentage is applied to the home price, and the remainder becomes the financed loan principal.
- Principal and interest. The loan principal amortizes over a standard 360-month (30-year) fixed term using PMT = P × r / (1 − (1 + r)^−n), with r equal to the monthly rate (annual APR divided by 12).
- Property tax. Delaware's statewide effective average of 0.47% is applied to the full home purchase price and divided by 12 for a monthly escrow figure.
- Homeowners insurance. A flat $125 monthly estimate is added, representing typical coverage costs, though coastal Sussex County properties near the Delaware beaches often carry higher premiums than inland Kent or New Castle County homes.
- Total PITI. Principal and interest, monthly tax, and monthly insurance sum to the headline monthly payment.
Worked Example
Using the calculator's baseline inputs: a $380,000 home, 20% down, and a 6.5% 30-year fixed rate.
- Down payment: $380,000 × 20% = $76,000
- Loan principal: $380,000 − $76,000 = $304,000
- Monthly rate: 6.5% ÷ 12 = 0.5417%
- Principal and interest: amortizing $304,000 over 360 months yields approximately $1,921.49 per month
- Monthly property tax: $380,000 × 0.47% ÷ 12 = $148.83
- Monthly insurance: $125.00 flat estimate
- Total PITI: $1,921.49 + $148.83 + $125.00 = approximately $2,195.32 per month
Compare that $148.83 monthly tax line against the $525.67 a Connecticut buyer would owe on the same $380,000 home. Over a full year, that difference alone is roughly $4,500, money that in Delaware stays available for the mortgage principal, savings, or simply a lower total housing cost.
Reading the Rate Sweep and the Crossover Month
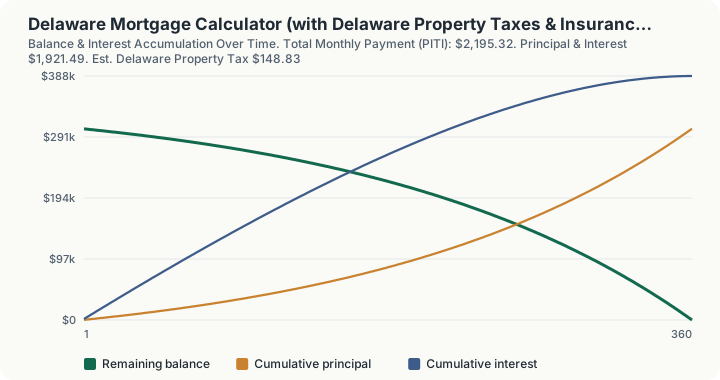
The amortization schedule holds the inputs still and advances the months. Moving the inputs instead produces four comparisons the schedule cannot show, and the schedule itself contains one genuine turning point.
An eighth of a point, priced. Taking the rate from 6.5% to 6.625% moves the monthly principal and interest from $1,921.49 to $1,946.55, a difference of $25.06 a month, and lifetime interest from $387,732.82 to $396,756.31. That single eighth of a point costs $9,021.08 over thirty years on a $304,000 loan. A full point, from 6.5% to 7.5%, takes the payment to $2,125.61 and lifetime interest to $461,220.45, which is $73,485.22 more.
The down payment, priced. At 10% down the loan principal is $342,000 and PITI reaches $2,435.50 a month. At 20% it is $2,195.32, and at 25% it is $2,075.22. The step from 10% to 20% is worth $240.18 a month, and lifetime interest falls from $436,202.14 to $387,732.82, a saving of $48,466.91 for $38,000 of additional cash at closing.
The crossover month, which is a real threshold in the schedule. Payment 232 splits $1,921.49 into $957.19 of principal and $964.30 of interest: interest is still winning. Payment 233 splits it into $962.37 of principal and $959.12 of interest. That is the month the loan finally sends more to principal than to the lender, and on these inputs it arrives in year twenty of thirty, with $176,105.09 still outstanding and $319,812.26 of interest already paid.
Where the schedule stands at the usual milestones. After twelve payments the balance is $300,602.08, meaning $3,397.92 of the $304,000 principal has been repaid against $19,659.96 of interest. After sixty payments the balance is $284,577.15 and cumulative interest is $95,866.55. After 120 payments, a third of the term, the balance is $257,718.88: fifteen percent of the principal retired, and $184,297.68 of interest paid.
What the PITI figure leaves out. The $2,195.32 is principal and interest plus $148.83 of Delaware property tax and a flat $125.00 insurance estimate. There is no mortgage insurance in that figure at any down payment: at 10% down the engine still returns a $0.00 PMI line on every row of the schedule, where a real Delaware lender would charge it until the loan reached 78% of value. The insurance figure is a fixed $125.00 rather than a rate against the property value, and neither HOA dues nor Delaware's realty transfer tax at closing appears anywhere.
What This Does Not Account For
- County-level rate differences. Delaware's three counties, New Castle, Kent, and Sussex, each set their own local tax rates on top of school district levies, so the 0.47% statewide effective average is a planning figure, not an address-specific quote.
- Delaware's realty transfer tax. A one-time state and county transfer tax applies at closing, separate from the recurring monthly payment modeled here, and can be a meaningful upfront cost that buyers should budget alongside the down payment.
- Coastal insurance premiums. Homes near Rehoboth Beach, Bethany Beach, and other Sussex County coastal areas often carry flood and windstorm coverage costs well above the flat $125 monthly estimate used in this baseline model.
- Private mortgage insurance. This calculator assumes the 20% down payment scenario avoids PMI; a smaller down payment would add a PMI line item not reflected here.
- Delaware state income tax. Delaware pairs its low property tax with a graduated state income tax, which affects overall affordability but is outside the scope of a monthly mortgage payment calculation.
Common Pitfalls
- Assuming Delaware is a no-tax state across the board. Delaware has no sales tax but does levy income tax and property tax, just at property tax rates well below the national average; conflating "low tax" with "no tax" leads to inaccurate total cost-of-living comparisons.
- Using a national average property tax rate instead of Delaware's actual figure. Applying a generic 1.0% or 1.1% national average rate to a Delaware home overstates the monthly tax burden by more than double.
- Overlooking the one-time realty transfer tax at closing. Delaware's transfer tax, split between state and county, is due at closing and is separate from the ongoing monthly property tax modeled in PITI.
- Ignoring county-to-county variation within Delaware. Sussex County beach communities and New Castle County suburbs can carry different effective rates once local levies are included, even though both fall under the same statewide average.
- Skipping insurance cost verification for coastal properties. A flat $125 monthly estimate understates true costs for homes within flood zones near the Atlantic coast, where premiums can run substantially higher.
Frequently Asked Questions
Why is Delaware's property tax rate so much lower than most states?
Does this calculator reflect my specific county's tax rate?
Is Delaware a good state for retirees from a housing cost perspective?
What is Delaware's realty transfer tax and is it included here?
How does a smaller down payment change this calculation?
Sources
- Delaware Division of Revenue, realty transfer tax guidance. revenue.delaware.gov
- Consumer Financial Protection Bureau, Regulation Z and mortgage disclosure standards. ecfr.gov/current/title-12/chapter-X/part-1026
Also consulted: Delaware Office of the State Fire Marshal and county assessor offices, county-level property tax rate publications.