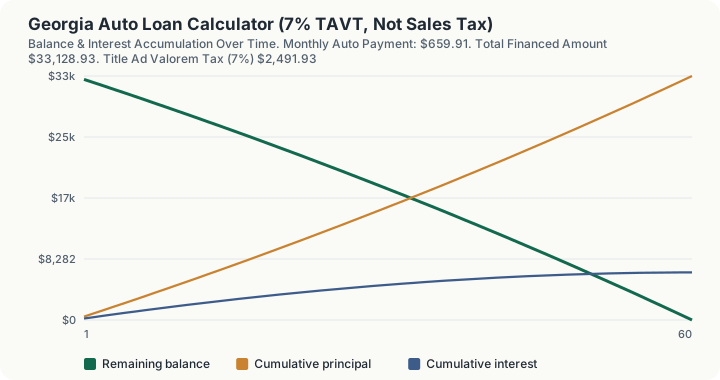
Quick Answer: A $35,000 vehicle in Georgia with $5,000 cash down, a $599 dealer documentation fee, a 60-month term, and a 7.25% APR carries a $659.91 monthly payment. Georgia charges no sales tax on titled vehicles. It collects a one-time $2,491.93 Title Ad Valorem Tax at 7% of fair market value, plus $38 in title and plate fees, financing $33,128.93.
Overview
Georgia does not tax car purchases with sales tax. Vehicles titled in Georgia are exempt from state and local sales and use tax, and under O.C.G.A. Sec. 48-5C-1 they instead pay a one-time Title Ad Valorem Tax, universally called TAVT, of 7.0% of fair market value at titling.
This is not a labeling difference. Three things follow from it.
First, there is no county or city add-on. Metro Atlanta's combined sales tax reaches 8% or 9%, but none of that touches a titled vehicle. The TAVT rate is 7.0% everywhere in Georgia, from Fulton County to the smallest rural tag office. On this baseline purchase, applying an 8% metro sales tax rate would produce $2,847.92 instead of the correct $2,491.93.
Second, the base is fair market value, not necessarily the price you paid. For a new vehicle, fair market value is the retail selling price including dealer add-ons and fees, less the trade-in value and less any rebate, so the price you negotiate does set the base. For a used vehicle, fair market value comes from the Georgia DOR Motor Vehicle Assessment Manual. If you buy a used car for less than the manual says it is worth, you can still owe TAVT on the manual value. A used-car estimate built from the negotiated price alone will be wrong.
Third, TAVT replaced the annual "birthday tax" for vehicles titled on or after 1 March 2013. You pay once at titling and then only the flat $20 plate fee each year. Vehicles that predate the switch and never opted in still pay annual ad valorem at local mill rates.
This calculator models a new-vehicle dealer purchase, where the retail selling price is the fair market value.
Auto Loan APR by Credit Score
The APR columns below are national averages, not Georgia figures. No primary source publishes average auto loan APR by state: Experian's report has no geographic cut, the CFPB publishes state origination volume but no rates, and the New York Fed publishes state delinquency only. The payment column is the part that is specific to Georgia, because it runs this calculator's own Georgia tax and fee rules at each tier's rate.
| Credit Tier | VantageScore 4.0 | Avg New APR | Avg Used APR | Est. Payment in Georgia |
|---|---|---|---|---|
| Super prime | 781-850 | 4.55% | 6.30% | $618.38 |
| Prime | 661-780 | 6.23% | 8.77% | $644.02 |
| Nonprime | 601-660 | 9.67% | 14.03% | $698.52 |
| Subprime | 501-600 | 13.44% | 19.42% | $761.27 |
| Deep subprime | 300-500 | 16.01% | 21.77% | $805.81 |
Payment assumptions: $35,000 vehicle price, $0 trade-in, $5,000 cash down, $599 dealer documentation fee, 60-month term, new-vehicle APR applied to the Georgia delivered price including tax and statutory fees. At the 6.39% overall new-car average the same purchase costs $646.50 a month.
The score bands are VantageScore 4.0, not FICO. The same borrower can land in a different tier under each model, so a FICO score pulled from a card issuer will not always match the band here. Source: Experian, State of the Automotive Finance Market, Q1 2026, slide 45.
What Moves Your Payment
Each row changes one input and leaves the rest at the baseline below. The dollar effects are this calculator's own output for Georgia, not a rule of thumb.
| Factor | What Changes | Effect on Monthly Payment | Effect on Total Interest |
|---|---|---|---|
| Vehicle Price | Each extra $1,000 of price raises both the amount financed and the Title Ad Valorem Tax (TAVT) base, so the tax rises with it. | +$21.31 | +$208.82 |
| Trade-In Allowance | A $1,000 allowance cuts the amount financed by $1,000 and reduces the Title Ad Valorem Tax (TAVT) base by the same amount, so it saves tax as well as principal. | -$21.32 | -$208.83 |
| Cash Down Payment | A $1,000 larger down payment cuts the amount financed by $1,000. It never reduces the Title Ad Valorem Tax (TAVT), which is assessed on the price, not on what you borrow. | -$19.92 | -$195.16 |
| Dealer Doc Fee | A $100 higher documentation fee adds $100 to the amount financed and is inside the Title Ad Valorem Tax (TAVT) base, so it is taxed on top of itself. | +$2.13 | +$20.88 |
| Longer Term | Stretching the same balance from 60 months to 72 months spreads the principal over twelve more payments at the same rate. | -$91.11 | +$1,359.22 |
Baseline: $35,000 vehicle price, $0 trade-in, $5,000 cash down, $599 documentation fee, 60 months at 7.25% APR, giving a $659.91 payment and $6,465.49 of total interest.
How This Is Calculated
Georgia does not apply sales tax to a titled vehicle at all. It charges a one-time 7% Title Ad Valorem Tax on fair market value instead, which also replaces the annual ad valorem tax. Four steps.
1. Fair market value. For a new vehicle, O.C.G.A. Sec. 48-5C-1 defines fair market value as the retail selling price, which includes dealer add-ons and fees, reduced by the trade-in value of another motor vehicle and by any rebate.
2. TAVT.
One rate, statewide, with no local component and no dollar cap.
3. Title and plate. A fixed $38, being the $18 certificate of title fee and the $20 flat annual license plate fee. Georgia's plate fee is neither weight based nor value based for standard passenger vehicles. These fees are outside the TAVT base.
4. Amortization. The financed balance amortizes as a fixed-rate installment loan:
where $P$ is the amount financed, $i$ is the monthly rate (APR divided by 12), and $n$ is the term in months. Each period's interest is the outstanding balance times $i$, the remainder reduces principal, and the schedule reconciles to zero at maturity.
Worked Example
Georgia replaced both sales tax and annual ad valorem tax on cars with one Title Ad Valorem Tax at 7%, paid once. There is no local layer to look up, which makes the arithmetic short and the doc fee unusually expensive.
- Retail selling price: $35,000
- Trade-in allowance: $0
- Cash down: $5,000
- Dealer doc fee: $599
- Term: 60 months at 7.25% APR
Step 1 -- Fair market value, the TAVT base. Retail selling price plus the doc fee, less any trade-in: $35,000 + $599 - $0 = $35,599.00
Step 2 -- TAVT at 7%. $35,599.00 x 7% = $2,491.93
Step 3 -- Title and plate, outside the base. $18.00 title + $20.00 plate = $38.00
Step 4 -- Total delivered price. $35,000 + $599.00 + $2,491.93 + $38.00 = $38,128.93
Step 5 -- Amount financed. $38,128.93 - $0 trade-in - $5,000 cash down = $33,128.93
Step 6 -- The monthly payment. $33,128.93 at 7.25% over 60 months = $659.91
Step 7 -- Month 1. $33,128.93 x (7.25% / 12) = $200.15 interest, $459.76 principal, balance $32,669.17
Step 8 -- Month 2. $32,669.17 x (7.25% / 12) = $197.38 interest, $462.53 principal, balance $32,206.64. Cumulative interest: $397.53
Step 9 -- The running total. By month 12, $2,214.77 of interest paid and $27,424.78 outstanding. Over 60 months, $6,465.49
Add a $10,000 trade-in and fair market value drops to $25,599. TAVT falls to $1,791.93, a saving of $700, and the payment drops to $446.77. The credit is worth 7% of the allowance, which is a higher return per trade-in dollar than most states offer, because Georgia has no lower automotive rate and no cap on the credit.
The doc fee matters more here than the number suggests. Because it is part of the retail selling price on a new vehicle, negotiating the $599 fee away removes $41.93 of TAVT along with it, and the payment falls to $647.14. You are negotiating $640.93, not $599.
What This Does Not Account For
- Used-vehicle valuation. For used vehicles the TAVT base is the Georgia DOR Motor Vehicle Assessment Manual value, not the price on your buyer's order. This calculator applies the rate to the value you enter, so for a used purchase you should enter the manual value rather than the negotiated price. Dealer-sale value adjustments and trade-in treatment also work differently for used vehicles than for new ones.
- Reduced TAVT rates. Georgia sets 3% for people establishing residency and titling a vehicle they already own, and 0.5% for immediate-family transfers and inheritance. This calculator applies only the standard 7.0% rate.
- Annual ad valorem on pre-2013 vehicles. A vehicle titled before 1 March 2013 that never opted into TAVT still pays the annual ad valorem tax at local mill rates, which this calculator does not model. Certain non-titled vehicles remain in that system too.
- Alternative-fuel vehicle fees. Georgia charges a substantial additional annual registration fee for alternative-fuel vehicles, on top of the $20 plate fee.
- Fee amounts from secondary sources. The $18 title fee and $20 plate fee come from summaries of the Georgia DOR and county tag office schedules rather than a live fee page. Confirm at your county tag office.
- Rate stability. Georgia law contains a mechanism to adjust the TAVT rate, so the 7.0% figure should be re-checked at each tax year rollover.
- GAP insurance, extended warranties, and negative equity, unless you fold them into the price yourself.
Common Pitfalls
- Applying metro Atlanta's sales tax rate to a car. Fulton, DeKalb, and the surrounding counties reach 8% to 9% combined on ordinary goods. None of it applies to a titled vehicle. Using 8% on this baseline overstates the tax by $355.99.
- Estimating a used car's TAVT from the price you paid. The assessment manual governs. A good deal on a used car does not reduce the TAVT the way a good deal on a new car does, which is one of the sharpest differences between Georgia and a conventional sales tax state.
- Expecting a county line on the buyer's order. There is none. If a quote shows a local vehicle tax add-on, question it.
- Treating TAVT as deductible the way sales tax is. TAVT is a title fee levied once, and it is not the annual ad valorem tax that used to be deductible as a personal property tax. Ask a tax preparer rather than assuming.
- Ignoring that the doc fee is inside the base on a new car. Every dollar of doc fee costs seven cents of TAVT on top of itself.
- Judging a loan by the monthly payment alone. Stretching the baseline $33,128.93 balance from 60 to 72 months lowers the payment to $568.80 but raises total finance charges from $6,465.49 to $7,824.81.
Frequently Asked Questions
What is the sales tax on a car in Georgia?
Does TAVT vary by county in Georgia?
Is TAVT based on what I paid for the car?
Does a trade-in reduce TAVT?
Do I still pay Georgia's annual birthday tax?
Are there lower TAVT rates for some buyers?
Sources
- O.C.G.A. Sec. 48-5C-1 (Title Ad Valorem Tax: 7.0% of fair market value, exemption from sales and use tax and from annual ad valorem tax, definition of fair market value for new and used vehicles, trade-in and rebate reductions) sec.gov
- Georgia Department of Revenue, Vehicle Taxes: Title Ad Valorem Tax (TAVT) and Annual Ad Valorem Tax guidance. dor.georgia.gov
- Consumer Financial Protection Bureau, Truth in Lending Act (Regulation Z, 12 CFR Sec. 1026.22) disclosure requirements for installment credit. ecfr.gov/current/title-12/chapter-X/part-1026
Also consulted: Georgia Department of Revenue, Motor Vehicle Assessment Manual (fair market value for used vehicles); Georgia Department of Revenue and county tag office fee schedules (title fee and annual license plate fee); Experian, State of the Automotive Finance Market, Q1 2026, slide 45 (average new and used auto loan APR by VantageScore 4.0 credit tier; national, no state level cut published).