Quick Answer: A $400,000 home in Hawaii carries an estimated $1,080.00 in annual property tax at the state's 0.27% effective rate, or about $90.00 a month.
The Lowest Effective Rate in the Country
Property tax bills in Hawaii run on an average effective rate of 0.27%, good for a #50 national ranking and among the ten lowest effective property tax rates in the country. That is less than half the national average of roughly 1.0%, based on the average effective rate across all 50 states. Compared with the rest of the West, which averages roughly 0.71%, Hawaii lands well below its neighbors.
Like its neighbors elsewhere in the West, Hawaii relies on property tax as the primary funding mechanism for public schools, emergency services, and county infrastructure, with local taxing authorities setting the actual millage each year.
In real estate underwriting, this rate feeds directly into monthly escrow and cap-rate math for Hawaii property, which is exactly what this calculator is built to model before a buyer commits to a purchase price or a lender sets up impound accounts for the loan.
How This Is Calculated
Hawaii has the lowest effective property tax rate in the country at 0.27%, and it is the only state where property tax is entirely a county matter with no state levy at all. The four counties set rates by classification and grant large owner-occupant exemptions, which is how bills stay modest on some of the most expensive real estate in the United States.
None of that detail is asked for here. This calculator works one level up, applying Hawaii's average effective property tax rate of 0.27% to the value you enter. That rate is the ratio of property taxes actually paid to home value across the state, so the assessment ratios, caps, and exemptions described above are already baked into it.
Working through it in order:
- Start from the county assessment. Each county values property at full market value and sorts it into a class such as owner-occupied, residential, or hotel and resort.
- Take off the owner-occupant exemption. Claiming it both removes a large slice of value and moves the property into a lower-rate class.
- Multiply by the effective rate. At 0.27%, a $400,000 home in Hawaii comes to $1,080 a year before any exemption you enter above.
- Divide by twelve for escrow. That same home works out to $90.00 a month set aside in a mortgage escrow account.
- Compare it against your own bill. An owner-occupant and an absentee investor holding identical Hawaii condos can pay very different rates on the same value. Your county's number is the one that governs; this figure tells you whether it is roughly where a Hawaii home of that value ought to land.
Worked Example
Using this calculator's baseline inputs: a $400,000 home in Hawaii, taxed at the state's 0.27% average effective rate (rank #50 of 50 states).
- Start with the assessed value. The home is assessed at its full $400,000.00 market value, with no homestead exemption applied in this baseline scenario.
- Apply the effective rate. $400,000.00 × 0.27% = $1,080.00 in annual property tax, Hawaii's statewide average effective rate.
- Convert to a monthly escrow. Lenders typically collect property tax in twelve equal installments alongside principal and interest: $1,080.00 ÷ 12 = $90.00 per month.
- Project a five-year hold. At a flat rate, five years of ownership totals $1,080.00 × 5 = $5,400.00, before any reassessment, exemption change, or millage increase.
At 0.27%, Hawaii carries one of the lightest property tax burdens nationally, ranking #50 of 50 states, though actual bills still vary by county and municipality.
Why the Hawaii Sweep Has No Step In It
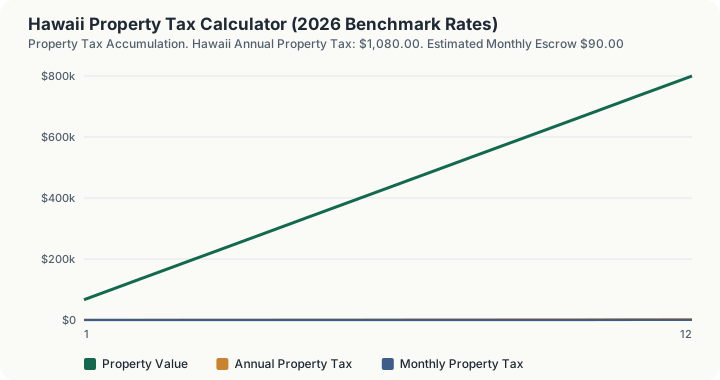
Hawaii's 0.27% average effective property tax rate is the lowest in the country, 50th of 50, and the twelve tiers above rise in a perfectly straight line. That flatness is a property of this engine, not of Hawaii: the calculator holds one statewide effective rate and applies it to market value less your exemption entry. Honolulu's actual graduated Residential A classification, which charges a higher rate on the portion of a non-owner-occupied property's value above a threshold, is a genuine step in Hawaii law and it is absent from this code path entirely.
Two rungs. Row 6 is the $400,000 baseline at $1,080.00 a year, $90.00 a month. Row 12 doubles it to $800,000 and returns $2,160.00 a year, $180.00 a month. A million-dollar Hawaii property, well past the top of the sweep, returns $2,700.00, which is still less than a $170,000 Connecticut home pays.
The marginal figure. Each additional $10,000 of Hawaii market value costs $27.00 a year, $2.25 a month. The engine returns $1,107.00 at $410,000 against $1,080.00 at $400,000. On a rate this low the marginal figure is small enough that valuation disputes rarely repay the filing effort, which is a real consequence of the number rather than an observation about Hawaii.
The reverse question. $555,555.56 of Hawaii market value returns exactly $1,500.00 a year and $125.00 a month. Framed as a budget: $125 a month of escrow carries over half a million dollars of Hawaii property, where the same $125 a month covers about $90,000 in Connecticut.
The Honolulu home exemption, and the limitation behind it. Honolulu's owner-occupant home exemption removes a fixed amount of assessed value, $120,000 for owners under 65 in recent schedules. Entering $120,000 here takes taxable value to $280,000 and the bill to $756.00, a $324.00 saving against the baseline. The engine treats this correctly only because Hawaii counties assess at 100% of market value, so no ratio conversion is needed, unlike the states where a 40% or 70% ratio sits between the two figures. What the engine still cannot do is switch rate class: claiming the home exemption in Honolulu also moves a property out of Residential A, and that reclassification is worth far more than the exemption itself on high-value parcels. Neither the classification nor its rate is available to this calculator.
What This Does Not Account For
- Specific hyper-local county and municipal millage district variations within Hawaii.
- County-specific special assessment or improvement district charges. Hawaii's four counties administer property tax independently, and any special assessment for road, water, or sewer improvements in a given development is set at the county level, not captured in this calculator's statewide figure.
- Commercial vs residential assessment classification differentials.
- Property tax appeal reductions or localized board of equalization adjustments.
Common Pitfalls
- Confusing Market Fair Value with Assessed Basis: Some jurisdictions assess property at fractional ratios rather than 100% of market value.
- Failing to File Homestead Paperwork: Homestead exemptions are rarely automatic; homeowners must file timely paperwork with the county appraisal district.
- Underestimating Post-Sale Supplemental Assessments: Purchasing a newly constructed or reassessed property often triggers catch-up supplemental tax bills.
- Ignoring Property Tax Appeal Windows: Missing the annual 30-to-60 day statutory protest window forfeits the right to challenge over-assessed property values for that tax year.
Frequently Asked Questions
How high are property taxes in Hawaii?
When are property taxes due in Hawaii?
How can I lower my property taxes in Hawaii?
Does purchasing a home trigger a property tax reassessment?
Sources
- U.S. Census Bureau: American Community Survey (ACS) Real Estate Assessment Benchmark Data. census.gov/programs-surveys/acs
Also consulted: Hawaii county Real Property Assessment Divisions: Property Tax Assessment Guidance.