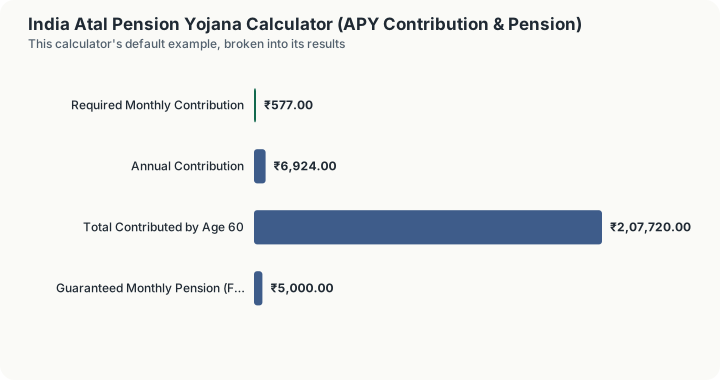
Quick Answer: Joining the Atal Pension Yojana (APY) at age 30 and targeting the maximum ₹5,000/month guaranteed pension from age 60 requires a monthly contribution of ₹577, paid for 30 years, totaling roughly ₹2,07,720 in lifetime contributions in exchange for a Central Government-guaranteed pension for life.
Overview
This calculator is built specifically for India's Atal Pension Yojana (APY), a Central Government-guaranteed pension scheme aimed at workers in the unorganized sector, and every figure is shown in Indian Rupees (₹). It is not a market-linked retirement calculator. Unlike NPS, PPF, or EPF -- where your eventual payout depends on contribution amounts and investment returns -- APY works backward from a guaranteed outcome: you choose a target monthly pension (₹1,000, ₹2,000, ₹3,000, ₹4,000, or ₹5,000, payable for life from age 60), and PFRDA's published contribution table tells you exactly what you must pay each month, based on your age when you join, to lock in that guarantee.
Eligibility runs from age 18 to 40 at entry, and -- since 1 October 2022 -- anyone who is or has been an income-tax payer is no longer eligible to join APY at all, a restriction that meaningfully narrows the scheme's target population toward genuinely unorganized-sector workers without other guaranteed pension coverage.
How This Is Calculated
APY does not use a formula in the way PPF or EPF do -- instead, PFRDA publishes a fixed table specifying the exact monthly contribution required for every combination of entry age (18 through 40) and target pension slab (₹1,000 through ₹5,000), unchanged since the scheme's 2015 launch. This calculator looks up your entry age and chosen target pension directly against that table rather than computing a formula, since the government has fixed these amounts by regulation rather than leaving them to be derived.
The logic behind the table is intuitive even without deriving it yourself: the earlier you join, the more years your contributions have to build toward the guaranteed pension, so the required monthly amount is dramatically lower at age 18 than at age 40 for the same target pension.
Important verification note: the specific contribution table used by this calculator reflects the long-published, industry-standard APY figures that have remained unchanged since 2015 and were spot-checked against live 2026 reporting for several age/slab combinations (age 18 and age 39/40 entries). However, the full official PFRDA/NSDL contribution chart PDF could not be freshly re-fetched from a primary government source during this calculator's research pass due to access restrictions in the research environment. Before relying on this calculator for a binding financial decision, cross-check your specific entry age and target pension against your bank's or post office's current official APY contribution chart.
Worked Example
APY is a lookup rather than a projection, so the arithmetic worth showing is what the fixed table actually costs across a working life, and how fast the guaranteed pension repays it.
Step 1 -- Entry at 18, targeting the top ₹5,000 slab. Table contribution: ₹210 a month
Step 2 -- Years of contribution from that entry age. 60 - 18 = 42 years
Step 3 -- The annual cost. ₹210 × 12 = ₹2,520 a year
Step 4 -- Total paid in by age 60. ₹2,520 × 42 = ₹1,05,840
Step 5 -- Annual pension received from age 60. ₹5,000 × 12 = ₹60,000 a year
Step 6 -- How long the pension takes to repay the contributions. ₹1,05,840 / ₹60,000 = 1.76 years
Under two years of pension returns everything paid in across forty-two years, and the pension is guaranteed for life with a spouse continuation and a corpus return to the nominee after that. This is the strongest arithmetic in any of India's small-savings schemes, and it exists only because the entry was made at 18.
Step 7 -- The same ₹5,000 slab entered at 30. Contribution: ₹577 a month Years: 60 - 30 = 30 years Total paid: ₹577 × 12 × 30 = ₹2,07,720 Payback: ₹2,07,720 / ₹60,000 = 3.46 years
Step 8 -- The same slab at the maximum entry age of 40. Contribution: ₹1,454 a month Years: 20 Total paid: ₹1,454 × 12 × 20 = ₹3,48,960 Payback: ₹3,48,960 / ₹60,000 = 5.82 years
Waiting from 18 to 40 multiplies the monthly cost by roughly 6.9 times and the lifetime outlay by 3.3 times for an identical guaranteed pension. Every year of delay is expensive here in a way that is easy to miss, because the headline pension never changes.
Step 9 -- The cheapest possible commitment: age 18, ₹1,000 slab. Contribution: ₹42 a month Total paid over 42 years: ₹42 × 12 × 42 = ₹21,168 Annual pension: ₹1,000 × 12 = ₹12,000 Payback: ₹21,168 / ₹12,000 = 1.76 years
The ratio in step 9 is identical to step 6 because the official table scales the ₹1,000 through ₹5,000 slabs proportionally within each entry age. Choosing a slab decides the size of the commitment; choosing an entry age decides how good the deal is.
What This Does Not Account For
- Government co-contribution. APY originally offered a government co-contribution (50% of the subscriber's contribution, up to ₹1,000/year) for accounts opened in the scheme's early years, subject to eligibility conditions; the current status of this co-contribution for new subscribers was not independently confirmed against a primary PFRDA source in this research session, and this calculator does not assume any co-contribution is available.
- Death/disability benefits before age 60. APY provides for the pension (or the accumulated corpus) to pass to the spouse or nominee under specific rules if the subscriber dies or is permanently disabled before age 60; not modeled by this calculator, which only computes the standard contribution-to-pension path.
- Contribution frequency options. Contributions can be made monthly, quarterly, or half-yearly with different processing conventions; this calculator assumes standard monthly contributions.
- Late-payment penalties. APY charges a small penalty for delayed monthly contributions, scaled to the contribution amount; not modeled here.
- Exit before age 60. Voluntary exit before age 60 is permitted only in exceptional circumstances and returns only the subscriber's own contributions plus actual (not guaranteed) interest earned, forfeiting the pension guarantee; this calculator models only the standard, full-term path to age 60.
Common Pitfalls
- Assuming APY contributions grow with investment returns like NPS. APY is a guaranteed-benefit (not guaranteed-contribution) scheme -- the government bears the shortfall risk if actual fund returns fall short of what's needed to pay the promised pension, not the subscriber; this is fundamentally different from NPS's market-linked, subscriber-bears-the-risk structure.
- Joining late and being surprised by the cost. The monthly contribution required rises steeply with entry age for the same pension target -- someone joining at 40 pays roughly seven times what an 18-year-old pays for the identical ₹5,000/month guarantee.
- Not realizing income-tax payers are excluded. Since 1 October 2022, anyone who is or has been liable to pay income tax is ineligible to newly join APY -- a materially important eligibility change from the scheme's original open-to-all design.
- Confusing APY's fixed pension slabs with a flexible target. You must choose one of exactly five slabs (₹1,000/2,000/3,000/4,000/5,000); there is no option to target, say, ₹3,500/month.
- Assuming the contribution table is negotiable or estimate-based. Unlike an investment projection, the APY contribution table is a fixed, government-published schedule -- the amount for your specific entry age and pension slab is exact, not an estimate subject to market conditions.
Frequently Asked Questions
How much do I need to contribute to Atal Pension Yojana?
Can anyone join Atal Pension Yojana?
What happens if I stop paying my APY contributions?
Is the APY pension amount guaranteed?
Can I change my target pension slab after joining?
Sources
- Income Tax Department, Government of India, the official authority for the national tax authority this calculator relates to. incometax.gov.in/iec/foportal
Also consulted: PFRDA, pfrda.org.in/schemes/atal-pension-yojana-apy -- guaranteed pension slabs (₹1,000-5,000), entry age window (18-40), the 1 October 2022 income-tax-payer exclusion, fetched directly; PFRDA/NSDL APY Subscribers' Contribution Chart (official chart location: npscra.nsdl.co.in/nsdl/scheme-details/APY_Subscribers_Contribution_Chart_1.pdf) -- this calculator's contribution table reflects the long-published, industry-standard figures from this chart, with select entries cross-checked against live 2026 secondary reporting; a full fresh re-fetch of this specific PDF was not achievable in this research session due to environment access restrictions, and this is flagged as a verification gap for the platform owner to close with a direct manual check before this calculator's publish gate.