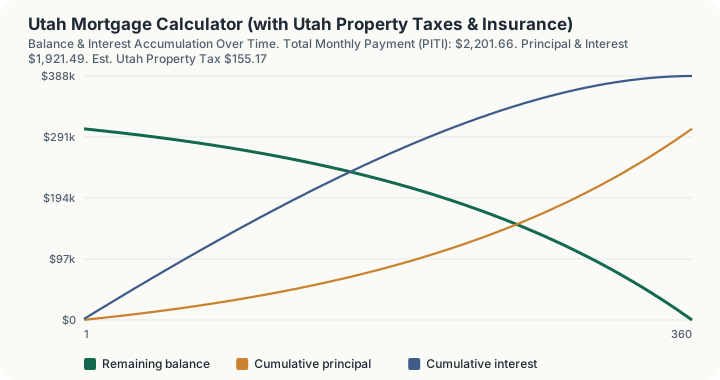
Quick Answer: On a $380,000 home with 20% down and a 6.5% fixed rate, the loan principal is $304,000, the principal and interest payment is about $1,921 a month, and Utah's below-average 0.49% effective property tax rate keeps the estimated total PITI payment near $2,202.
Overview
Utah consistently ranks among the states with the lowest effective property tax rates in the country, generally landing in the 0.4% to 0.6% range depending on county assessment practices. This calculator uses a 0.49% effective rate, which reflects that reality and produces a noticeably smaller property tax line than a buyer would see in a state like Vermont, New Jersey, or Illinois on an identically priced home. For buyers relocating to the Wasatch Front from higher-tax states, that gap is often the single biggest surprise in their total housing cost comparison, larger even than differences in home price.
The calculator combines a standard 30-year fixed-rate amortization with that property tax estimate and a flat monthly homeowners insurance placeholder to produce a full PITI (Principal, Interest, Taxes, Insurance) figure. This mirrors how an Utah mortgage lender underwrites a monthly payment and how loan servicers structure escrow accounts, so the headline number here should track closely with what appears on a Loan Estimate from an Utah-licensed lender, minus any private mortgage insurance that may apply on lower down payment scenarios.
How This Is Calculated
- Down payment and loan principal. Home Price times the down payment percentage gives the cash down; the remainder becomes the loan principal. At $380,000 with 20% down, that is $76,000 down and $304,000 financed.
- Principal and interest. The loan principal is amortized over 360 monthly periods (30 years) using the standard mortgage payment formula, PMT = P x [r(1+r)^n] / [(1+r)^n - 1], where r is the monthly rate (annual APR / 12).
- Property tax. Home Price times 0.49% gives the estimated annual property tax, divided by 12 for the monthly escrow contribution.
- Insurance. A flat $125 monthly estimate represents typical homeowners insurance premiums, added to complete the PITI total.
Worked Example
Using the platform's verified baseline: a $380,000 home, 20% down, and a 6.5% fixed rate.
- Home price: $380,000.00
- Down payment (20%): $76,000.00
- Loan principal: $304,000.00
- Monthly rate: 6.5% / 12 = 0.54167%
- Principal and interest (verified): $1,921.49
- Estimated monthly property tax (0.49% annual / 12): $155.17
- Estimated monthly insurance: $125.00
- Estimated total monthly PITI: approximately $2,201.66
- Total interest paid over 30 years: $387,732.82
Compare that to the 5% down payment scenario built into this calculator: a smaller down payment raises the loan principal to $361,000, which increases the principal and interest payment substantially even though the property tax and insurance lines stay identical, since they are based on home price rather than loan size.
The Crossover Month, and What an Eighth of a Point Costs
The twelve-row table on this page shows the first year of a 360-row schedule the engine generates in full. Four numbers from that schedule and from sweeping the three inputs describe almost everything a buyer wants to know here.
The crossover, which is real and computed. Payment 1 splits $1,921.49 into $274.82 of principal and $1,646.67 of interest: six dollars of interest for every dollar of equity. The two halves do not cross until payment 232, where the split is $957.19 of principal against $964.30 of interest and interest is still ahead by $7.13. Payment 233 is the first month principal wins, at $962.37 of principal against $959.12 of interest. That is nineteen years and five months into a thirty-year loan. By that month the schedule has already booked $319,812.26 of cumulative interest and the remaining balance is $176,105.09, still more than half the original $304,000 principal.
The cost of the next eighth of a point. Sweeping interestRate in its own 0.125 step, principal and interest runs $1,871.78 at 6.25%, $1,896.56 at 6.375%, $1,921.49 at 6.5%, $1,946.55 at 6.625% and $1,971.74 at 6.75%. Moving from 6.5% to 6.625% costs $25.06 a month, and over the full term it costs $9,021.08 in total interest, $387,732.82 rising to $396,756.31. Half a point, 6.25% to 6.75%, is $99.96 a month and $35,984.97 in lifetime interest on the same $304,000.
The reverse question: what price hits a target payment? Sweeping homePrice at 20% down and 6.5%, total PITI runs $1,983.06 at $340,000, $2,092.36 at $360,000, $2,201.66 at $380,000 and $2,310.95 at $400,000. Each $10,000 of purchase price adds a constant amount to PITI because both moving parts, the 80% financed principal and the 0.49% property tax, scale linearly with price. To hit a target monthly figure, read it off that ladder rather than solving for it.
The 20% down payment line, and why nothing happens there. This is the boundary buyers expect to matter, and in this engine it does not. Sweeping downPaymentPercent across 19.5%, 20% and 20.5%, total PITI runs $2,213.67, $2,201.66, $2,189.65: a smooth $12.01 per half-point of down payment, with no discontinuity at twenty. At 5% down the figure is $2,561.94 on a $361,000 principal. The engine calls generateAmortizationSchedule without a monthlyPMIAmount, so the PMI column of the computed schedule is $0.00 at every down payment from 0% to 100%. Private mortgage insurance is genuinely not modelled, which means every sub-20% figure on this page understates the real payment by whatever a lender would charge.
Right method against wrong method, priced. The common error is applying the quoted rate to the purchase price instead of to the loan principal. Running this calculator at 0% down, so that the financed amount equals the full $380,000, returns $2,401.86 in monthly principal and interest against the correct $1,921.49. That is $480.37 a month overstated, and $484,667.97 of total interest against $387,732.82, an overstatement of $96,933.85 across the term, purely from pricing the rate against the wrong base.
Two limitations sit inside this section rather than beside it. The 0.49% property tax rate is a literal in this calculator's config, not a lookup against the platform's state property tax table. It happens to match the 0.49% the table currently carries for Utah, but a correction to that table would not reach this page. And the tax line is computed off the full purchase price, not off the loan balance or any reassessed value: the property tax figure stays at $155.17 a month at 5%, 19.5%, 20% and 20.5% down, and it never falls as the balance amortises.
What This Does Not Account For
- Private mortgage insurance (PMI). Down payments below 20% typically trigger PMI, an added monthly cost not included in this calculator's output.
- County-level assessment variance. Utah's 0.49% figure is a statewide effective average; individual counties, and even individual parcels within a county, can carry different assessed values relative to market price.
- Utah's primary residence property tax exemption. Owner-occupied homes in Utah receive a 45% taxable value exemption that county assessors apply before calculating the bill; this calculator models the net effective rate after that exemption is already factored in, so it should not be stacked with an additional discount.
- HOA dues and special assessments. Many newer Utah subdivisions, particularly in fast-growing areas like Utah County, carry homeowners association fees that are not part of this calculation.
- Closing costs and prepaid escrow reserves. This tool models the ongoing monthly payment, not the cash needed at closing.
Common Pitfalls
- Forgetting PMI on low down payment scenarios. Buyers running the 5% down scenario should mentally add an extra $100 to $250 a month for PMI until they reach 20% equity, since the calculator does not model it directly.
- Assuming property tax scales with the loan amount rather than the home price. Property tax is calculated on home value, not on the outstanding loan balance, so paying down the mortgage faster does not reduce the tax bill.
- Underestimating insurance in wildfire-adjacent or hail-prone areas. The $125 monthly estimate is a national-style placeholder; homes in higher-risk foothill or canyon areas of Utah can see meaningfully higher premiums.
- Overlooking how a 25% higher home price scales every line item. The built-in scenario comparing a higher purchase price shows that property tax and insurance grow in step with price even while the down payment percentage stays fixed.
- Comparing 15-year and 30-year terms only by monthly payment. A shorter term carries a materially higher monthly principal and interest payment but dramatically less lifetime interest.
Frequently Asked Questions
Why is Utah's property tax rate so low compared to other states?
Does this calculator include private mortgage insurance?
How is the monthly property tax estimate calculated?
What happens to my payment if I put down less than 20%?
Is the $125 monthly insurance estimate accurate for my home?
Sources
- Utah State Tax Commission, Property Tax Division, effective rate and primary residence exemption guidance. tax.utah.gov
- Consumer Financial Protection Bureau (CFPB), Regulation Z and mortgage disclosure standards. ecfr.gov/current/title-12/chapter-X/part-1026
- Federal Reserve Bulletin, historical mortgage rate benchmarks. federalreserve.gov