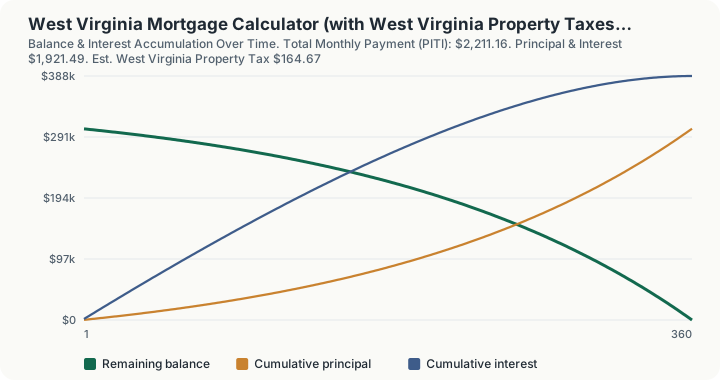
Quick Answer: On a $380,000 West Virginia home with 20% down at 6.5% APR, the loan principal is $304,000, principal and interest run about $1,921.49 a month, and adding West Virginia's 0.52% average effective property tax rate plus a $125 insurance estimate brings the full PITI payment to roughly $2,211.
Overview
West Virginia carries one of the lowest average effective property tax rates in the country, which is the single biggest reason a West Virginia mortgage payment tends to look smaller than the same loan amount would in a higher-tax state. This calculator estimates a full monthly housing payment, principal, interest, taxes, and insurance (PITI), using a 0.52% effective property tax rate applied to the home's purchase price and a flat $125 monthly homeowner's insurance estimate. Everything downstream of those two assumptions runs through the same 30-year amortization engine used by every mortgage calculator on this platform.
Property tax in West Virginia is assessed at the county level based on 60% of a property's appraised value, then multiplied by local levy rates that vary by county and school district. The 0.52% figure used here is a statewide effective average (tax paid divided by market value), not a single county's mill rate, so treat it as a planning estimate rather than the specific number your county assessor will bill.
How This Is Calculated
- Determine the loan principal. Down payment cash = home price × down payment percentage. Loan principal = home price − down payment cash, floored at zero.
- Amortize principal and interest over 30 years (360 months). The engine solves the standard fixed-rate mortgage payment formula:
where $P$ is the loan principal, $r$ is the monthly interest rate (APR ÷ 12), and $n = 360$.
- Estimate monthly property tax. Monthly tax = home price × 0.52% ÷ 12. Using the full purchase price (rather than an assessed value) keeps the estimate straightforward and comparable across scenarios.
- Add a flat insurance estimate. $125 per month is added as a placeholder for homeowner's insurance; actual premiums vary by coverage level, home age, construction type, and insurer.
- Sum to PITI. Total monthly payment = principal & interest + property tax + insurance. Private mortgage insurance (PMI) is not separately modeled here since the baseline scenario assumes 20% down, which conventionally avoids it.
Worked Example
Using the calculator's own defaults:
- Home price: $380,000
- Down payment: 20% ($76,000)
- Interest rate: 6.5% APR
Loan principal = $380,000 − $76,000 = $304,000. Amortized over 360 months at 6.5% APR (monthly rate 0.5417%), the principal and interest payment is $1,921.49. Monthly property tax = $380,000 × 0.52% ÷ 12 = $164.67. Adding the $125 insurance estimate gives a total PITI of $1,921.49 + $164.67 + $125.00 = $2,211.16 per month. Over the full 30-year term, cumulative interest paid on the $304,000 loan comes to roughly $387,733, more than the original loan amount itself, which is a useful illustration of how much compounding interest costs over three decades even at a moderate rate.
Lowering the down payment to 5% (the "low down" scenario) raises the loan principal to $361,000 and the monthly principal and interest payment accordingly, while also typically triggering PMI in the real world, which this calculator does not add automatically.
Pricing Equity Against Interest
The rate step, at one eighth of a point. Holding the $380,000 price and 20% down fixed, the engine returns a principal and interest payment of $1,896.56 at 6.375%, $1,921.49 at 6.500%, $1,946.55 at 6.625% and $2,022.52 at 7.000%. One eighth of a point therefore costs about $25 a month. Over the full 360 payments the same eighth is worth far more: total interest runs $378,763.14 at 6.375%, $387,732.82 at 6.500% and $396,756.31 at 6.625%, so the step from 6.375% to 6.500% costs $8,972.09 and the next one $9,021.08. Going from 6.5% to 7.0% costs $36,371.80 of interest, which is more than the down payment difference between 20% and 25%.
The down payment step, priced against the tax line. At 20% down the West Virginia PITI is $2,211.16. At 5% down it is $2,571.44, at 0% down $2,691.53, and at 25% down $2,091.06. The whole of that movement is principal and interest: the property tax line stays at $164.67 in every one of those four scenarios, because the engine applies the 0.52% rate to the purchase price and the purchase price does not change when the down payment does. Total interest moves from $387,732.82 at 20% down to $460,432.24 at 5% and $484,667.97 at 0%, so the fifteen points of equity between 5% and 20% are worth $72,700.34 of interest over the term.
The price step, and the only line that responds to it. Raising the price from $380,000 to $400,000 moves the West Virginia PITI from $2,211.16 to $2,320.95 and the tax line from $164.67 to $173.33. Dropping to $300,000 gives $1,771.96 with a tax line of $130.00. At $475,000, which is the calculator's higher-price scenario, PITI is $2,732.69 with $205.83 of monthly tax. Price is the only input that moves the escrow figure at all; rate and down payment leave it untouched.
The reverse question. A buyer with a fixed monthly budget can read those anchors backwards. In West Virginia at 6.5% with 20% down, $1,771.96 a month supports a $300,000 purchase, $2,211.16 supports $380,000, $2,320.95 supports $400,000 and $2,732.69 supports $475,000. Each additional $20,000 of purchase price costs roughly $109.79 a month at these inputs, of which $8.66 is the tax line and the rest is principal and interest.
Right method against wrong method, priced. The 5%-down scenario is the trap on this page. Moving from 20% down to 5% raises the reported PITI from $2,211.16 to $2,571.44, a difference of $360.28 a month, and a buyer comparing the two figures will conclude that is the cost of the smaller down payment. It is not. No private mortgage insurance is added anywhere in this code path, at any loan-to-value ratio, so the 5%, 0% and 20% figures are all quoted PMI-free. A real 5%-down loan carries a PMI charge on top of $2,571.44, and the engine has no input that would produce it.
What This Does Not Account For
- No private mortgage insurance is computed at any loan-to-value ratio. The 0%-down scenario returns $2,691.53 and the 20%-down scenario $2,211.16, and neither carries a PMI line. The gap between them is principal and interest only.
- The property tax line is the 0.52% effective rate applied to the purchase price, once. It is not applied to an assessed value, it is never reassessed, and it is held constant for all 360 months. The figure is $164.67 a month in month one and $164.67 a month in month 360.
- The $125 monthly insurance figure is a flat placeholder, not a quote. It does not vary with price, location or coverage, so it is identical at the $300,000 and $475,000 scenarios.
- The term is fixed at 360 months and the rate at a single APR. No 15-year option, no adjustable rate and no extra-payment input exists on this page, so every total-interest figure above assumes the loan runs to term unchanged.
- County-specific mill rates. Actual property tax bills depend on your county's levy rate and the 60%-of-appraised-value assessment ratio, which can push the effective rate above or below the 0.52% statewide average used here.
- Private mortgage insurance (PMI). Loans with less than 20% down typically require PMI, an additional monthly cost not included in the low-down-payment scenario.
- Homeowners association dues. HOA fees, where applicable, are a separate recurring cost not reflected in the PITI figure.
- Closing costs and prepaid escrow. Origination fees, title insurance, appraisal costs, and the initial escrow deposit are all excluded from this monthly-payment-focused estimate.
- Rate locks, points, and lender credits. The interest rate entered is treated as the effective note rate; discount points or lender credits that change the rate are not separately modeled.
Common Pitfalls
- Using the statewide average tax rate as a firm quote. County-level rates in West Virginia can differ meaningfully from the 0.52% statewide figure; always confirm with the county assessor before finalizing a budget.
- Forgetting PMI on low-down-payment scenarios. Dropping below 20% down changes the real-world monthly cost in a way this calculator's flat insurance line does not capture.
- Comparing 30-year and 15-year loans by monthly payment alone. A shorter term carries a higher monthly payment but dramatically lower total interest; the two are not directly comparable on payment size alone.
- Ignoring escrow cushion requirements. Lenders often require an upfront escrow deposit at closing beyond the ongoing monthly tax and insurance contributions modeled here.
- Treating the insurance estimate as a real quote. $125 a month is a placeholder; actual premiums depend heavily on the home's age, construction, claims history of the area, and coverage limits chosen.
Frequently Asked Questions
Why is West Virginia's property tax rate so low?
Does this calculator include PMI?
How accurate is the $125 insurance estimate?
What happens if I increase the home price by 25%?
Is the interest rate on this calculator guaranteed?
Sources
- West Virginia State Tax Department, Property Tax Division, assessment ratio and levy rate guidance. tax.wv.gov
- Consumer Financial Protection Bureau, mortgage disclosure and PITI guidance. consumerfinance.gov
Also consulted: West Virginia County Assessors' Association, local mill rate publications.