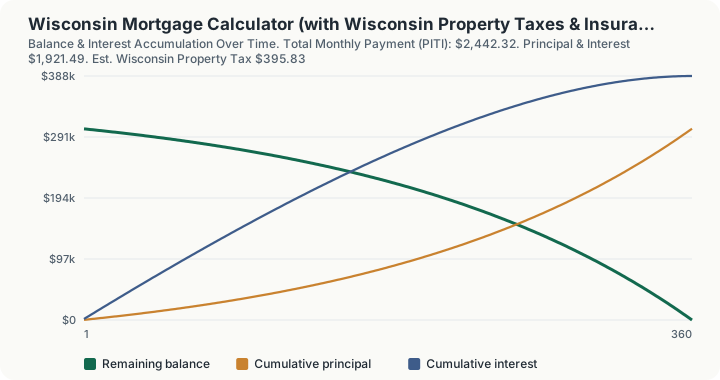
Quick Answer: On a $380,000 Wisconsin home with 20% down at 6.5% APR, the loan principal is $304,000, principal and interest run about $1,921.49 a month, and Wisconsin's above-average 1.25% effective property tax rate adds another $395.83 a month, bringing the full PITI payment to roughly $2,442.32.
Overview
Wisconsin consistently ranks among the higher property-tax states in the country, and that shows up directly in the size of a monthly mortgage payment here compared with the same loan amount in a lower-tax state. This calculator estimates a full PITI payment, principal, interest, taxes, and insurance, using a 1.25% effective property tax rate applied to the home's purchase price, plus a flat $125 monthly insurance placeholder. The loan amortization itself runs through the same 30-year fixed-rate engine used across every mortgage calculator on this site; only the tax assumption changes state to state.
Wisconsin property tax bills are set locally by municipalities, counties, and school districts based on assessed value, and the state does not cap annual increases the way some states do, which is part of why the statewide effective rate sits well above the national average. The 1.25% figure used here is a statewide average, useful for budgeting, but any specific Wisconsin municipality can run meaningfully higher or lower.
How This Is Calculated
- Determine the loan principal. Down payment cash = home price × down payment percentage. Loan principal = home price − down payment cash, floored at zero.
- Amortize over 30 years (360 months). The engine solves the standard fixed-rate mortgage payment formula:
where $P$ is the loan principal, $r$ is the monthly interest rate (APR ÷ 12), and $n = 360$.
- Estimate monthly property tax. Monthly tax = home price × 1.25% ÷ 12. Applying the rate to purchase price rather than a separately assessed value keeps the estimate consistent and easy to reproduce.
- Add a flat insurance placeholder. $125 per month is added for homeowner's insurance, independent of the tax calculation.
- Sum to PITI. Total monthly payment = principal & interest + property tax + insurance. Private mortgage insurance is not automatically added, since the baseline 20%-down scenario conventionally avoids it.
Worked Example
Using the calculator's default inputs:
- Home price: $380,000
- Down payment: 20% ($76,000)
- Interest rate: 6.5% APR
Loan principal = $380,000 − $76,000 = $304,000. Amortized over 360 months at 6.5% APR (monthly rate 0.5417%), principal and interest comes to $1,921.49 per month. Monthly property tax = $380,000 × 1.25% ÷ 12 = $395.83. Adding the $125 insurance placeholder gives total PITI of $1,921.49 + $395.83 + $125.00 = $2,442.32 per month. That property tax line alone is roughly 2.4 times larger than the equivalent estimate for a state like West Virginia at the same home price, which is a direct illustration of how much effective tax rate differences matter to monthly affordability.
Over the full 30-year term, cumulative interest on the $304,000 loan runs approximately $387,733, entirely separate from and in addition to the property tax paid over the same period, which for a Wisconsin home at this price would add up to roughly $142,000 across three decades if the rate stayed constant.
How The Escrow Line Moves With The Purchase Price
The rate step, at one eighth of a point. Holding the $380,000 price and 20% down fixed, the engine returns a principal and interest payment of $1,896.56 at 6.375%, $1,921.49 at 6.500%, $1,946.55 at 6.625% and $2,022.52 at 7.000%. One eighth of a point therefore costs about $25 a month. Over the full 360 payments the same eighth is worth far more: total interest runs $378,763.14 at 6.375%, $387,732.82 at 6.500% and $396,756.31 at 6.625%, so the step from 6.375% to 6.500% costs $8,972.09 and the next one $9,021.08. Going from 6.5% to 7.0% costs $36,371.80 of interest, which is more than the down payment difference between 20% and 25%.
The down payment step, priced against the tax line. At 20% down the Wisconsin PITI is $2,442.32. At 5% down it is $2,802.60, at 0% down $2,922.69, and at 25% down $2,322.22. The whole of that movement is principal and interest: the property tax line stays at $395.83 in every one of those four scenarios, because the engine applies the 1.25% rate to the purchase price and the purchase price does not change when the down payment does. Total interest moves from $387,732.82 at 20% down to $460,432.24 at 5% and $484,667.97 at 0%, so the fifteen points of equity between 5% and 20% are worth $72,700.34 of interest over the term.
The price step, and the only line that responds to it. Raising the price from $380,000 to $400,000 moves the Wisconsin PITI from $2,442.32 to $2,564.29 and the tax line from $395.83 to $416.67. Dropping to $300,000 gives $1,954.46 with a tax line of $312.50. At $475,000, which is the calculator's higher-price scenario, PITI is $3,021.65 with $494.79 of monthly tax. Price is the only input that moves the escrow figure at all; rate and down payment leave it untouched.
The reverse question. A buyer with a fixed monthly budget can read those anchors backwards. In Wisconsin at 6.5% with 20% down, $1,954.46 a month supports a $300,000 purchase, $2,442.32 supports $380,000, $2,564.29 supports $400,000 and $3,021.65 supports $475,000. Each additional $20,000 of purchase price costs roughly $121.97 a month at these inputs, of which $20.84 is the tax line and the rest is principal and interest.
Right method against wrong method, priced. The 5%-down scenario is the trap on this page. Moving from 20% down to 5% raises the reported PITI from $2,442.32 to $2,802.60, a difference of $360.28 a month, and a buyer comparing the two figures will conclude that is the cost of the smaller down payment. It is not. No private mortgage insurance is added anywhere in this code path, at any loan-to-value ratio, so the 5%, 0% and 20% figures are all quoted PMI-free. A real 5%-down loan carries a PMI charge on top of $2,802.60, and the engine has no input that would produce it.
What This Does Not Account For
- No private mortgage insurance is computed at any loan-to-value ratio. The 0%-down scenario returns $2,922.69 and the 20%-down scenario $2,442.32, and neither carries a PMI line. The gap between them is principal and interest only.
- The property tax line is the 1.25% effective rate applied to the purchase price, once. It is not applied to an assessed value, it is never reassessed, and it is held constant for all 360 months. The figure is $395.83 a month in month one and $395.83 a month in month 360.
- The $125 monthly insurance figure is a flat placeholder, not a quote. It does not vary with price, location or coverage, so it is identical at the $300,000 and $475,000 scenarios.
- The term is fixed at 360 months and the rate at a single APR. No 15-year option, no adjustable rate and no extra-payment input exists on this page, so every total-interest figure above assumes the loan runs to term unchanged.
- Municipal and school district variation. Wisconsin's 1.25% figure is a statewide average; specific municipalities and school districts can carry meaningfully higher or lower effective rates.
- Private mortgage insurance (PMI). The 5%-down scenario in real life would typically add a PMI charge, which this calculator does not automatically layer in.
- Lottery and gaming property tax credit. Wisconsin offers a statewide credit that reduces net property tax for qualifying primary residences; this calculator does not net that credit against the estimated tax figure.
- Special assessments and TIF district effects. Local infrastructure assessments or tax-increment financing district effects on a specific parcel are not modeled.
- Closing costs and prepaid escrow deposits. Origination fees, title costs, and the upfront escrow cushion required at closing are excluded from this ongoing monthly estimate.
Common Pitfalls
- Budgeting off the statewide average alone. Because Wisconsin property tax varies significantly by municipality, always confirm the actual mill rate for the specific property before finalizing a purchase budget.
- Forgetting the lottery and gaming credit. Many Wisconsin primary-residence owners receive a modest annual credit against property tax; failing to account for it means slightly overestimating the net tax burden.
- Ignoring PMI on low-down-payment purchases. Dropping below 20% down in the real world adds a cost this calculator's flat insurance line does not include.
- Comparing Wisconsin's total payment to a low-tax state without adjusting for the tax difference. A higher sticker payment in Wisconsin does not necessarily mean a worse deal; overall affordability depends on income, home value appreciation, and total cost of ownership together.
- Underestimating how much property tax compounds over a 30-year hold. Even a fixed-rate mortgage has principal and interest that stay level, but property tax is reassessed periodically and can rise over time, unlike the P&I portion of the payment.
Frequently Asked Questions
Why is Wisconsin's property tax rate used here so much higher than neighboring states?
Does this calculator subtract Wisconsin's lottery and gaming credit?
What if I put down less than 20%?
Is $125 a realistic homeowner's insurance estimate for Wisconsin?
How much does the higher property tax rate cost over the life of the loan?
Sources
- Wisconsin Department of Revenue, Division of State and Local Finance, property tax statistics. revenue.wi.gov
- Consumer Financial Protection Bureau, mortgage disclosure and PITI guidance. consumerfinance.gov
- Consumer Financial Protection Bureau, Buying a house. consumerfinance.gov/owning-a-home
Also consulted: Wisconsin Department of Revenue, Lottery and Gaming Credit program guidance.