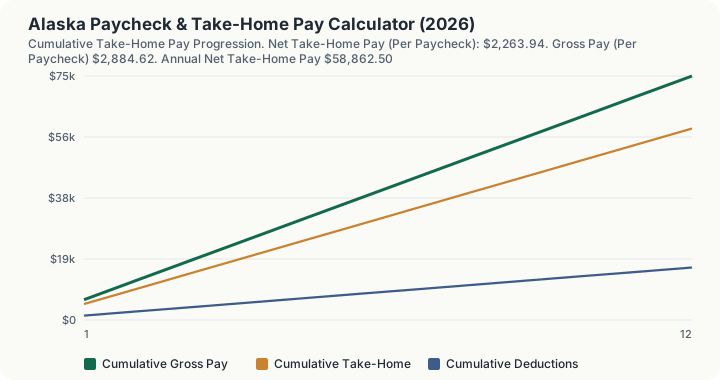
Quick Answer: A $75,000 annual salary in Alaska, paid bi-weekly and filing single, takes home about $2,263.94 per paycheck ($58,862.50 per year) after federal tax and FICA, since Alaska has no state income tax.
How This Is Calculated
Alaska is one of nine states that does not tax wage income, and it goes further than most: there are no borough or city income taxes either, so the state withholding line on an Alaska stub is blank rather than small. What comes out of an Alaska paycheck is federal withholding, FICA, and whatever benefits an employee elected. That leaves a short subtraction:
With no state layer to compute, three of these four steps do the work:
- FICA Payroll Tax Computation: Assessed on the full gross salary, before any pre-tax deduction is subtracted. - Social Security (OASDI): 6.20% withheld on wages up to the 2026 statutory wage base ($184,500). - Medicare (HI): 1.45% withheld on all gross earnings (no wage cap), plus 0.90% Additional Medicare Tax on earnings exceeding $200,000 (single) or $250,000 (married filing jointly).
- Federal Income Tax Withholding: Evaluated using 2026 progressive federal tax brackets (10%, 12%, 22%, 24%, 32%, 35%, 37%) on gross salary less the pre-tax deduction, after applying standard deduction thresholds ($16,100 single / $32,200 married joint).
- Alaska State Income Tax Withholding: None. Alaska's entry in the state table carries an empty bracket array, so the state line evaluates to $0.00 at every salary this calculator accepts.
- Pay Period Proration: Annual net compensation is divided across the designated pay frequency (26 bi-weekly, 24 semi-monthly, 12 monthly, or 52 weekly pay periods).
Worked Example
Consider an employee in Alaska earning $75,000 annually, paid bi-weekly (26 paychecks per year), filing single, with $3,500 in annual pre-tax 401(k) contributions.
- Gross pay per paycheck. $75,000 ÷ 26 pay periods = $2,884.62 before any withholding.
- Pre-tax deduction. The $3,500 annual 401(k) contribution reduces each paycheck by $134.62 and also shrinks the wages used to calculate federal income tax; FICA is still assessed on the full gross amount.
- FICA payroll taxes. Social Security withholds 6.2% of gross pay and Medicare withholds 1.45%, for $220.67 per paycheck.
- Federal income tax withholding. Applying the 2026 federal schedule to the reduced taxable wage withholds $265.38 per paycheck.
- State tax withholding. Alaska levies no state income tax, so $0.00 is withheld from each paycheck.
- Net take-home pay. $2,884.62 gross, minus $134.62 pre-tax, minus $220.67 FICA, minus $265.38 federal tax, minus $0.00 state tax leaves $2,263.94 per paycheck, which works out to $58,862.50 per year, an effective total tax rate of 16.85%.
Two Months In, And Then The Whole Year
With no state income tax and no state withholding line to accumulate, Alaska's schedule is a pure federal-plus-FICA accumulation, and it is worth watching precisely because there is nothing else in it.
Step 7 -- Two months of cumulative pay. The schedule's first row shows $6,250.00 of cumulative gross against $4,905.21 of cumulative take-home. Row two doubles both: $12,500.00 gross, $9,810.42 take-home, with $2,689.58 accumulated on the deduction side.
Step 8 -- The full year. By month twelve the schedule reaches $75,000.00 of cumulative gross and $58,862.50 of cumulative take-home, adding $4,905.21 every month without variation.
Step 9 -- What the year actually withheld. The cumulative deduction column closes at $16,137.50. That column carries the $3,500 pre-tax 401(k) contribution alongside the tax, so tax alone is $16,137.50 - $3,500 = $12,637.50, an effective total tax rate of 16.85% on $75,000.00 of gross pay.
Step 10 -- Why the monthly increment never changes. The twelve rows rise in identical increments, which is worth naming rather than assuming. FICA is computed once on the full annual wage -- Social Security capped at $184,500, Additional Medicare charged above $200,000 for a single filer -- and the annual figure is then spread evenly across the months. So the mid-year jump in take-home that a high earner sees on a real pay stub never appears here. At $75,000 nothing crosses either threshold anyway; it would take $184,500 to reach the first and $200,000 to reach the second.
What A Blank State Line Is Worth, Measured
Almost every other page in this series has three moving parts. Alaska has two, and that is not a rhetorical point: the state figure this engine returns is $0.00 at $30,000 of salary, $0.00 at $75,000, $0.00 at $150,000 and $0.00 at $300,000. Every dollar of the spread between an Alaska paycheck and any other state's is federal withholding and FICA, so every edge on this page belongs to Washington.
That also removes a lever. In a graduated-rate state, a pre-tax contribution buys relief in two schedules at once. Here it buys relief in one, and the numbers below show exactly how much smaller that makes the return.
The federal edge that lands at $70,000 of gross salary
With the default $3,500 pre-tax deduction and the $16,100 single standard deduction, the federal 12% band runs out at exactly $70,000 of gross salary. The sweep walks it.
At $69,000 of salary. Take-home is $2,097.75 per bi-weekly check on federal withholding of $218.46. Annual net is $54,541.50.
At $70,000, at the boundary. Take-home is $2,128.65 per check, federal withholding $223.08, annual net $55,345.00. That thousand added $803.50 to the year.
At $71,000, past it. Take-home is $2,155.71 per check, federal withholding $231.54, annual net $56,048.50. The identical thousand now adds $703.50.
The edge costs $100.00 of annual take-home on an identical raise. In Alaska that is the whole of the step, with no state bracket contributing anything either side of it.
The Social Security wage base at $184,500
The one place on this page where the next dollar gets cheaper rather than dearer.
At $184,000 of salary, annual net take-home is $134,370.00, FICA $541.38 per check.
At $185,000, annual net is $135,084.50, FICA $543.13 per check. That thousand was worth $714.50.
At $186,000, wholly above the base, annual net is $135,830.00 and FICA per check is $543.69. That thousand was worth $745.50 -- $31.00 more than the one immediately below it, because Social Security's 6.2% has stopped and only the 1.45% Medicare line continues.
The schedule shows none of this. At $186,000 its twelve rows still climb by one constant increment, because FICA was resolved annually before the division by twelve. The step is real, it is in the salary sweep, and it is invisible in the table by construction.
The marginal cost of the next $1,000
Annual net take-home runs $58,159.00 at $74,000 of salary, $58,862.50 at $75,000 and $59,566.00 at $76,000. Each additional $1,000 of salary is worth $703.50 of annual take-home in Alaska, and costs $296.50 in federal tax and FICA. That is the highest retention of the seven states in this batch's default sweep, and all of the advantage sits in the $0.00 state line.
Running the calculator backwards
Sweeping the salary axis in $500 steps at the default settings, $102,500 is the first salary at which the bi-weekly check reaches $3,000, paying $3,008.03 where $102,000 pays $2,994.50. And $134,000 is the first salary whose annual net take-home clears $100,000, at $100,195.00 against $99,853.25 at $133,500.
The pre-tax dollar, priced in a no-state-tax state
At $3,500 of pre-tax deductions, annual net take-home is $58,862.50, federal withholding $265.38 per check.
At $10,000, annual net take-home is $53,642.50, federal withholding $216.15 per check.
Contributions rose $6,500.00 while spendable take-home fell only $5,220.00. The $1,280.00 difference is federal tax that was never withheld -- and in Alaska that is the entire subsidy, because there is no state schedule underneath it to add a second layer of relief.
The Total Effective Tax Rate output moves in the opposite direction over the same range, reading 16.85% at $3,500 and 15.14% at $10,000, since the contribution is excluded from that ratio's numerator. The schedule's Cumulative Deductions column counts the same contribution as a deduction. Both outputs are on this page and they measure different things.
Common Pitfalls
Annualising the paycheck instead of reading the annual output. Twenty-six times $2,263.94 is $58,862.44, six cents under the engine's $58,862.50. Switch to monthly and the drift reverses: $4,905.21 per check, twelve of them making $58,862.52. The annual figure is computed first and every paycheck is derived from it, which is also why annual net is identical at $58,862.50 whether you select weekly ($1,131.97), bi-weekly ($2,263.94), semi-monthly ($2,452.60) or monthly ($4,905.21).
Reading Cumulative Deductions as a tax total. The column closes at $16,137.50 against $12,637.50 of actual tax. Quoted as tax it reads 21.52% of a $75,000 gross where the true figure is 16.85%, overstating the burden by 4.67 percentage points -- and in a state whose entire appeal is the size of that number.
Assuming no state tax means no filing-status effect. It does not. At $75,000 the state line is $0.00 either way, but married filing jointly cuts federal withholding from $265.38 to $162.31 per check and lifts annual net from $58,862.50 to $61,542.50.
What This Does Not Account For
- No state income tax exists to model, and none is modelled. Alaska's bracket array is empty; the engine returns $0.00 rather than computing anything. It also does not model the Permanent Fund Dividend, which is federally taxable income and is not an input here.
- No local wage taxes. Alaska boroughs and cities levy none on wages, and none are modelled.
- No W-4 detail. No dependents, no multiple-jobs checkbox, no extra per-period withholding, no other-income entry. Filing status is single or married filing jointly and nothing else.
- One pre-tax box, no post-tax box. 401(k), HSA and FSA contributions share one annual field with no employer match and no per-plan limit. Roth contributions, garnishments and post-tax premiums are absent.
- FICA is annual, then prorated. The twelve schedule rows never show the wage-base step, at any salary, for the reason given in Step 10.
- Two definitions on one page. The effective rate output excludes the pre-tax deduction from its numerator; the Cumulative Deductions column includes it. The gap between them is exactly the contribution.
Frequently Asked Questions
Does Alaska have a state income tax on paychecks?
What does a raise actually add in Alaska?
What is the Social Security wage cap for 2026?
Can I adjust my state tax withholding in Alaska?
Sources
- Internal Revenue Service (IRS): Publication 15 (Circular E) and Publication 15-T (2026). irs.gov/publications/p15
- Social Security Administration (SSA): 2026 Social Security Wage Base Limit. ssa.gov
- Alaska Department of Revenue, the official state tax authority for Alaska rates, rules and forms. tax.alaska.gov
Also consulted: Alaska: no state Employer Withholding Tax Tables exist to cite, since the state levies no personal income tax.