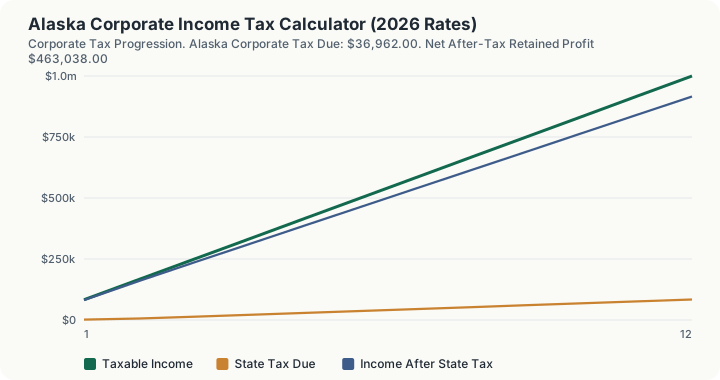
Quick Answer: On $500,000 of pre-apportioned taxable income, Alaska's graduated corporate income tax brackets (reaching 9.40% at this income level) produce $36,962.00 in state tax due and $463,038.00 in net after-tax profit.
Ten Brackets, and Where They Actually Bite
Alaska is a graduated-rate state, but its bracket structure is unlike anything else in this dataset: ten separate income tiers climb from 0% on the first $25,000 of apportioned income all the way to a 9.40% top rate above $222,000, in roughly $25,000 increments. No other state that taxes corporate income spreads its schedule across that many steps.
That top rate of 9.40% is also among the highest in the nation: third-highest of any state in this dataset, behind only Minnesota's 9.80% and Illinois's 9.50%. For a corporation with only modest Alaska-sourced income, the low starting brackets matter; for a company with hundreds of thousands of dollars apportioned to the state, the effective rate climbs quickly toward that 9.40% ceiling, and multi-entity structuring should account for exactly where a projected income figure lands within Alaska's ten tiers.
Even after stepping through all ten brackets, a $500,000 filer's effective rate lands at just 7.39%, noticeably below the 9.40% top bracket, since Alaska's zero-rate opening tier and gradual climb shelter a meaningful share of income from the top rate. That gap between marginal and effective rate narrows steadily as apportioned income grows well past $222,000.
How This Is Calculated
Alaska runs the most granular corporate rate schedule in the country: ten brackets climbing from a zero-rate first tier to a 9.40% top rate, one of the highest state corporate rates anywhere. Because the schedule steps up in narrow increments below $222,000, a small Alaska filer pays an effective rate far under the headline, while a large one converges on 9.40%. At $500,000 of apportioned income the calculator returns $36,962.00, an effective rate of 7.39%, not 9.40%.
where $c_i$ are the bracket ceilings ($25{,}000$ through $222{,}000$ in ten steps) and $r_i$ the corresponding rates ($0\%$ rising to $9.40\%$).
The engine runs three steps and stops. Everything else on an Alaska return happens before the figure reaches this box.
- Take the income figure as entered. No apportionment formula runs here, three-factor or otherwise, and there is no separate oil and gas computation, no addition or subtraction schedule, no nexus test and no NOL carryforward. The number you type is treated as final Alaska taxable income.
- Walk the ten brackets. Each slice of income is multiplied by the rate for its own tier and the pieces are added: 0% on the first $25,000, then 2%, 3%, 4%, 5%, 6%, 7%, 8% and 9% through the tiers ending at $49,000, $74,000, $99,000, $124,000, $148,000, $173,000, $198,000 and $222,000, and 9.40% on everything above $222,000. At $500,000 the pieces total $36,962.00.
- Subtract credits, floor at zero, and report. Credits come off the bracket total. The effective rate is the tax after credits divided by the income entered, so the baseline reports 7.39% while the marginal rate, reported before credits, reads 9.40%. Net retained profit is $463,038.00.
Worked Example
Using this calculator's baseline scenario: a corporation with $500,000 in taxable income apportioned to Alaska.
- Start with apportioned taxable income. The corporation has $500,000 of taxable income apportioned to Alaska before state tax is applied.
- Work through Alaska's bracket schedule. Alaska taxes corporate income progressively: each slice of income is taxed only at the rate for its own bracket rather than the entire amount being taxed at the top rate, so lower brackets are filled first and the marginal rate rises step by step as income climbs.
- Marginal rate reached at this income level. At $500,000 of taxable income, the highest bracket reached is 9.40%.
- Sum the marginal brackets. Adding together the tax owed within every bracket the $500,000 passes through produces a total Alaska state tax liability of $36,962.00.
- Net retained profit. $500,000 − $36,962.00 = $463,038.00 retained after state tax, before any separate federal tax liability.
Because the calculation sums each bracket's marginal tax rather than applying one flat rate to the whole amount, the resulting effective rate (7.39%) is always lower than the top marginal bracket actually touched.
The $25,000 Cliff, and the Nine Steps Above It
Alaska's zero-rate opening tier is the sharpest edge on this page, and it is worth pricing to the cent. Every figure below is a separate run of the calculator.
At $24,999 of taxable income. Alaska tax = $0.00, effective rate 0.00%, marginal rate 0.00%.
At $25,000, the top of the zero band. Alaska tax = $0.00. Still nothing.
At $25,001, one dollar later. Alaska tax = $0.02, and the reported marginal rate flips from 0.00% to 2.00%. That single dollar is the moment Alaska starts charging at all.
At $26,000. Alaska tax = $20.00, an effective rate of 0.08% against a 2.00% marginal rate. A thousand dollars past the cliff the bill is still trivial, which is the point of the tier.
The nine steps above run in narrow increments and the calculator prices each one. $49,000 of income returns $480.00 at a 2.00% marginal rate; $74,000 returns $1,230.00 at 3.00%; $99,000 returns $2,230.00 at 4.00%; $124,000 returns $3,480.00 at 5.00%; $148,000 returns $4,920.00 at 6.00%; $173,000 returns $6,670.00 at 7.00%; $198,000 returns $8,670.00 at 8.00%.
The last edge is the one that matters most. At $222,000 the tax is $10,830.00 and the marginal rate reads 9.00%. At $222,001 the tax is $10,830.09 and the marginal rate reads 9.40%. That is the top of the schedule; there is no further step at any income above it. A $5,000,000 filer returns $459,962.00, an effective rate of 9.20%, still short of the 9.40% ceiling because the tiers below $222,000 never stop sheltering their $10,830.00 worth of cheaper income.
Marginal Cost, and How Much Can Be Earned Tax Free
Above $222,000, each additional $1,000 of Alaska taxable income costs $94.00. The proof pair: $499,000 of income returns $36,868.00 and $500,000 returns $36,962.00. It holds going up as well, with $501,000 returning $37,056.00, and it stays constant however large the base gets.
The reverse question has an exact answer: $25,000. That is the most a corporation can apportion to Alaska and still owe nothing, and the engine confirms it at $24,999 and $25,000, both $0.00. The next useful figure is the value of the graduated tiers as a block. A filer at $250,000 pays $13,462.00, an effective rate of 5.38% rather than 9.40%; the gap is the cumulative discount from the ten tiers, and it is worth $10,830.00 at any income above $222,000, since that is the total charged on everything below the top bracket.
The twelve-row schedule makes the convergence visible. Tax runs $1,603.33 on $83,333.33 of income (an effective rate well under 2%), $13,462.00 at $250,000.00, $36,962.00 at $500,000.00 and $83,962.00 at $1,000,000.00. The first row's tax is not one twelfth of the last row's; it is closer to one fifty-second, because the low tiers absorb most of a small filer's income.
What the Credits Field Does, and Where It Loses Money
Credits are subtracted from the bracket total and the answer is floored at zero. On the $500,000 baseline, $10,000 of credits produces $26,962.00 and drops the effective rate from 7.39% to 5.39%, while the marginal rate still reports 9.40% because it is computed before credits.
Push the credits higher and the field stops paying. $50,000 of credits returns $0.00. $1,000,000 of credits also returns $0.00. Between those two runs, $950,000 of credit value disappears without trace: the engine treats credits as a non-refundable, non-carryforward offset, so any credit larger than the computed tax is worth exactly what a credit equal to the tax is worth. The twelve-row table ignores the credit input altogether and always shows the pre-credit bracket walk.
What This Does Not Account For
- Federal corporate income tax (21% under IRC § 11).
- Specialized gross receipts taxes (e.g. Ohio CAT, Washington B&O, Texas Franchise Tax) where applicable.
- Minimum entity franchise tax fees or annual report filing charges.
- Base Erosion and Anti-Abuse Tax (BEAT) or Global Intangible Low-Taxed Income (GILTI) provisions.
- Local municipal corporate earnings taxes (e.g. NYC General Corporation Tax).
- Everything that produces the base. No apportionment (three-factor or otherwise), no separate oil and gas formula, no nexus or P.L. 86-272 test, no state modifications and no NOL carryforward are computed here.
- Credit carryforward and refundability. $50,000 and $1,000,000 of credits both return $0.00 on the $500,000 baseline; unused credit is discarded rather than carried.
Common Pitfalls
- Applying the Top Bracket to the Whole Amount: Treating Alaska's 9.40% top rate as a flat rate rather than working through all ten brackets, which understates how much of a $500,000 filer's income is actually taxed at 0% and the lower tiers.
- Improper Apportionment Sourcing: Applying market-based sourcing vs cost-of-performance rules incorrectly for service revenue, which shifts income between brackets rather than just changing a flat total.
- Ignoring Unitary Group Combined Reporting: Failing to account for Alaska's mandatory combined return requirements across related entities.
- Neglecting State NOL Carryforward Caps: Overlooking Alaska's annual percentage limitations on net operating loss deductions, which matter more with a ten-bracket schedule where each dollar sheltered can fall in a lower tier.
Frequently Asked Questions
Does Alaska have a corporate income tax?
When are Alaska corporate tax returns due?
Does Alaska tax S-corporations and LLCs?
How is multi-state corporate income apportioned to Alaska?
Sources
- Alaska Department of Revenue: Corporate Tax Statutes and Guidance (2026). tax.alaska.gov
- Multistate Tax Commission (MTC): Uniform Apportionment and Allocation Guidelines. mtc.gov