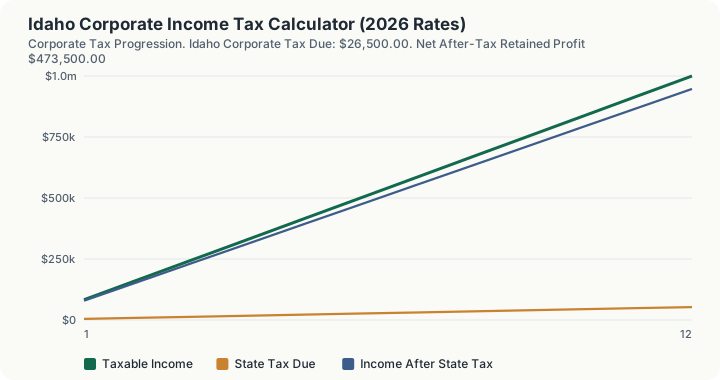
Quick Answer: On $500,000 of pre-apportioned taxable income, Idaho's flat 5.30% corporate income tax rate produces $26,500.00 in state tax due and $473,500.00 in net after-tax profit.
Idaho's 5.30% After Successive Cuts
5.30%: Idaho taxes C-corporation income at a single flat rate, the product of a series of statutory rate reductions that have stepped the figure down over the past several years rather than resetting it in one move.
That rate places Idaho below the national middle for states that tax corporate income, lower than neighboring Montana's 6.75% but higher than Utah's 4.45%. As a flat-rate state, Idaho applies 5.30% uniformly to all apportioned C-corporation income with no bracket thresholds, so the marginal and effective rates are identical regardless of how large a filer's Idaho-sourced income becomes.
Idaho's 5.30% rate produces $26,500.00 in state tax on the calculator's $500,000 example. The same income apportioned to Montana instead would draw $33,750.00 at that state's 6.75% rate, a gap of $7,250.00 on an identical base.
How This Is Calculated
Idaho charges a flat 5.30% and attaches a $20 minimum tax to every corporate return, so a loss year in Idaho still produces a filing and a payment. This calculator implements the 5.30% and not the minimum: it floors the answer at $0.00, so at zero income it returns $0.00 where Idaho returns $20. The rate has also been cut repeatedly in recent sessions, and this page holds a single stored 2026 figure, which makes it unsuitable for reconstructing a prior year.
- The entered income is the base. The engine performs no apportionment, no double-weighted sales factor, and no net operating loss deduction. The figure you type is taxed as-is.
- Apply 5.30% flat. Idaho's stored schedule holds a single open-ended bracket.
- Subtract credits and floor at zero. Note what the floor is: zero, not $20. Idaho's statutory $20 minimum corporate tax is not implemented in this code path, so a zero-income Idaho corporation returns $0.00 here where the state would still charge $20.
- Effective rate. Net tax over entered income.
- Net retained profit. Entered income minus net tax.
- Twelve tiers. The same flat multiplication is run at incomes from one sixth of your figure to twice it.
Worked Example
Using this calculator's baseline scenario: a corporation with $500,000 in taxable income apportioned to Idaho.
- Start with apportioned taxable income. The corporation has already apportioned $500,000 of its total taxable income to Idaho using the state's statutory apportionment formula, before any state-level tax is applied.
- Apply Idaho's flat statutory rate. Idaho taxes all C-corporation income at a single flat rate of 5.30%, regardless of income size, so no bracket lookup is required: $500,000 × 5.30% = $26,500.00.
- Idaho corporate tax due: $26,500.00.
- Net retained profit. Subtracting the state tax liability from taxable income leaves $500,000 − $26,500.00 = $473,500.00 in after-tax profit retained by the corporation, before any separate federal tax liability is applied.
Because Idaho uses a single flat rate rather than graduated brackets, the 5.30% effective rate is identical to the marginal rate at every income level: a corporation earning $50,000 and one earning $50 million both face the same 5.30% state rate on their apportioned income.
Idaho's Flat Line and the Twenty Dollars That Are Not There
Idaho's stored schedule is a single open bracket at 5.30%, so the twelve rows above rise in a straight line with the effective rate reading 5.30% at each one.
Two rungs. Row 3 sets income at $250,000.00 and returns $13,250.00. Row 6, the $500,000 baseline, returns $26,500.00. Row 12 is $1,000,000.00 at $53,000.00. Nothing on that ladder steps, so there is no bracket edge to walk and no exemption cliff to price.
The marginal figure. Each additional $1,000 of Idaho apportioned income costs $53.00. The engine returns $26,553.00 at $501,000 against $26,500.00 at $500,000.
The reverse question. A company capping Idaho tax at $25,000 can carry $471,698.11 of apportioned income, where the engine returns exactly $25,000.00 and $446,698.11 of retained profit.
Credit against deduction, priced. A $25,000 Idaho credit, the investment tax credit being the common one, takes the liability from $26,500.00 to $1,500.00 and saves the whole $25,000.00. Cutting $25,000 from the base instead returns $25,175.00, a $1,325.00 saving. The credit outperforms the deduction by $23,675.00, a ratio of 18.9 to 1.
At the small end of the sweep. Row 1 sets income at $83,333.33 and returns $4,416.67. At $100,000 the engine returns $5,300.00 and at $25,000 it returns $1,325.00, both at a 5.30% effective rate, because one open bracket taxes the first dollar of profit exactly as it taxes the last.
The floor is zero, and Idaho's is not. Enter zero income, or credits larger than the tax, and this calculator returns $0.00. Idaho charges a $20 minimum tax on every corporate return from a corporation transacting business in the state, including loss years. That minimum is not implemented anywhere in this code path, so every Idaho figure this page produces below $20 is understated by the difference, and a loss year reads as no filing obligation when it is in fact both a filing and a payment.
The other omissions. No apportionment is performed, so the double-weighted sales factor that pulls Idaho property and payroll into the base has to be applied before you type the number in. No net operating loss carryforward, no add-back of Idaho tax deducted federally, and no interest adjustment on other states' obligations is computed here.
What This Does Not Account For
- Federal corporate income tax (21% under IRC § 11).
- Specialized gross receipts taxes (e.g. Ohio CAT, Washington B&O, Texas Franchise Tax) where applicable.
- Minimum entity franchise tax fees or annual report filing charges.
- Base Erosion and Anti-Abuse Tax (BEAT) or Global Intangible Low-Taxed Income (GILTI) provisions.
- Local municipal corporate earnings taxes (e.g. NYC General Corporation Tax).
Common Pitfalls
- Mistaking the Flat Rate for the Final Bill: Assuming Idaho's 5.30% rate applies directly to book income rather than to apportioned taxable income after state additions, subtractions, and NOL adjustments.
- Improper Apportionment Sourcing: Applying market-based sourcing vs cost-of-performance rules incorrectly for service revenue apportioned to Idaho.
- Ignoring Unitary Group Combined Reporting: Failing to account for Idaho's mandatory combined return requirements across related entities.
- Neglecting State NOL Carryforward Caps: Overlooking Idaho's annual percentage limitations on net operating loss deductions, which matter more once the 5.30% rate is applied to a larger taxable base.
Frequently Asked Questions
Does Idaho have a corporate income tax?
When are Idaho corporate tax returns due?
Does Idaho tax S-corporations and LLCs?
How is multi-state corporate income apportioned to Idaho?
Sources
- Idaho State Tax Commission: Corporate Tax Statutes and Guidance (2026). tax.idaho.gov
- Multistate Tax Commission (MTC): Uniform Apportionment and Allocation Guidelines. mtc.gov