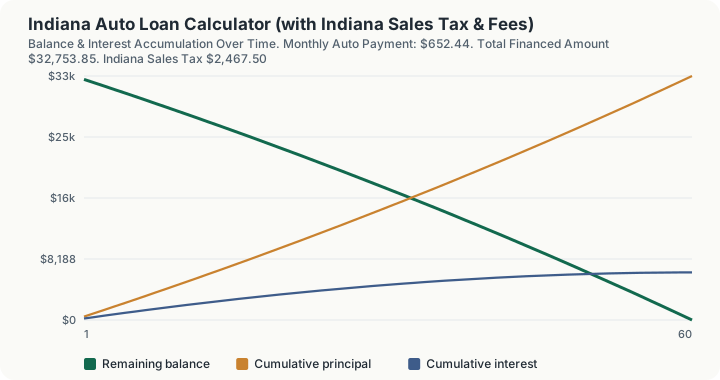
Quick Answer: A $35,000 vehicle in Indiana with $5,000 cash down, a $250 dealer documentation fee, a 60-month term, and a 7.25% APR carries a $652.44 monthly payment. That figure includes $2,467.50 of Indiana sales tax at the flat 7% rate and $36.35 in title and registration fees, financing $32,753.85 in total.
Overview
Indiana has no local option sales tax. Not a county rate, not a city rate, not a transit district rate. IC 6-2.5-2-2 sets a single 7% state gross retail tax and that is the entire sales tax picture, in Indianapolis and in the smallest town in the state. For a car buyer this makes the purchase side of the arithmetic unusually clean: one rate, applied to one base, with an uncapped trade-in credit subtracted first.
The cost of that simplicity shows up after you drive away. Indiana runs an annual motor vehicle excise tax at registration renewal, calculated from the vehicle's value and age, and most counties layer an excise surtax and a wheel tax on top. That recurring bill is where county-to-county variation actually lives in Indiana, and it is not part of what you finance. This calculator covers the purchase; the excise tax is described below but deliberately excluded from the totals.
At 7%, Indiana's rate is the joint-highest state sales tax in the country. That cuts both ways. It makes the trade-in credit worth more per dollar here than in most states: every $1,000 of trade-in allowance takes $70 off the tax bill, with no cap and no local rate diluting it.
Auto Loan APR by Credit Score
The APR columns below are national averages, not Indiana figures. No primary source publishes average auto loan APR by state: Experian's report has no geographic cut, the CFPB publishes state origination volume but no rates, and the New York Fed publishes state delinquency only. The payment column is the part that is specific to Indiana, because it runs this calculator's own Indiana tax and fee rules at each tier's rate.
| Credit Tier | VantageScore 4.0 | Avg New APR | Avg Used APR | Est. Payment in Indiana |
|---|---|---|---|---|
| Super prime | 781-850 | 4.55% | 6.30% | $611.38 |
| Prime | 661-780 | 6.23% | 8.77% | $636.73 |
| Nonprime | 601-660 | 9.67% | 14.03% | $690.62 |
| Subprime | 501-600 | 13.44% | 19.42% | $752.65 |
| Deep subprime | 300-500 | 16.01% | 21.77% | $796.68 |
Payment assumptions: $35,000 vehicle price, $0 trade-in, $5,000 cash down, $250 dealer documentation fee, 60-month term, new-vehicle APR applied to the Indiana delivered price including tax and statutory fees. At the 6.39% overall new-car average the same purchase costs $639.18 a month.
The score bands are VantageScore 4.0, not FICO. The same borrower can land in a different tier under each model, so a FICO score pulled from a card issuer will not always match the band here. Source: Experian, State of the Automotive Finance Market, Q1 2026, slide 45.
What Moves Your Payment
Each row changes one input and leaves the rest at the baseline below. The dollar effects are this calculator's own output for Indiana, not a rule of thumb.
| Factor | What Changes | Effect on Monthly Payment | Effect on Total Interest |
|---|---|---|---|
| Vehicle Price | Each extra $1,000 of price raises both the amount financed and the sales tax base, so the tax rises with it. | +$21.31 | +$208.82 |
| Trade-In Allowance | A $1,000 allowance cuts the amount financed by $1,000 and reduces the sales tax base by the same amount, so it saves tax as well as principal. | -$21.32 | -$208.83 |
| Cash Down Payment | A $1,000 larger down payment cuts the amount financed by $1,000. It never reduces the sales tax, which is assessed on the price, not on what you borrow. | -$19.92 | -$195.17 |
| Dealer Doc Fee | A $100 higher documentation fee adds $100 to the amount financed and is inside the sales tax base, so it is taxed on top of itself. | +$2.13 | +$20.88 |
| Longer Term | Stretching the same balance from 60 months to 72 months spreads the principal over twelve more payments at the same rate. | -$90.08 | +$1,343.83 |
Baseline: $35,000 vehicle price, $0 trade-in, $5,000 cash down, $250 documentation fee, 60 months at 7.25% APR, giving a $652.44 payment and $6,392.28 of total interest.
How This Is Calculated
Indiana is the simplest state in this family: one 7% rate everywhere, a full trade-in credit, no local add-on. Four steps.
1. Net taxable amount. IC 6-2.5-1-5 defines gross retail income as the consideration the dealer receives, which includes a document preparation charge. The trade-in allowance is then subtracted under IC 6-2.5-1-5(b).
The credit has one condition worth knowing: the trade must be a like-kind vehicle that you own and hold title to. Trading in a boat, a trailer that is not a vehicle, or other personal property against a car does not reduce the taxable amount.
2. Sales tax. One rate, no local component:
3. Title and registration. A fixed $36.35, being the $15 certificate of title and the $21.35 flat passenger registration fee. Separately stated, neither is taxable.
4. Amortization. The financed balance is the delivered price less the trade-in and the cash down, amortized as a fixed-rate installment loan:
where $P$ is the financed amount, $i$ is the monthly rate (APR ÷ 12), and $n$ is the term in months. Each period's interest is the outstanding balance times $i$, the remainder reduces principal, and the schedule reconciles to zero at maturity.
There is no metro rate table on this page because there are no metro rates. Indianapolis, Fort Wayne, Evansville, South Bend, and Bloomington are all 7%.
Worked Example
Indiana is one of the simplest states to model: a flat 7% with no county vehicle add-on, an uncapped like-kind trade-in credit, and a doc fee that sits inside the base.
- Vehicle price: $35,000
- Trade-in allowance: $0
- Cash down: $5,000
- Dealer doc fee: $250
- Term: 60 months at 7.25% APR
Step 1 -- The taxable amount. Gross retail income including the doc fee, less any trade-in: $35,000 + $250 - $0 = $35,250.00
Step 2 -- Indiana sales tax at 7%. $35,250.00 x 7% = $2,467.50
Step 3 -- Title and registration, outside the base. $15.00 title + $21.35 registration = $36.35
Step 4 -- Total delivered price. $35,000 + $250.00 + $2,467.50 + $36.35 = $37,753.85
Step 5 -- Amount financed. $37,753.85 - $0 trade-in - $5,000 cash down = $32,753.85
Step 6 -- The monthly payment. $32,753.85 at 7.25% over 60 months = $652.44
Step 7 -- Month 1. $32,753.85 x (7.25% / 12) = $197.89 interest, $454.55 principal, balance $32,299.30
Step 8 -- Month 2. $32,299.30 x (7.25% / 12) = $195.14 interest, $457.30 principal, balance $31,842.00. Cumulative interest: $393.03
Step 9 -- The running total. Through month 12, $2,189.71 of interest paid and $27,114.28 still owed. Over 60 months, $6,392.28
Add a $10,000 trade-in and the taxable amount falls to $25,250, tax falls to $1,767.50, and the payment drops to $439.30. The trade-in saved $700 in tax on its own. That is the number a private-sale buyer has to beat: unless a private buyer pays you at least $700 more than the dealer's allowance, trading in wins on cash terms alone.
The doc fee works the same way in reverse. Negotiating $250 to zero saves $267.50 delivered, because the fee carries $17.50 of its own tax. Indiana caps nothing here, so the fee is negotiable in principle even where a dealer presents it as fixed.
What This Does Not Account For
- The annual motor vehicle excise tax. Indiana bills this every year at registration renewal, based on the vehicle's value and model year. On a newer $35,000 vehicle it is a meaningful recurring cost, and it declines as the car ages. It is not financed and is not modeled here.
- County excise surtax and wheel tax. Most Indiana counties add both on top of the state excise tax at renewal. The amounts are set locally and vary widely. They were not researched for this calculator and are excluded.
- The doc fee figure itself. $250 is a market estimate for Indiana, not a sourced statutory or survey number. Indiana has no cap, so use the figure on your dealer's buyer's order.
- Non-vehicle trade-ins. The credit requires a like-kind vehicle you own and hold title to. This calculator applies the allowance you enter without testing that condition.
- Private-party purchases. Tax on a casual sale is collected by the BMV at titling rather than by a dealer, and the trade-in mechanics are not the same.
- GAP insurance, service contracts, and aftermarket accessories, unless you fold them into the vehicle price yourself.
Common Pitfalls
- Looking up a county rate that does not exist. Buyers coming from Ohio, Illinois, or Missouri often assume a county add-on applies. In Indiana it does not. If an estimate shows a local sales tax line for an Indiana car purchase, that line is wrong.
- Confusing the county wheel tax with sales tax. The wheel tax and excise surtax are annual registration charges tied to your county of residence. They have nothing to do with the 7% you pay at purchase, and rolling them into a purchase estimate double-counts.
- Underrating the trade-in credit because Indiana's fees look small. The $36.35 in title and plate fees is among the lowest in the country and tempts buyers to stop thinking about state charges. The 7% rate is where the money is, and the trade-in credit is the only lever against it.
- Trading in property that is not a vehicle. A boat or a piece of equipment traded against a car does not reduce the taxable amount under IC 6-2.5-1-5(b).
- Rolling negative equity forward. If you owe more than the trade is worth, the shortfall is added to the new loan. It raises the principal and the total interest, and it does not increase your tax credit, which is based on the allowance rather than your equity.
- Judging the loan by payment alone. Stretching this $32,753.85 balance from 60 to 72 months drops the payment to $562.36 but raises total finance charges from $6,392.28 to $7,736.10.
Frequently Asked Questions
What is the sales tax on a car in Indiana?
Does Indianapolis or Marion County add local sales tax on a vehicle?
Does a trade-in reduce sales tax in Indiana?
Is the dealer doc fee taxable in Indiana, and is it capped?
What is Indiana's annual vehicle excise tax?
How much are Indiana title and plate fees?
Sources
- Consumer Financial Protection Bureau, Truth in Lending Act (Regulation Z, 12 CFR § 1026.22) disclosure requirements for installment credit. ecfr.gov/current/title-12/chapter-X/part-1026
Also consulted: IC 6-2.5-2-2 (state gross retail tax rate); IC 6-2.5-1-5, including subsection (b) (definition of gross retail income and the like-kind vehicle trade-in deduction); Indiana Department of Revenue, Sales Tax Information Bulletin #28S (motor vehicle and trailer sales); Indiana Bureau of Motor Vehicles fee chart (certificate of title and passenger registration fees); Indiana Bureau of Motor Vehicles, annual motor vehicle excise tax, county excise surtax and wheel tax schedules; Experian, State of the Automotive Finance Market, Q1 2026, slide 45 (average new and used auto loan APR by VantageScore 4.0 credit tier; national, no state level cut published).