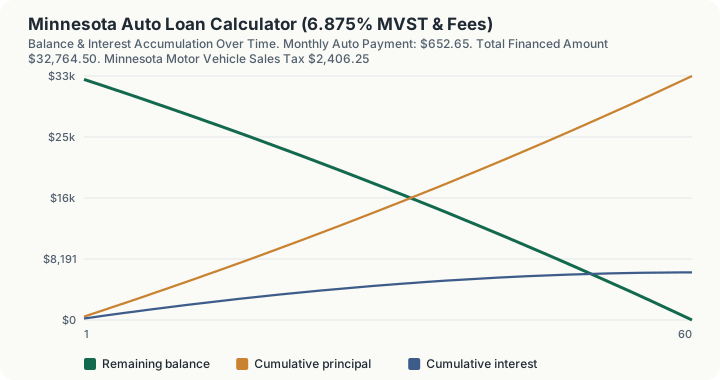
Quick Answer: A $35,000 vehicle in Minnesota with $5,000 cash down, a $350 dealer documentation fee, a 60-month term, and a 7.25% APR carries a $652.65 monthly payment. That figure includes $2,406.25 of Minnesota Motor Vehicle Sales Tax at 6.875% and the $8.25 title fee, financing $32,764.50 in total.
Overview
Minnesota does not charge general sales tax on a car. It charges a different tax that happens to use the same number. The Motor Vehicle Sales Tax sits in Minn. Stat. ch. 297B, separate from the general sales tax in ch. 297A, and that separation is the reason a Minnesota vehicle purchase is cheaper to tax than almost anything else you buy in the Twin Cities.
Here is what it means in practice. Since October 2023, a retail purchase in the seven-county metro carries the state 6.875% plus a 0.75% regional transportation sales tax, a 0.25% metro housing tax, and county and city add-ons, pushing the combined rate past 9% in Minneapolis and St. Paul. None of those percentage add-ons apply to a vehicle purchase. The MVST base is defined by ch. 297B and the metro taxes ride on ch. 297A. A Minneapolis buyer and a buyer in rural Roseau County pay the same 6.875% on the same car.
Local governments do reach vehicles, but not with a percentage. Some jurisdictions levy a flat $20 local vehicle excise tax that the dealer collects per sale, and counties levy a wheelage tax of up to $20 a year at registration. All seven metro counties levy the full $20 wheelage. These are dollar amounts, not rates, and adding a fifth of a percent to your purchase to approximate them would be wrong in both direction and magnitude.
Two other Minnesota rules matter. The trade-in credit is full and uncapped, unlike Michigan next door. And the documentation fee, capped at $350, is not subject to MVST at all.
Auto Loan APR by Credit Score
The APR columns below are national averages, not Minnesota figures. No primary source publishes average auto loan APR by state: Experian's report has no geographic cut, the CFPB publishes state origination volume but no rates, and the New York Fed publishes state delinquency only. The payment column is the part that is specific to Minnesota, because it runs this calculator's own Minnesota tax and fee rules at each tier's rate.
| Credit Tier | VantageScore 4.0 | Avg New APR | Avg Used APR | Est. Payment in Minnesota |
|---|---|---|---|---|
| Super prime | 781-850 | 4.55% | 6.30% | $611.57 |
| Prime | 661-780 | 6.23% | 8.77% | $636.94 |
| Nonprime | 601-660 | 9.67% | 14.03% | $690.84 |
| Subprime | 501-600 | 13.44% | 19.42% | $752.89 |
| Deep subprime | 300-500 | 16.01% | 21.77% | $796.94 |
Payment assumptions: $35,000 vehicle price, $0 trade-in, $5,000 cash down, $350 dealer documentation fee, 60-month term, new-vehicle APR applied to the Minnesota delivered price including tax and statutory fees. At the 6.39% overall new-car average the same purchase costs $639.39 a month.
The score bands are VantageScore 4.0, not FICO. The same borrower can land in a different tier under each model, so a FICO score pulled from a card issuer will not always match the band here. Source: Experian, State of the Automotive Finance Market, Q1 2026, slide 45.
What Moves Your Payment
Each row changes one input and leaves the rest at the baseline below. The dollar effects are this calculator's own output for Minnesota, not a rule of thumb.
| Factor | What Changes | Effect on Monthly Payment | Effect on Total Interest |
|---|---|---|---|
| Vehicle Price | Each extra $1,000 of price raises both the amount financed and the motor vehicle sales tax base, so the tax rises with it. | +$21.29 | +$208.58 |
| Trade-In Allowance | A $1,000 allowance cuts the amount financed by $1,000 and reduces the motor vehicle sales tax base by the same amount, so it saves tax as well as principal. | -$21.29 | -$208.57 |
| Cash Down Payment | A $1,000 larger down payment cuts the amount financed by $1,000. It never reduces the motor vehicle sales tax, which is assessed on the price, not on what you borrow. | -$19.92 | -$195.15 |
| Dealer Doc Fee | A $100 higher documentation fee adds $100 to the amount financed. It sits outside the motor vehicle sales tax base in Minnesota, so it does not raise the tax. Minnesota caps the fee at $350. | +$1.99 | +$19.52 |
| Longer Term | Stretching the same balance from 60 months to 72 months spreads the principal over twelve more payments at the same rate. | -$90.11 | +$1,344.28 |
Baseline: $35,000 vehicle price, $0 trade-in, $5,000 cash down, $350 documentation fee, 60 months at 7.25% APR, giving a $652.65 payment and $6,394.35 of total interest.
How This Is Calculated
Minnesota keeps documentation and registration fees out of the Motor Vehicle Sales Tax base entirely, which few states do. Four steps.
1. Net taxable base. Minn. Stat. 297B.01 subd. 14 defines the purchase price net of the trade-in allowance and net of rebates. The Department of Revenue states that documentation and registration fees are not subject to MVST, so the doc fee stays outside the base.
2. Motor Vehicle Sales Tax. One rate, statewide, with no percentage local add-on.
3. Title fee. A fixed $8.25, outside the tax base.
4. Amount financed and amortization. The trade-in works twice: it lowered the base in step one and it reduces what you borrow here.
That balance amortizes as a fixed-rate installment loan:
where $P$ is the financed amount, $i$ is the monthly rate (APR divided by 12), and $n$ is the term in months. Each period's interest is the outstanding balance times $i$, the remainder reduces principal, and the schedule reconciles to zero at maturity.
Worked Example
Minnesota keeps the doc fee out of the Motor Vehicle Sales Tax base, so the $350 below is financed but never taxed. The credit for a trade-in, by contrast, has no ceiling at all.
- Vehicle price: $35,000
- Trade-in allowance: $0
- Cash down: $5,000
- Dealer doc fee: $350
- Term: 60 months at 7.25% APR
Step 1 -- The taxable base. Sales price less rebates and trade-in allowance, with the doc fee excluded: $35,000 - $0 = $35,000.00
Step 2 -- Motor Vehicle Sales Tax at 6.875%. $35,000.00 x 6.875% = $2,406.25
Step 3 -- The title fee, outside the base. $8.25
Step 4 -- Total delivered price. $35,000 + $350.00 doc fee + $2,406.25 + $8.25 = $37,764.50
Step 5 -- Amount financed. $37,764.50 - $0 trade-in - $5,000 cash down = $32,764.50
Step 6 -- The monthly payment. $32,764.50 at 7.25% over 60 months = $652.65
Step 7 -- Month 1. $32,764.50 x (7.25% / 12) = $197.95 interest, $454.70 principal, balance $32,309.80
Step 8 -- Month 2. $32,309.80 x (7.25% / 12) = $195.21 interest, $457.44 principal, balance $31,852.36. Cumulative interest: $393.16
Step 9 -- The running total. Interest through month 12 is $2,190.40 with $27,123.10 still owed. Over 60 months, $6,394.35
Add a $10,000 trade-in and the base falls to $25,000, tax to $1,718.75, and the payment to $439.76. The trade-in saved $687.50 in tax on top of the $10,000 it took off the loan. Double the trade to $20,000 and the saving doubles to $1,375, because Minnesota puts no ceiling on the credit. That linearity is worth checking against any rate guide you read: if a source shows the credit flattening out above some dollar figure, it is describing another state's rule.
Because the tax credit scales without limit, a Minnesota buyer with a valuable trade-in has a real reason to trade in at the dealership rather than sell privately. A private sale has to beat the dealer's offer by more than 6.875% of the offer to come out ahead.
What This Does Not Account For
- Annual registration tax. Minnesota's is value based: $10 flat plus roughly 1.285% to 1.575% of the vehicle's original MSRP, multiplied by an age factor that steps down each year for about ten years before dropping to a flat minimum. On a new car this is the largest recurring cost after insurance. No single figure is honest across vehicles, so it is excluded rather than guessed at.
- The $11 filing fee charged at the deputy registrar office, and the county wheelage tax of up to $20 per year. Both are small and both are real.
- The $20 local vehicle excise tax. Some cities and counties impose it per sale and the dealer collects it. The current list of participating jurisdictions was not obtained, so it is not added here. If your buyer's order shows a $20 line labelled a local vehicle excise tax, that is what it is.
- EV and plug-in hybrid surcharges, roughly 0.5% and 0.25% of base value respectively, added to the annual registration tax.
- Trading in an off-road vehicle. Minn. Stat. ch. 297B credits a motor vehicle taken in trade. A snowmobile, ATV, or boat traded toward a car does not reduce the taxable price, even though the dealer may still allow you value for it.
- Negative equity, GAP insurance, extended warranties, and aftermarket add-ons, unless you fold them into the vehicle price yourself.
Common Pitfalls
- Using the Minneapolis or St. Paul combined sales tax rate. This is the big one. Those rates run above 9% and they do not apply to a car. Applying 9.025% to a $35,000 purchase overstates your tax by roughly $750.
- Assuming a local percentage exists somewhere in Minnesota. It does not, for vehicles. Local charges on cars are flat dollar amounts collected at sale or at registration.
- Taxing the doc fee. Minnesota Revenue excludes documentation and registration fees from MVST. Adding $350 to the base would add $24.06 of tax you do not owe.
- Using an old MVST rate. The rate rose from 6.5% to 6.875% effective 1 July 2023. On a $35,000 base that is a $131.25 difference, and stale rate guides are still circulating.
- Confusing the doc fee cap with a fixed fee. It is the lesser of $350 or 10% of the value of the sale under Minn. Stat. 168.27 subd. 31(b), and it stepped up from $200 in 2023 and $275 in 2024 to $350 for sales on or after 1 July 2025. On a $2,000 car the legal maximum is $200.
- Judging a loan by the monthly payment. Stretching this $32,764.50 balance from 60 to 72 months drops the payment to $562.54 and raises total finance charges from $6,394.35 to $7,738.71.
Frequently Asked Questions
What is Minnesota's sales tax rate on cars?
Do Minneapolis and St. Paul charge extra sales tax on a car?
Does a trade-in reduce sales tax in Minnesota?
Is the dealer documentation fee taxed in Minnesota?
How much is title and registration in Minnesota?
Does Minnesota charge property tax on vehicles?
Sources
- Minnesota Department of Revenue, Motor Vehicle Sales industry guide (documentation and registration fees not subject to MVST) revenue.state.mn.us
- Consumer Financial Protection Bureau, Truth in Lending Act (Regulation Z, 12 CFR § 1026.22) disclosure requirements for installment credit. ecfr.gov/current/title-12/chapter-X/part-1026
Also consulted: Minn. Stat. ch. 297B (Motor Vehicle Sales Tax), rate raised from 6.5% to 6.875% effective 1 July 2023; Minn. Stat. 297B.01 subd. 14 (purchase price computed net of the trade-in allowance); Minn. Stat. 168.27 subd. 31(b) (documentary fee capped at the lesser of $350 or 10% of the value of the sale or lease, for sales on or after 1 July 2025); Minnesota Department of Public Safety, Driver and Vehicle Services, vehicle fee and registration tax schedules; Experian, State of the Automotive Finance Market, Q1 2026, slide 45 (average new and used auto loan APR by VantageScore 4.0 credit tier; national, no state level cut published).
The DVS 2026 vehicle tax manual PDF refuses automated retrieval. The registration depreciation ladder described above comes from secondary summaries of that manual and should be confirmed at your deputy registrar office. The list of jurisdictions imposing the $20 local vehicle excise tax was likewise not obtained.