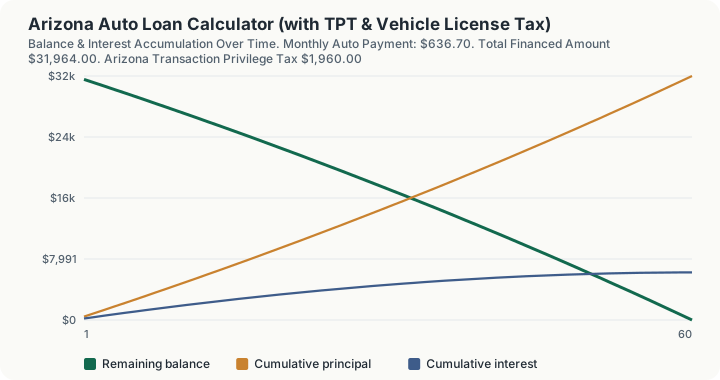
Quick Answer: A $35,000 vehicle in Arizona with $5,000 cash down, a 60-month term, and a 7.25% APR carries a $636.70 monthly payment at the 5.6% state rate alone. That includes $1,960.00 of Transaction Privilege Tax and the $4 title fee, financing $31,964.00. County and city rates add to that, and Arizona bases them on where the dealer sits, not where you live.
Overview
Arizona does not have a sales tax. It has a Transaction Privilege Tax, and the difference is not academic. Under A.R.S. § 42-5061 the TPT is a tax on the seller's privilege of doing business in the state, assessed on the dealer's gross receipts from the retail classification. Dealers pass it through to buyers, so it looks and behaves like a sales tax on the buyer's order, but the legal incidence sits on the dealer. That is why one rule surprises people: Arizona sources vehicle tax to the dealership's location, not to your address. A Scottsdale resident buying in Mesa pays Mesa's rate. Any calculator that asks for your ZIP code and quotes an Arizona rate from it is answering the wrong question.
The state rate is 5.6%. On top of that sit a county excise tax and the city privilege tax of the city where the dealer does business. Those are the numbers this calculator cannot fill in for you, and the reason is worth stating plainly: no Arizona county or city automotive rate could be confirmed from a primary rate table. The Department of Revenue rate table, the City of Phoenix site, and the Department of Transportation fee schedules all refused the request. Rather than publish a rate table built out of secondary sources, this page leaves the local rate at zero and asks you to get the figure from the dealer.
Two things are worth knowing about the widely republished Arizona rates. Phoenix raised its privilege tax rate on several classifications from 2.3% to 2.8% by Ordinance G-7369, passed on 18 March 2025, so the 8.6% combined Phoenix figure still circulating on rate sites appears stale. Scottsdale set its rate to 1.70% by Ordinance 4676, passed 20 May 2025, and the 1.75% figure that most sources carry is likewise out of date.
Auto Loan APR by Credit Score
The APR columns below are national averages, not Arizona figures. No primary source publishes average auto loan APR by state: Experian's report has no geographic cut, the CFPB publishes state origination volume but no rates, and the New York Fed publishes state delinquency only. The payment column is the part that is specific to Arizona, because it runs this calculator's own Arizona tax and fee rules at each tier's rate.
| Credit Tier | VantageScore 4.0 | Avg New APR | Avg Used APR | Est. Payment in Arizona |
|---|---|---|---|---|
| Super prime | 781-850 | 4.55% | 6.30% | $596.63 |
| Prime | 661-780 | 6.23% | 8.77% | $621.38 |
| Nonprime | 601-660 | 9.67% | 14.03% | $673.96 |
| Subprime | 501-600 | 13.44% | 19.42% | $734.50 |
| Deep subprime | 300-500 | 16.01% | 21.77% | $777.47 |
Payment assumptions: $35,000 vehicle price, $0 trade-in, $5,000 cash down, $0 dealer documentation fee, 60-month term, new-vehicle APR applied to the Arizona delivered price including tax and statutory fees. At the 6.39% overall new-car average the same purchase costs $623.77 a month.
The score bands are VantageScore 4.0, not FICO. The same borrower can land in a different tier under each model, so a FICO score pulled from a card issuer will not always match the band here. Source: Experian, State of the Automotive Finance Market, Q1 2026, slide 45.
What Moves Your Payment
Each row changes one input and leaves the rest at the baseline below. The dollar effects are this calculator's own output for Arizona, not a rule of thumb.
| Factor | What Changes | Effect on Monthly Payment | Effect on Total Interest |
|---|---|---|---|
| Vehicle Price | Each extra $1,000 of price raises both the amount financed and the transaction privilege tax base, so the tax rises with it. | +$21.04 | +$206.09 |
| Trade-In Allowance | A $1,000 allowance cuts the amount financed by $1,000 and reduces the transaction privilege tax base by the same amount, so it saves tax as well as principal. | -$21.03 | -$206.09 |
| Cash Down Payment | A $1,000 larger down payment cuts the amount financed by $1,000. It never reduces the transaction privilege tax, which is assessed on the price, not on what you borrow. | -$19.92 | -$195.16 |
| Dealer Doc Fee | A $100 higher documentation fee adds $100 to the amount financed and is inside the transaction privilege tax base, so it is taxed on top of itself. | +$2.11 | +$20.61 |
| Longer Term | Stretching the same balance from 60 months to 72 months spreads the principal over twelve more payments at the same rate. | -$87.90 | +$1,311.43 |
Baseline: $35,000 vehicle price, $0 trade-in, $5,000 cash down, $0 documentation fee, 60 months at 7.25% APR, giving a $636.70 payment and $6,238.19 of total interest.
How This Is Calculated
Arizona's levy is a Transaction Privilege Tax on the dealer's business rather than a sales tax on you, though it lands on your buyer's order either way. Four steps.
1. Net taxable base. ADOR's motor vehicle sales guidance lists the total trade-in allowance as a deduction from the retail tax base. The dealer documentation fee is part of gross receipts and stays inside the base.
2. Transaction Privilege Tax. The 5.6% state retail rate plus whatever county and city rate applies at the dealer's location.
3. Title fee. A flat $4. Arizona's registration charge is deliberately excluded, for reasons set out in the next section.
4. Amount financed and amortization. The trade-in works twice: it reduced the tax base in step one, and it reduces what you borrow. The result amortizes as a fixed-rate installment loan:
where $P$ is the financed amount, $i$ is the monthly rate (APR divided by 12), and $n$ is the term in months.
Why Registration Is Not In This Number
Arizona's registration cost is dominated by the Vehicle License Tax, which is not a flat fee at all. The VLT is an annual ad valorem charge collected at registration in lieu of local personal property tax on the vehicle. Its base is 60% of the manufacturer's base retail price in the first year, declining by 16.25% of the previous year's figure each renewal. The rate is $2.80 per $100 of assessed value for a new vehicle and $2.89 per $100 for a used one.
That means the VLT depends on the vehicle's MSRP and its model year, not on the price you negotiated. Two buyers paying the same $35,000 for the same car pay the same TPT and different VLT if one car is newer.
Two consequences follow. The first is that a single fixed registration figure would misrepresent the cost badly, so this calculator does not include one. The small fixed components Arizona charges alongside the VLT could not be re-read from a primary source, which is the second reason they are left out rather than asserted.
The third consequence is the one that costs money. The trade-in reduces your TPT but not your VLT. They are two separate taxes with two separate bases. A $10,000 trade-in saves $560 of TPT at the state rate on a $35,000 car and changes the annual VLT by nothing at all, because the VLT never looks at what you paid.
Worked Example
What Arizona charges is not legally a sales tax at all: the Transaction Privilege Tax is levied on the dealer's privilege of doing business and passed through to you. It still comes off the invoice, and the trade-in still reduces it.
- Vehicle price: $35,000
- Trade-in allowance: $0
- Cash down: $5,000
- Dealer doc fee: $0
- County and city rate: 0% (state floor)
- Term: 60 months at 7.25% APR
Step 1 -- The taxable base. No doc fee entered and no trade-in, so gross receipts are the price: $35,000.00
Step 2 -- Transaction Privilege Tax at the 5.6% state rate. $35,000.00 x 5.6% = $1,960.00
Step 3 -- The title fee, which sits outside the base. $4.00
Step 4 -- Total delivered price. $35,000 + $1,960.00 + $4.00 = $36,964.00
Step 5 -- Amount financed. $36,964.00 - $0 trade-in - $5,000 cash down = $31,964.00
Step 6 -- The monthly payment. $31,964.00 at 7.25% over 60 months = $636.70
Step 7 -- Month 1. $31,964.00 x (7.25% / 12) = $193.12 interest, $443.58 principal, balance $31,520.42
Step 8 -- Month 2. $31,520.42 x (7.25% / 12) = $190.44 interest, $446.26 principal, balance $31,074.16. Cumulative interest: $383.56
Step 9 -- The accumulation. Through month 12 the interest paid is $2,136.91 and the balance is $26,460.51. Over 60 months the total finance charge is $6,238.19
Add a $10,000 trade-in and the base falls to $25,000, TPT falls to $1,400.00, and the payment falls to $426.35. The trade-in is worth $560.00 in tax by itself at the state rate, and more once a county and city rate is added: at a 3.5% combined local rate, the same trade-in saves $910.00.
Now add a $499 doc fee to the baseline. Because it sits inside gross receipts, the taxable base becomes $35,499 and TPT rises to $1,987.94. The fee costs $499 plus $27.94 of tax on the fee, at the state rate alone.
What This Does Not Account For
- County and city rates. Left at zero because none could be verified from a primary rate table. A realistic Arizona combined rate runs several points above 5.6%, so the default output here is a floor, not an estimate of your actual bill.
- Two-tier city retail rates. Several Arizona cities apply a lower privilege tax rate to the portion of a single item above a threshold in the region of $10,000 to $11,000, indexed. Tucson is reported to be one of them. Where such a structure applies, entering a flat combined percentage overstates the city tax on a car. That structure could not be confirmed per city.
- The Vehicle License Tax and registration fees. Explained above. The VLT is annual, value-based, and unaffected by your trade-in or your negotiated price.
- Dealer-location sourcing. The calculator applies whatever local rate you type. It cannot tell you which jurisdiction's rate your dealer will charge. Ask them.
- Dealer documentation fees. Arizona sets no statutory cap and no verified market average was found, so the input starts at $0.
- Private-party purchases, where no dealer collects TPT and use tax rules apply instead.
- GAP insurance, extended warranties, and aftermarket add-ons, unless you fold them into the vehicle price yourself.
Common Pitfalls
- Looking up your own ZIP code's rate. Arizona taxes the dealer's location. Buying across a city line genuinely changes the tax, which is not true in most states.
- Using a stale Phoenix rate. The 8.6% combined figure predates Ordinance G-7369, which raised the city rate to 2.8% in March 2025. Scottsdale's 1.75% is likewise stale against the 1.70% set by Ordinance 4676.
- Expecting the trade-in to lower your registration bill. It lowers TPT only. The Vehicle License Tax is computed from manufacturer base retail price with no additions and no deductions.
- Applying a flat city rate in a two-tier city. The result is too high, not too low, because the second tier is the lower one.
- Forgetting the doc fee is taxed. Arizona caps nothing and taxes the fee as part of gross receipts, so a $499 fee costs $526.94 at the state rate alone.
- Judging a loan by the monthly payment alone. Stretching this $31,964.00 balance from 60 to 72 months lowers the payment to $548.80 and raises total finance charges from $6,238.19 to $7,549.57.
Frequently Asked Questions
What is Arizona's sales tax rate on cars?
Does a trade-in reduce sales tax in Arizona?
Is Arizona vehicle tax based on where I live or where I buy?
What is the Arizona Vehicle License Tax?
Is there a cap on dealer documentation fees in Arizona?
Why does this calculator leave out Arizona registration fees?
Sources
- A.R.S. § 42-5061 (Transaction Privilege Tax, retail classification) azleg.gov/arstitle
- Arizona Department of Revenue, motor vehicle sales guidance (trade-in allowance as a deduction from the retail tax base; doc fees within gross receipts) azdor.gov
- Consumer Financial Protection Bureau, Truth in Lending Act (Regulation Z, 12 CFR § 1026.22) disclosure requirements for installment credit. ecfr.gov/current/title-12/chapter-X/part-1026
Also consulted: Arizona Department of Transportation, Motor Vehicle Division, title and registration (title fee; Vehicle License Tax assessment method and rates); City of Phoenix Ordinance G-7369, passed 18 March 2025 (privilege tax rate to 2.8%); City of Scottsdale Ordinance 4676, passed 20 May 2025 (privilege tax rate to 1.70%), per ADOR Rate and Code Updates; Experian, State of the Automotive Finance Market, Q1 2026, slide 45 (average new and used auto loan APR by VantageScore 4.0 credit tier; national, no state level cut published).