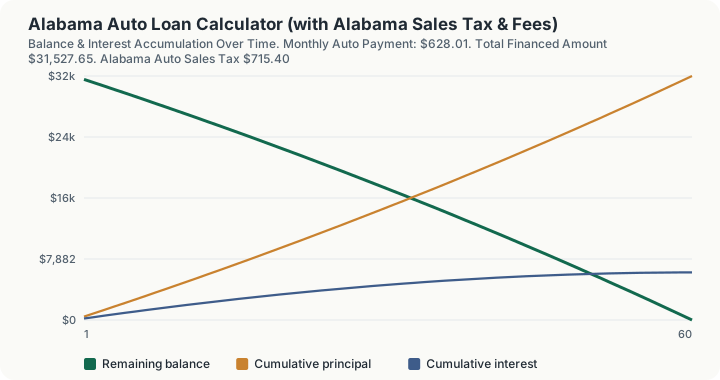
Quick Answer: A $35,000 vehicle in Alabama with $5,000 cash down, a $770 dealer documentation fee, a 60-month term, and a 7.25% APR carries a $628.01 monthly payment. That figure includes $715.40 of Alabama automotive sales tax at the 2% state rate and $42.25 in title and registration fees, financing $31,527.65 in total.
Overview
Alabama taxes motor vehicles at 2%, which is half the state's 4% general sales tax rate. This is not a rounding quirk. Ala. Code § 40-23-2(4) creates a separate automotive rate that applies to cars, trucks, truck trailers, house trailers, and motorcycles, while parts and accessories bought at the same dealership are taxed at the full 4%.
That 2% figure is where most Alabama car buyers stop reading, and it is where most payment estimates go wrong. Counties and cities levy their own automotive add-ons on top, and in the state's largest metros those add-ons are larger than the state rate itself. A Birmingham buyer pays 4.75% combined. A Mobile buyer inside the city limits also pays 4.75%. The state rate alone describes almost nobody's actual tax bill.
This calculator separates the two so you can see both. Leave the local rate at zero and you get the statewide floor, which is useful for comparing loan offers across counties. Enter your local rate, or pick your metro from the scenario buttons, and you get the number your dealer will actually put on the buyer's order.
It also models the trade-in credit, which is the single largest tax lever available to an Alabama buyer and the one most often left out of online estimates.
Auto Loan APR by Credit Score
The APR columns below are national averages, not Alabama figures. No primary source publishes average auto loan APR by state: Experian's report has no geographic cut, the CFPB publishes state origination volume but no rates, and the New York Fed publishes state delinquency only. The payment column is the part that is specific to Alabama, because it runs this calculator's own Alabama tax and fee rules at each tier's rate.
| Credit Tier | VantageScore 4.0 | Avg New APR | Avg Used APR | Est. Payment in Alabama |
|---|---|---|---|---|
| Super prime | 781-850 | 4.55% | 6.30% | $588.49 |
| Prime | 661-780 | 6.23% | 8.77% | $612.90 |
| Nonprime | 601-660 | 9.67% | 14.03% | $664.76 |
| Subprime | 501-600 | 13.44% | 19.42% | $724.47 |
| Deep subprime | 300-500 | 16.01% | 21.77% | $766.86 |
Payment assumptions: $35,000 vehicle price, $0 trade-in, $5,000 cash down, $770 dealer documentation fee, 60-month term, new-vehicle APR applied to the Alabama delivered price including tax and statutory fees. At the 6.39% overall new-car average the same purchase costs $615.25 a month.
The score bands are VantageScore 4.0, not FICO. The same borrower can land in a different tier under each model, so a FICO score pulled from a card issuer will not always match the band here. Source: Experian, State of the Automotive Finance Market, Q1 2026, slide 45.
What Moves Your Payment
Each row changes one input and leaves the rest at the baseline below. The dollar effects are this calculator's own output for Alabama, not a rule of thumb.
| Factor | What Changes | Effect on Monthly Payment | Effect on Total Interest |
|---|---|---|---|
| Vehicle Price | Each extra $1,000 of price raises both the amount financed and the sales tax base, so the tax rises with it. | +$20.32 | +$199.06 |
| Trade-In Allowance | A $1,000 allowance cuts the amount financed by $1,000 and reduces the sales tax base by the same amount, so it saves tax as well as principal. | -$20.32 | -$199.07 |
| Cash Down Payment | A $1,000 larger down payment cuts the amount financed by $1,000. It never reduces the sales tax, which is assessed on the price, not on what you borrow. | -$19.92 | -$195.16 |
| Dealer Doc Fee | A $100 higher documentation fee adds $100 to the amount financed and is inside the sales tax base, so it is taxed on top of itself. | +$2.03 | +$19.91 |
| Longer Term | Stretching the same balance from 60 months to 72 months spreads the principal over twelve more payments at the same rate. | -$86.70 | +$1,293.53 |
Baseline: $35,000 vehicle price, $0 trade-in, $5,000 cash down, $770 documentation fee, 60 months at 7.25% APR, giving a $628.01 payment and $6,152.97 of total interest.
How This Is Calculated
Alabama taxes a car at 2%, less than half the 4% general sales tax rate, then lets counties and cities stack automotive rates on top of it. Five steps get from sticker price to monthly payment.
1. Net taxable base. Ala. Code § 40-23-2(4) taxes the net difference after a trade-in, not the sticker price. The Alabama Department of Revenue also treats the dealer documentation fee as part of the taxable automotive base, while a separately stated title fee sits outside it.
Ala. Admin. Code r. 810-6-1-.22(1)(a) caps the allowance on a trade-up: it "cannot exceed the sales price of the vehicles sold by the dealer." Because the cap is measured against the vehicle price alone, a trade worth more than the car still leaves the doc fee taxable rather than driving the base below zero.
2. Sales tax. The combined rate is the 2% state automotive rate plus whatever county and city automotive rate applies where the vehicle is registered.
3. Title and registration. A fixed $42.25, being the $18 typical out-the-door title cost and the $23 standard passenger plate with its $1.25 issuance fee. These are not taxed when separately stated.
4. Amount financed. The trade-in works twice here. It lowered the tax base in step one, and it also reduces the balance you borrow.
5. Amortization. The financed amount amortizes as a fixed-rate installment loan under the standard annuity formula:
where $P$ is the financed amount, $i$ is the monthly rate (APR ÷ 12), and $n$ is the term in months. Each period's interest is the outstanding balance times $i$, the remainder reduces principal, and the schedule reconciles to zero at maturity.
Alabama Vehicle Tax Rates by Metro
Local automotive rates are almost always lower than local general sales tax rates, and confusing the two is the most common source of bad Alabama estimates. Jefferson County charges 2% general sales tax but only 0.75% on vehicles. These are the automotive rates.
| Metro | County | County Auto | City Auto | State | Combined |
|---|---|---|---|---|---|
| Birmingham | Jefferson | 0.750% | 2.000% | 2% | 4.750% |
| Mobile | Mobile | 0.500% | 2.250% | 2% | 4.750% |
| Huntsville | Madison | 0.250% | 1.750% | 2% | 4.000% |
| Tuscaloosa | Tuscaloosa | 0.750% | 1.125% | 2% | 3.875% |
| Montgomery | Montgomery | 0.333% | 1.250% | 2% | 3.583% |
Two of these depend on city limits. Mobile County charges 0.500% inside the corporate limits of Mobile and Prichard but 1.000% outside them. Tuscaloosa County charges 0.750% inside corporate limits against a 1.875% countywide rate. Tuscaloosa County's automotive rate rose from 1.500% on 1 November 2025, so older rate tables understate it.
Rates published by the Alabama Department of Revenue are refreshed monthly. Confirm yours with the county licensing official before you sign.
Worked Example
Alabama's 2% automotive rate is the lowest headline vehicle tax in the Southeast, and the trade-in credit under Ala. Code 40-23-2(4) makes it lower still. Here is the state-floor case, matching the published test vector.
- Vehicle price: $35,000
- Trade-in allowance: $0
- Cash down: $5,000
- Dealer doc fee: $770
- Local rate: 0% (state floor)
- Term: 60 months at 7.25% APR
Step 1 -- The taxable base. Price plus the taxable doc fee, less any trade-in credit: $35,000 + $770 - $0 = $35,770.00
Step 2 -- The automotive sales tax. $35,770.00 x 2% = $715.40
Step 3 -- Title and registration, outside the tax base. $18.00 title + $23.00 plate + $1.25 issuance = $42.25
Step 4 -- Total delivered price. $35,000 + $770.00 + $715.40 + $42.25 = $36,527.65
Step 5 -- Amount financed. $36,527.65 - $0 trade-in - $5,000 cash down = $31,527.65
Step 6 -- The monthly payment. $31,527.65 amortized at 7.25% over 60 months = $628.01
Step 7 -- Where month 1 goes. Interest is the opening balance times the monthly rate: $31,527.65 x (7.25% / 12) = $190.48, leaving $437.53 of principal and a balance of $31,090.12
Step 8 -- Where month 2 goes. $31,090.12 x (7.25% / 12) = $187.84 interest and $440.17 of principal, for a balance of $30,649.95. Two months in, cumulative interest is $378.32
Step 9 -- The accumulation. By month 12 you have paid $2,107.75 in interest and still owe $26,099.28. Over the full 60 months the finance charge totals $6,152.97
Now add a $10,000 trade-in and nothing else changes. The taxable base drops to $25,770, tax falls to $515.40, and the payment drops to $424.83. The trade-in saved $200 in tax on its own, which is the section 40-23-2(4) credit doing its work. In Birmingham, where the combined rate is 4.75%, that same trade-in saves $475.
That gap is the practical argument for trading in at the dealership rather than selling privately and bringing cash. A private sale has to clear the trade-in offer by more than the tax credit to come out ahead.
What This Does Not Account For
- Annual ad valorem property tax. Alabama assesses vehicles annually at registration renewal under Ala. Code § 40-12-253, separate from the purchase tax. Private passenger vehicles are Class IV property under Ala. Code § 40-8-1, assessed at 15% of market value, then multiplied by the local millage rate. It is a recurring cost, not something financed into the loan.
- Trade-in credit on private-party purchases. Private sales are taxed under the separate casual sales and use tax at Ala. Code § 40-23-101. Neither that statute nor ADOR's casual sales guidance states whether a trade-in reduces that base, so this calculator does not model one. Ask your county licensing official.
- County-specific title surcharges. The $18 title figure covers the $15 statutory fee plus the two $1.50 commissions a designated agent and issuing official may each add. Individual counties may charge additional local fees.
- Electric and plug-in hybrid surcharges. Alabama charges an extra annual registration fee for EVs and PHEVs under Ala. Code § 40-12-242. That amount is not modeled here.
- Truck chassis with a body added at purchase, which ADOR taxes at the general 4% rate rather than the 2% automotive rate.
- GAP insurance, extended warranties, and aftermarket add-ons, unless you fold them into the vehicle price yourself.
Common Pitfalls
- Reading the 2% state rate as the full tax bill. Every major Alabama metro lands between 3.583% and 4.75% combined. On a $35,770 base that is a difference of $566 to $984 against the state-only figure.
- Substituting the general sales tax rate for the automotive rate. They are different numbers in most Alabama jurisdictions, and the general rate is usually higher. Using it inflates your estimate.
- Forgetting the doc fee is taxable. Alabama caps nothing here, and ADOR taxes doc fees at the automotive rate, so a $770 fee adds $15.40 of tax at the state rate and $36.58 in Birmingham.
- Rolling negative equity forward. If you owe more than the trade is worth, the shortfall is added to the new loan. It raises the principal and the total interest, and it does not increase your tax credit, which is based on the allowance rather than your equity.
- Comparing a credit union pre-approval against a dealer's quoted rate without asking whether the dealer rate includes a markup over the wholesale buy rate the lender gave them.
- Judging a loan by the monthly payment alone. Stretching this $31,527.65 balance from 60 to 72 months lowers the payment and raises what you pay in total finance charges.
Frequently Asked Questions
What is Alabama's sales tax rate on cars?
Does a trade-in reduce sales tax in Alabama?
Is there a cap on dealer documentation fees in Alabama?
How much are Alabama title and tag fees?
How is Alabama's annual ad valorem tax different from sales tax?
Where do I pay tax on a car bought from a private seller?
Sources
- Alabama Department of Revenue, Automotive Sales, Use & Lease Tax Guide (2% automotive rate, doc fee taxability, separately stated title fee treatment) revenue.alabama.gov
- Consumer Financial Protection Bureau, Truth in Lending Act (Regulation Z, 12 CFR § 1026.22) disclosure requirements for installment credit. ecfr.gov/current/title-12/chapter-X/part-1026
Also consulted: Ala. Code § 40-23-2(4) (state automotive rate and trade-in net difference provision); Ala. Admin. Code r. 810-6-1-.22(1)(a) (trade-in allowance cap); Ala. Code § 40-23-101 (casual sales and use tax on private-party purchases); Ala. Code § 40-12-253 (annual ad valorem assessment at registration renewal) and Ala. Code § 40-8-1 (Class IV classification, 15% assessment ratio); Alabama Department of Revenue, motor vehicle certificate of title fee and registration fee schedules; Alabama Department of Revenue, local city and county tax rate file, August 2026 release, filtered to automotive rates; Experian, State of the Automotive Finance Market, Q1 2026, slide 45 (average new and used auto loan APR by VantageScore 4.0 credit tier; national, no state level cut published).