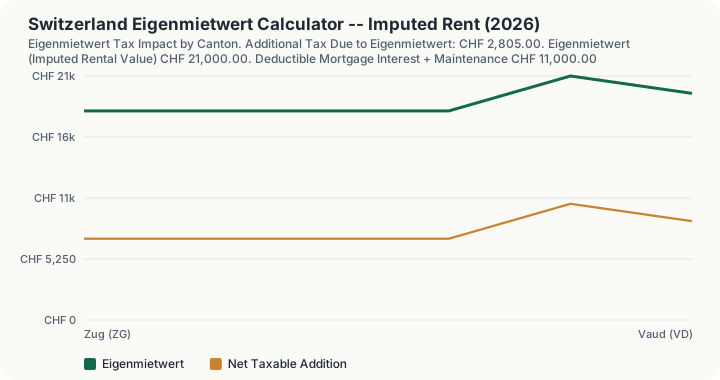
Quick Answer: A single Zurich homeowner with a CHF 30,000/year market rental value, CHF 8,000 in deductible mortgage interest, and CHF 3,000 in deductible maintenance costs has a net taxable Eigenmietwert addition of CHF 10,000, adding an estimated CHF 2,805.00 to their 2026 combined federal, cantonal, and communal tax bill on top of CHF 100,000 of other taxable income.
Overview
Eigenmietwert (imputed rental value) is one of the most distinctive -- and, to non-Swiss homeowners, one of the most surprising -- features of Swiss tax law. If you own the home you live in, Switzerland requires you to declare a notional rental income as if you had rented the property out to yourself, and add it to your taxable income, even though you never actually receive that money in cash. The logic is one of tax parity: a renter's landlord pays tax on rental income, so an owner-occupier is taxed on the equivalent imputed income to avoid an unfair advantage over renters.
This system is being phased out, but is NOT gone yet. On 28 September 2025 Swiss voters approved the Reform der Wohneigentumsbesteuerung, with 57.7% in favour, ending decades of argument about a tax that exists nowhere else. Abolition is not immediate. The Federal Council has indicated it intends to bring the change into force on 1 January 2029, which leaves Eigenmietwert in place for the whole of 2026, 2027 and 2028. The delay is not procedural foot-dragging: every canton has to rewrite its own tax law, and the cantons that depend on taxing holiday homes negotiated a parallel new property levy as the price of their support, which itself needs implementing legislation.
So for 2026 the system applies exactly as this calculator models it. Two consequences are worth planning around now. The abolition removes the mortgage-interest and maintenance deductions along with the imputed income, so an owner carrying a large mortgage against a modest imputed value may end up worse off, not better. And some cantons have already begun freezing their side of it: the canton of Zurich decided in November 2025 not to proceed with a planned increase in its Eigenmietwerte, precisely because the system is on its way out.
Every canton calculates Eigenmietwert using its own method and its own percentage of market rental value, subject to a Federal Court floor of at least 60% of a comparable market rent. This calculator covers 6 representative cantons: Zurich's method is precisely, directly documented (a dual-rate system based on an official tax value); the other 5 cantons' percentages here are representative estimates from secondary sources, not independently verified against each canton's primary statute -- flagged clearly in this calculator's output.
How This Is Calculated
- Eigenmietwert. Your entered estimated annual market rental value is multiplied by your canton's percentage.
- Net taxable addition. Your deductible mortgage interest and maintenance/upkeep costs are subtracted from the Eigenmietwert; the result is floored at zero (a genuine economic loss on the property does not create a negative addition to your OTHER taxable income in this simplified model).
- Additional tax. This platform's Switzerland combined income-tax model (federal + cantonal + communal) is run twice -- once on your other taxable income alone, once with the net Eigenmietwert addition included -- and the difference is the additional tax attributable to Eigenmietwert.
Worked Example
Using the calculator's default inputs -- CHF 30,000 annual market rental value, CHF 8,000 deductible mortgage interest, CHF 3,000 deductible maintenance, CHF 100,000 other taxable income, single, Zurich:
- Eigenmietwert: CHF 30,000 × 70% = CHF 21,000.00 (Zurich's precisely documented percentage).
- Deductible costs: CHF 8,000 mortgage interest + CHF 3,000 maintenance = CHF 11,000.00.
- Net taxable addition: CHF 21,000.00 − CHF 11,000.00 = CHF 10,000.00, added on top of CHF 100,000 other taxable income for a total of CHF 110,000.
- Tax without Eigenmietwert (CHF 100,000 other income): CHF 15,912.35 (per this platform's Zurich model).
- Tax with Eigenmietwert (CHF 110,000 total taxable income): estimated at roughly CHF 18,717.35.
- Additional tax due to Eigenmietwert: CHF 18,717.35 − CHF 15,912.35 ≈ CHF 2,805.00.
- Switching only the canton to Geneva (same market rent, same deductions): Eigenmietwert drops to CHF 18,000.00 (60% instead of 70%), producing a smaller net addition (CHF 7,000.00) and less additional tax.
What This Does Not Account For
- The pending abolition and transition rules. Swiss voters approved abolishing Eigenmietwert on 28 September 2025, and the Federal Council has signalled 1 January 2029 as the intended commencement date, with each canton needing to update its own law before then. This calculator models the current, still-in-force system and does not attempt to model the transition or the new holiday-home levy that accompanies it.
- Precise canton-specific formulas beyond Zurich. Geneva uses a living-space-and-features questionnaire; Vaud applies coefficients for age, location, comfort, and type with 3-30% possible deductions from a base figure; Bern uses a hedonic model based on comparable sale prices; Basel-Stadt uses building insurance value, age depreciation, and land value. This calculator approximates all of these as a flat percentage of market rental value -- a genuine simplification, most accurate for Zurich.
- Renovation and energy-efficiency deductions. Many cantons allow additional deductions for value-preserving renovations or energy-efficiency investments (e.g., a heat-pump installation) beyond ordinary maintenance -- not modeled here.
- Vacation/secondary homes and the cantons that opted for a replacement levy. Some tourism-dependent cantons negotiated a new property tax specifically for second homes as part of the abolition deal, a mechanism not modeled here.
- The flat-rate vs. itemized maintenance deduction choice. Most cantons let you choose, each tax year, between an itemized actual-cost maintenance deduction and a flat percentage of your property's tax value -- this calculator takes your maintenance deduction as a direct input rather than modeling that choice.
- Wealth tax on the property itself. Owning property also affects your Vermögenssteuer (net wealth tax) base -- see this platform's companion Switzerland Wealth Tax Calculator.
Common Pitfalls
- Forgetting Eigenmietwert exists at all. Homeowners moving to Switzerland from countries without an imputed-rent system are often caught off guard the first time they see it on a tax assessment -- it is a real, cash-relevant addition to taxable income, not a footnote.
- Assuming Eigenmietwert is already gone. The September 2025 referendum approved abolition, but the old system stays in force through the 2028 tax year on the Federal Council's stated timetable. Three more filings, at least, still include it. Do not skip declaring it on the strength of the headlines.
- Only deducting mortgage interest and forgetting maintenance. Both are separately deductible against Eigenmietwert (and other income); many first-time filers only remember the mortgage-interest deduction.
- Paying off your mortgage without realizing the tax tradeoff. Once a mortgage is paid off, the mortgage-interest deduction disappears, so the FULL Eigenmietwert (less maintenance only) becomes taxable -- a genuine incentive some Swiss financial advisors cite for maintaining some mortgage debt rather than fully repaying it, though the right call depends on your full financial picture.
- Comparing your own canton's method to this calculator's simplified percentage without checking your canton's actual formula. Only Zurich's percentage here is precisely documented; treat the other 5 cantons' figures as a starting estimate, not a filing-grade number.
Frequently Asked Questions
Is Eigenmietwert really being abolished?
Why does Zurich's percentage differ from other cantons in this calculator?
Can I reduce my Eigenmietwert tax bill?
Does renting out part of my home change my Eigenmietwert?
What happens to Eigenmietwert if I have a vacation home?
Sources
- Swiss Federal Tax Administration, the official authority for the national tax authority this calculator relates to. estv.admin.ch
Also consulted: Federal referendum result: the nationwide vote of 28 September 2025 on the Reform der Wohneigentumsbesteuerung, approved with 57.7% in favour. The Federal Council has since indicated an intended commencement of 1 January 2029, leaving the existing system in force through the 2028 tax period. Re-verified 2026-08-28; Kanton Zürich (zh.ch) and multiple corroborating Swiss real-estate advisory sources (ZKB, neho, RealAdvisor, Strike Advisory, Houzy): Zurich's dual-rate Eigenmietwert method (70% tax value; 3.5%/4.25% of tax value); Migros Bank, UBS Switzerland, Houzy, and immoverkauf24: representative canton-by-canton Eigenmietwert calculation-method summaries for Geneva, Vaud, Bern, and Basel-Stadt; Federal Court 60%-of-market-rent floor.