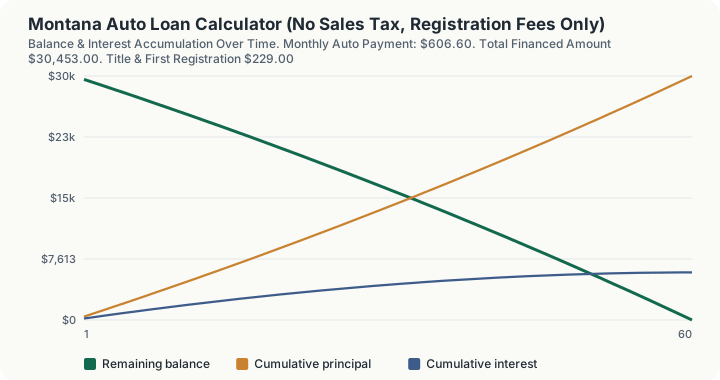
Quick Answer: A $35,000 vehicle in Montana with $5,000 cash down, a $224 dealer documentation fee, a 60-month term, and a 7.25% APR carries a $606.60 monthly payment. There is no sales tax line in that figure because Montana levies no sales or use tax. The delivered price is $35,453.00, being the price, the doc fee, and $229.00 of title and first registration, financing $30,453.00.
Overview
Montana is one of a handful of states with no general sales or use tax, and the vehicle purchase is where that shows up most plainly. There is no 6% added at signing, no local rate to look up, no trade-in credit to calculate, because there is no purchase tax for any of those things to modify. The same $35,000 car that costs $35,453 delivered here would carry roughly $2,100 in tax in a 6% state before the dealer added anything else.
What Montana does instead is charge you at registration, and it charges by the vehicle's age rather than its value. Under MCA 61-3-321, a light vehicle 4 years old or newer is $217, one that is 5 to 10 years old is $87, and one that is 11 years or older is a single one-time permanent registration payment of $28. A $90,000 SUV and a $22,000 sedan of the same model year pay the same $217. That is unusual: most states that skip the sales tax make it back with a value-based annual fee, and Montana largely does not.
Two things do scale with value, and both arrive at registration rather than at the dealership. Counties may levy a local option motor vehicle tax of up to 0.7% under MCA 61-3-537, subject to voter approval, assessed on the value determined under MCA 61-3-503. And a light vehicle with an MSRP above $150,000 that is 10 years old or newer owes an additional $825 annually. Neither is a purchase tax and neither is financed into your loan, so neither appears in the payment above.
Auto Loan APR by Credit Score
The APR columns below are national averages, not Montana figures. No primary source publishes average auto loan APR by state: Experian's report has no geographic cut, the CFPB publishes state origination volume but no rates, and the New York Fed publishes state delinquency only. The payment column is the part that is specific to Montana, because it runs this calculator's own Montana tax and fee rules at each tier's rate.
| Credit Tier | VantageScore 4.0 | Avg New APR | Avg Used APR | Est. Payment in Montana |
|---|---|---|---|---|
| Super prime | 781-850 | 4.55% | 6.30% | $568.43 |
| Prime | 661-780 | 6.23% | 8.77% | $592.00 |
| Nonprime | 601-660 | 9.67% | 14.03% | $642.10 |
| Subprime | 501-600 | 13.44% | 19.42% | $699.78 |
| Deep subprime | 300-500 | 16.01% | 21.77% | $740.72 |
Payment assumptions: $35,000 vehicle price, $0 trade-in, $5,000 cash down, $224 dealer documentation fee, 60-month term, new-vehicle APR applied to the Montana delivered price including tax and statutory fees. At the 6.39% overall new-car average the same purchase costs $594.28 a month.
The score bands are VantageScore 4.0, not FICO. The same borrower can land in a different tier under each model, so a FICO score pulled from a card issuer will not always match the band here. Source: Experian, State of the Automotive Finance Market, Q1 2026, slide 45.
What Moves Your Payment
Each row changes one input and leaves the rest at the baseline below. The dollar effects are this calculator's own output for Montana, not a rule of thumb.
| Factor | What Changes | Effect on Monthly Payment | Effect on Total Interest |
|---|---|---|---|
| Vehicle Price | Each extra $1,000 of price is financed in full. Montana levies no state vehicle purchase tax, so price moves the loan only. | +$19.92 | +$195.16 |
| Trade-In Allowance | A $1,000 allowance cuts the amount financed by $1,000. Montana levies no state vehicle purchase tax, so there is no state tax base for it to reduce. | -$19.92 | -$195.16 |
| Cash Down Payment | A $1,000 larger down payment cuts the amount financed by $1,000. | -$19.92 | -$195.16 |
| Dealer Doc Fee | A $100 higher documentation fee adds $100 to the amount financed. Montana levies no state vehicle purchase tax, so nothing is charged on top of it. | +$2.00 | +$19.51 |
| Longer Term | Stretching the same balance from 60 months to 72 months spreads the principal over twelve more payments at the same rate. | -$83.74 | +$1,249.44 |
Baseline: $35,000 vehicle price, $0 trade-in, $5,000 cash down, $224 documentation fee, 60 months at 7.25% APR, giving a $606.60 payment and $5,943.29 of total interest.
How This Is Calculated
Montana has no sales tax and no vehicle purchase tax, so nothing in this calculation scales with price except the loan itself. Three steps. The tax primitive is still used, with a rate of zero, so that this calculator shares one tested implementation of delivered-price arithmetic with the other forty-nine states rather than reimplementing it.
1. Delivered price. No tax term appears anywhere in it.
The $229 is the $12 certificate of title plus the $217 light vehicle registration for a vehicle 4 years old or newer, which is the band a new purchase falls into.
2. Amount financed. Here, and only here, the trade-in does its work.
In a state with a sales tax, a trade-in earns you twice: once against the loan and once against the tax. In Montana it earns you once. That is not a disadvantage, since there is no tax to be credited against in the first place, but it does change how a dealer trade offer compares to a private sale. Nothing about the tax code tilts the decision here. Take whichever offer is higher.
3. Amortization. The financed balance amortizes as a fixed-rate installment loan:
where $P$ is the financed amount, $i$ is the monthly rate (APR divided by 12), and $n$ is the term in months. Each period's interest is the outstanding balance times $i$, the remainder reduces principal, and the schedule reconciles to zero at maturity.
Worked Example
There is no tax step in Montana. The interesting thing about the arithmetic below is what is missing from it: between the doc fee and the loan there is nothing but two flat statutory charges.
- Vehicle price: $35,000
- Trade-in allowance: $0
- Cash down: $5,000
- Dealer doc fee: $224
- Term: 60 months at 7.25% APR
Step 1 -- Sales tax. Montana levies no general sales or use tax on a vehicle purchase: $0.00
Step 2 -- Title and first registration. $12.00 title + $217.00 registration = $229.00
Step 3 -- Total delivered price. $35,000 + $224.00 doc fee + $229.00 = $35,453.00
Step 4 -- Amount financed. $35,453.00 - $0 trade-in - $5,000 cash down = $30,453.00
Step 5 -- The monthly payment. $30,453.00 at 7.25% over 60 months = $606.60
Step 6 -- Month 1. $30,453.00 x (7.25% / 12) = $183.99 interest, $422.61 principal, balance $30,030.39
Step 7 -- Month 2. $30,030.39 x (7.25% / 12) = $181.43 interest, $425.17 principal, balance $29,605.22. Cumulative interest: $365.42
Step 8 -- The accumulation. Interest through month 12 is $2,035.88. Over the full 60 months, $5,943.29
Add a $10,000 trade-in and the delivered price does not move at all. It stays at $35,453.00. Only the financed balance changes, to $20,453.00, and the payment falls to $407.41. Watching the delivered price stay put is the clearest illustration of what the absence of a sales tax means: in a 6% state that same trade-in would also have knocked $600 off the tax bill.
The effect scales without limit because nothing here is a percentage. A $160,000 vehicle produces a delivered price of $160,453.00, exactly $125,000 more than the baseline. In a 6% state the same step up would add $132,500. The gap widens with every dollar of price, which is why Montana's no-tax status matters most to buyers at the top of the market and least to buyers of inexpensive used cars.
What This Does Not Account For
- County local option motor vehicle tax. MCA 61-3-537 allows counties to levy up to 0.7% of the vehicle value determined under MCA 61-3-503, or a flat local fee instead, subject to voter approval. It is collected at registration, not at the dealership. Which counties currently impose it and at what rate could not be verified, so no county rate is applied here. At the statutory ceiling, 0.7% on a $35,000 valuation would be $245 a year. Ask your county treasurer for the actual figure before you budget.
- The $825 luxury fee. Light vehicles with an MSRP over $150,000 that are 10 years old or newer owe an extra $825 annually. It is a recurring registration charge rather than a purchase cost, so it is not financed into the payment above. This figure comes from secondary summaries of the state fee schedule and should be confirmed.
- Renewal registration in later years. The $217 band applies while the vehicle is 4 years old or newer. It drops to $87 at 5 years and to a one-time $28 at 11 years, which means a Montana registration bill gets cheaper as the car ages rather than more expensive.
- Plate manufacturing and specialty plate fees, and county administrative charges added at the treasurer's office.
- Gross vehicle weight fees, which apply to trucks rather than the light passenger vehicles modeled here.
- Negative equity, GAP insurance, extended warranties, and aftermarket add-ons, unless you fold them into the vehicle price yourself.
Common Pitfalls
- Expecting a tax line and assuming the quote is wrong when it is missing. A Montana buyer's order with no sales tax on it is correct. If you see one, ask what it is, because it is not a Montana state or local sales tax.
- Registering out of state and expecting Montana rules to follow you. Montana's no-tax treatment applies to a Montana resident registering in Montana. If you move and register elsewhere, the receiving state generally charges its own use tax on the vehicle at that point.
- Treating the "Montana LLC" scheme as a consumer strategy. The widely marketed arrangement of forming a Montana LLC to register an expensive vehicle is aimed at buyers who live in other states, and several of those states now pursue it as tax evasion. It is not modeled here and it has nothing to do with an ordinary Montana resident buying a car.
- Assuming registration is annual forever. Once a light vehicle passes 11 years, the $28 permanent registration is a one-time payment, not a recurring one.
- Assuming no sales tax means no county charge. The local option motor vehicle tax is real where a county has adopted it, and it is value based, so it is the one Montana charge that scales with what you paid.
- Judging a loan by the monthly payment. Stretching this $30,453.00 balance from 60 to 72 months drops the payment to $522.86 and raises total finance charges from $5,943.29 to $7,192.66.
Frequently Asked Questions
Does Montana charge sales tax on a car?
How much is vehicle registration in Montana?
Does a trade-in save me anything on tax in Montana?
What is the Montana county option motor vehicle tax?
Is there a luxury car fee in Montana?
Is the dealer documentation fee capped in Montana?
Sources
- Consumer Financial Protection Bureau, Truth in Lending Act (Regulation Z, 12 CFR § 1026.22) disclosure requirements for installment credit. ecfr.gov/current/title-12/chapter-X/part-1026
- Montana Department of Revenue, the official state tax authority for Montana rates, rules and forms. mtrevenue.gov
Also consulted: MCA 61-3-321 (light vehicle registration fees, age banded at $217, $87, and a one-time $28) and MCA 61-3-562; MCA 61-3-537 (county local option motor vehicle tax, capped at 0.7% of the value determined under MCA 61-3-503, subject to voter approval); MCA 61-3-503 (determination of vehicle value for local option tax purposes); Montana Motor Vehicle Division, light vehicle registration and fee schedule, including the $12 certificate of title fee stated as effective through 30 June 2028; Montana Legislature, published Montana Code Annotated text confirming the absence of a general sales or use tax; Experian, State of the Automotive Finance Market, Q1 2026, slide 45 (average new and used auto loan APR by VantageScore 4.0 credit tier; national, no state level cut published).
The Montana MVD fee page and county treasurer sites refuse automated retrieval. The registration amounts and the $825 luxury fee come from secondary summaries of the official MVD schedule and a legislative fiscal brochure, and should be confirmed with your county treasurer before you rely on them. No county option tax rate is published on this page because none could be verified.