How much UK inheritance tax is due on a typical estate?
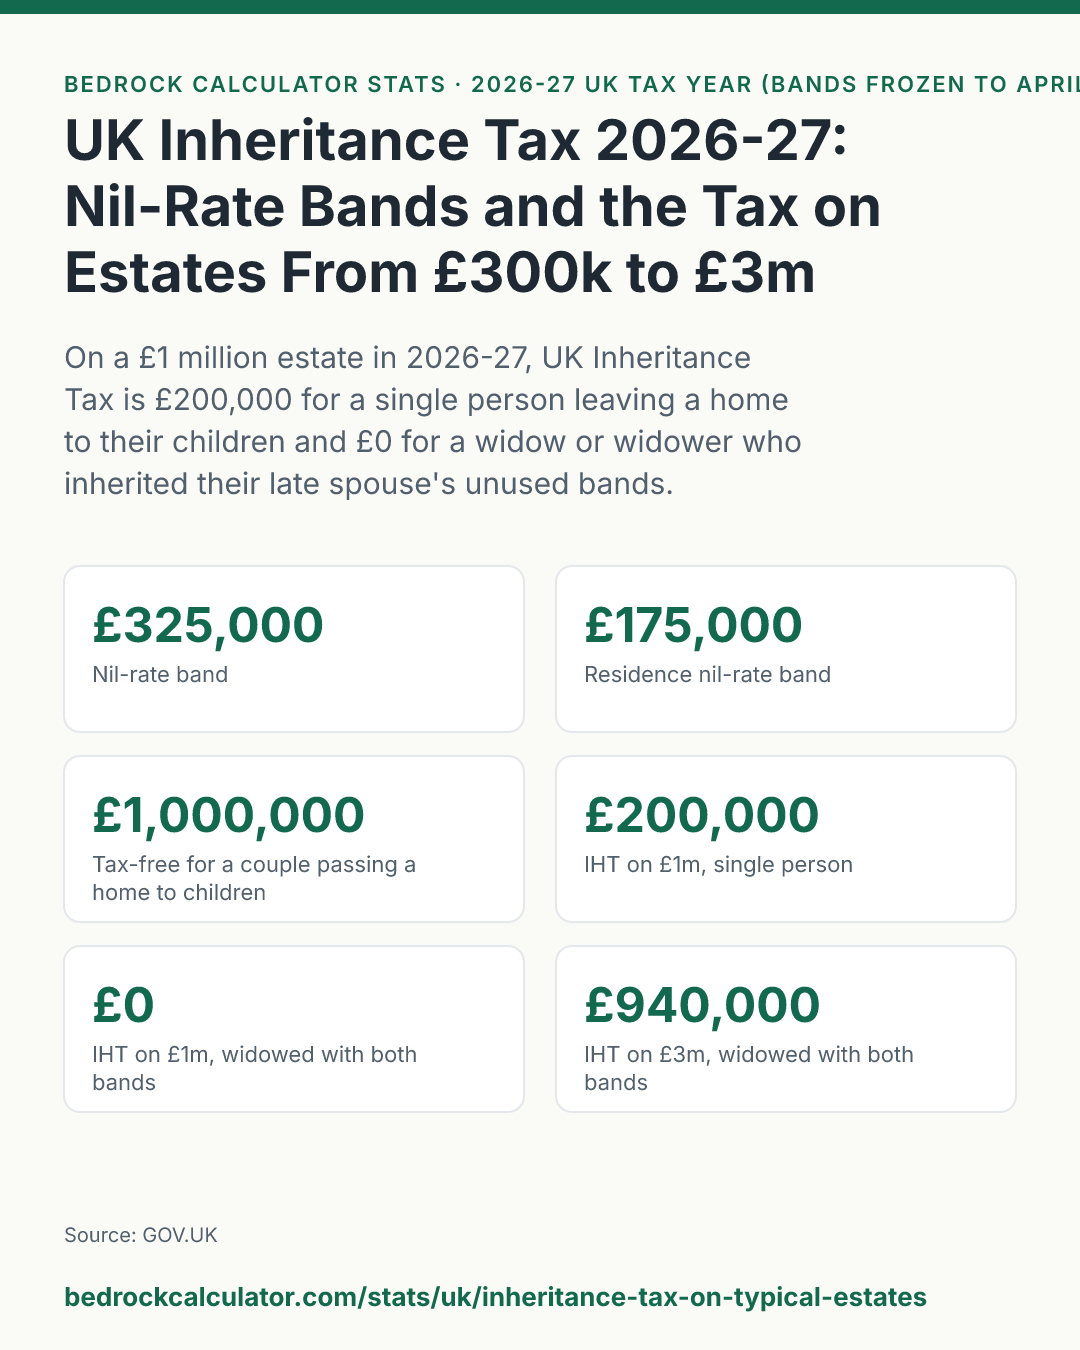
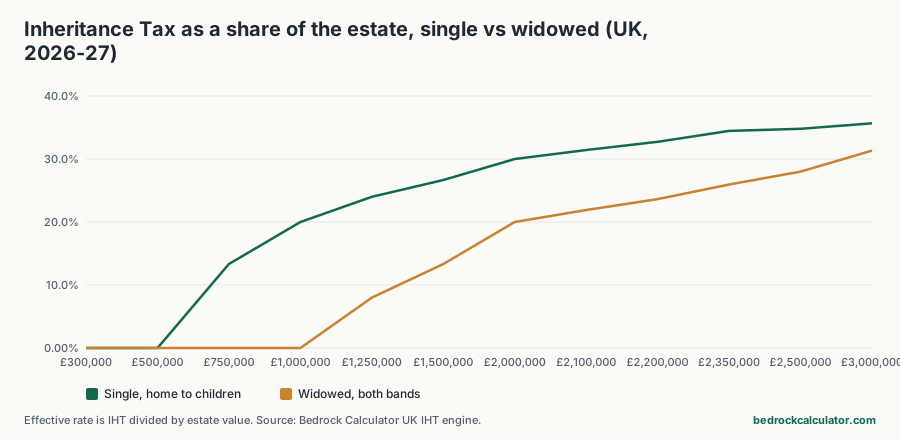
Most UK estates still pay no Inheritance Tax, but the line is lower than many families think, and the bands haven't moved for years. In the 2026-27 tax year a single person who leaves their home to their children can pass on £500,000 before any tax is due. On a £1 million estate the bill is £200,000.
A widow or widower whose late spouse left everything to them can usually use both sets of bands. That raises the tax-free amount to £1,000,000, and the same £1 million estate pays £0.
How we worked out these numbers
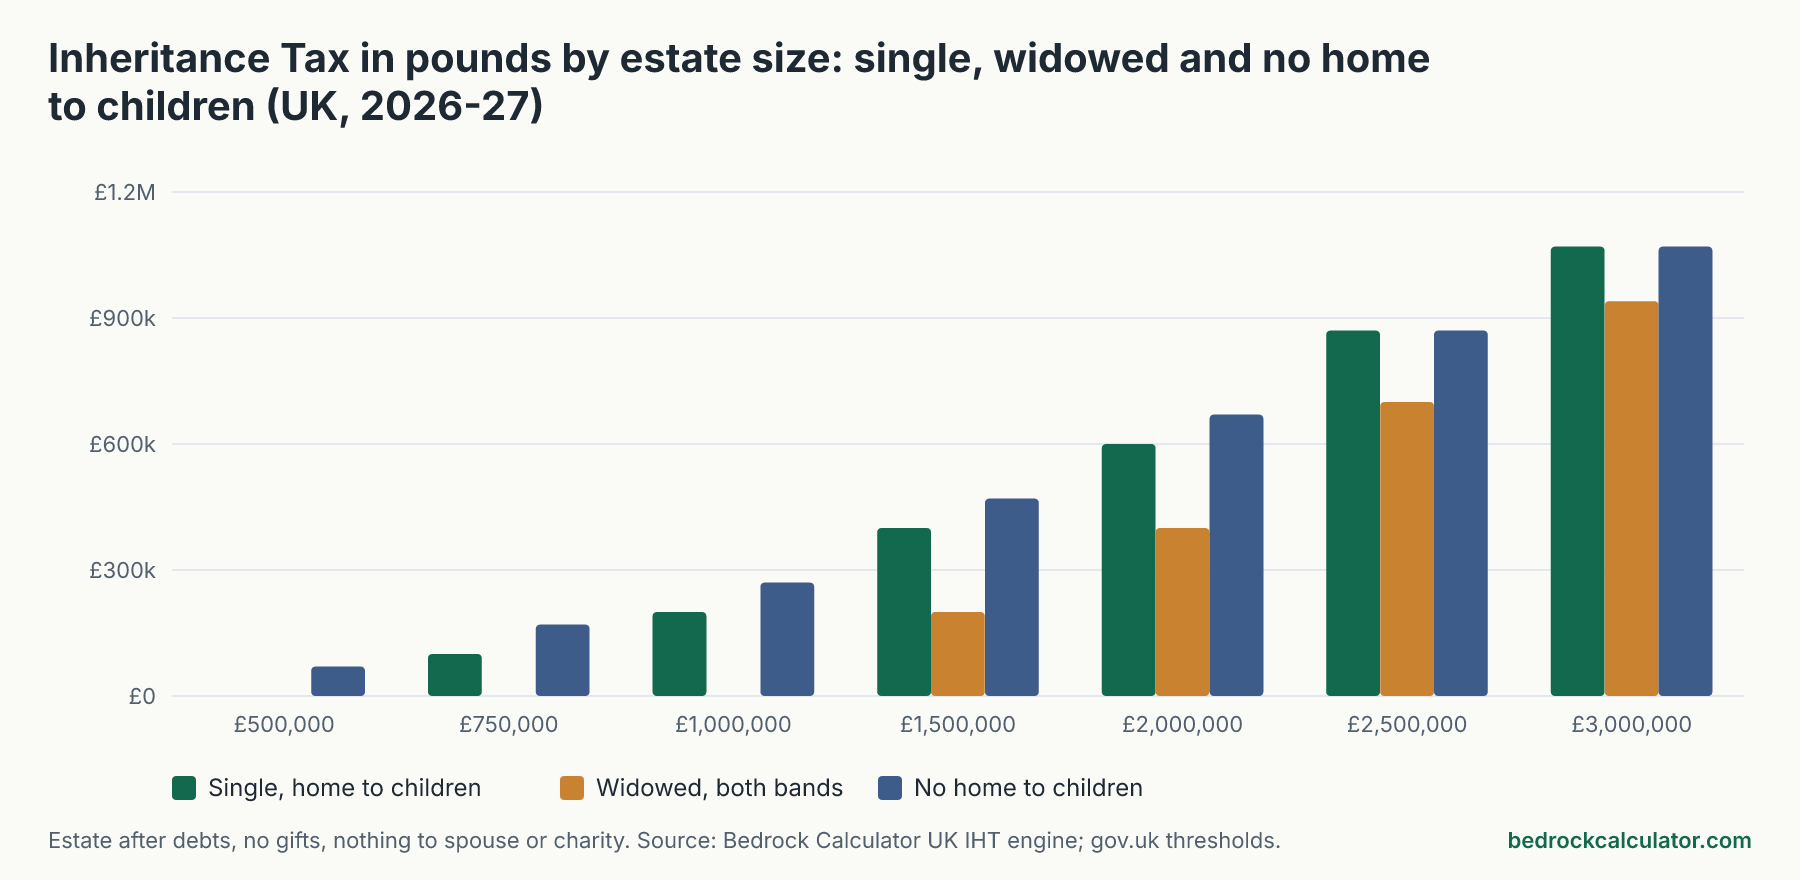
We ran the UK Inheritance Tax calculator on this site at twelve estate values from £300,000 to £3,000,000, in three situations:
- Single, home to children. One person, no allowances inherited from a spouse, whose estate includes a home passing to children or grandchildren.
- Widowed, both bands transferred. The same, plus all of a late spouse's unused nil-rate band and residence nil-rate band.
- No home to children. One person whose home doesn't pass to direct descendants, perhaps because they rent, or because the home goes to a nephew or a friend.
In every run the estate value is what's left after debts and funeral costs, nothing is left to a spouse or charity on this death, and there are no gifts in the previous seven years.
The calculator applies the £325,000 nil-rate band, the £175,000 residence nil-rate band, the taper on estates over £2,000,000, and the standard rate. The residence band can never be more than the value of the home passing to the children, and the calculator caps it there. For these figures we assume a home worth £350,000, enough for the full band even when a late spouse's band is added. If the home being left is worth less, the band is smaller and the bill is higher, which you can check by entering your home's value in the calculator.
It also leaves out several things that often matter in practice: lifetime gifts and taper relief, trusts, Business and Agricultural Property Relief, jointly owned property passing outside the will, and the change from 6 April 2027 that brings most unused pension pots into the estate. That pension change doesn't apply in 2026-27, but anyone planning ahead should allow for it.
Inheritance tax on every estate size, side by side
Click any column heading to sort. All amounts are in pounds.
UK Inheritance Tax 2026-27 on estates from £300,000 to £3m
Download CSVEstate value after debts, in pounds. Nothing left to a spouse or charity on this death, no lifetime gifts. Widowed means 100% of a late spouse's unused nil-rate and residence nil-rate bands transferred. England and Wales rules (the same across the UK).
| £300,000 | £0 | £0 | £0 | £1,000,000 | 0.0% |
| £500,000 | £0 | £0 | £70,000 | £1,000,000 | 0.0% |
| £750,000 | £100,000 | £0 | £170,000 | £1,000,000 | 13.3% |
| £1,000,000 | £200,000 | £0 | £270,000 | £1,000,000 | 20.0% |
| £1,250,000 | £300,000 | £100,000 | £370,000 | £1,000,000 | 24.0% |
| £1,500,000 | £400,000 | £200,000 | £470,000 | £1,000,000 | 26.7% |
| £2,000,000 | £600,000 | £400,000 | £670,000 | £1,000,000 | 30.0% |
| £2,100,000 | £660,000 | £460,000 | £710,000 | £950,000 | 31.4% |
| £2,200,000 | £720,000 | £520,000 | £750,000 | £900,000 | 32.7% |
| £2,350,000 | £810,000 | £610,000 | £810,000 | £825,000 | 34.5% |
| £2,500,000 | £870,000 | £700,000 | £870,000 | £750,000 | 34.8% |
| £3,000,000 | £1,070,000 | £940,000 | £1,070,000 | £650,000 | 35.7% |
What is the inheritance tax threshold in 2026-27?
There are two bands, and they stack.
The nil-rate band of £325,000 applies to everyone. The residence nil-rate band of £175,000 applies on top only when a home the person lived in passes to their children, stepchildren, grandchildren or other direct descendants. Together that's £500,000.
Without a home going to descendants, only the first band applies, so the threshold is £325,000. That difference is easy to miss. On a £500,000 estate, leaving the home to children means no tax; leaving it elsewhere means £70,000. At £1,000,000, the residence band is worth £70,000 to the family.
Inheritance tax on a £1 million estate
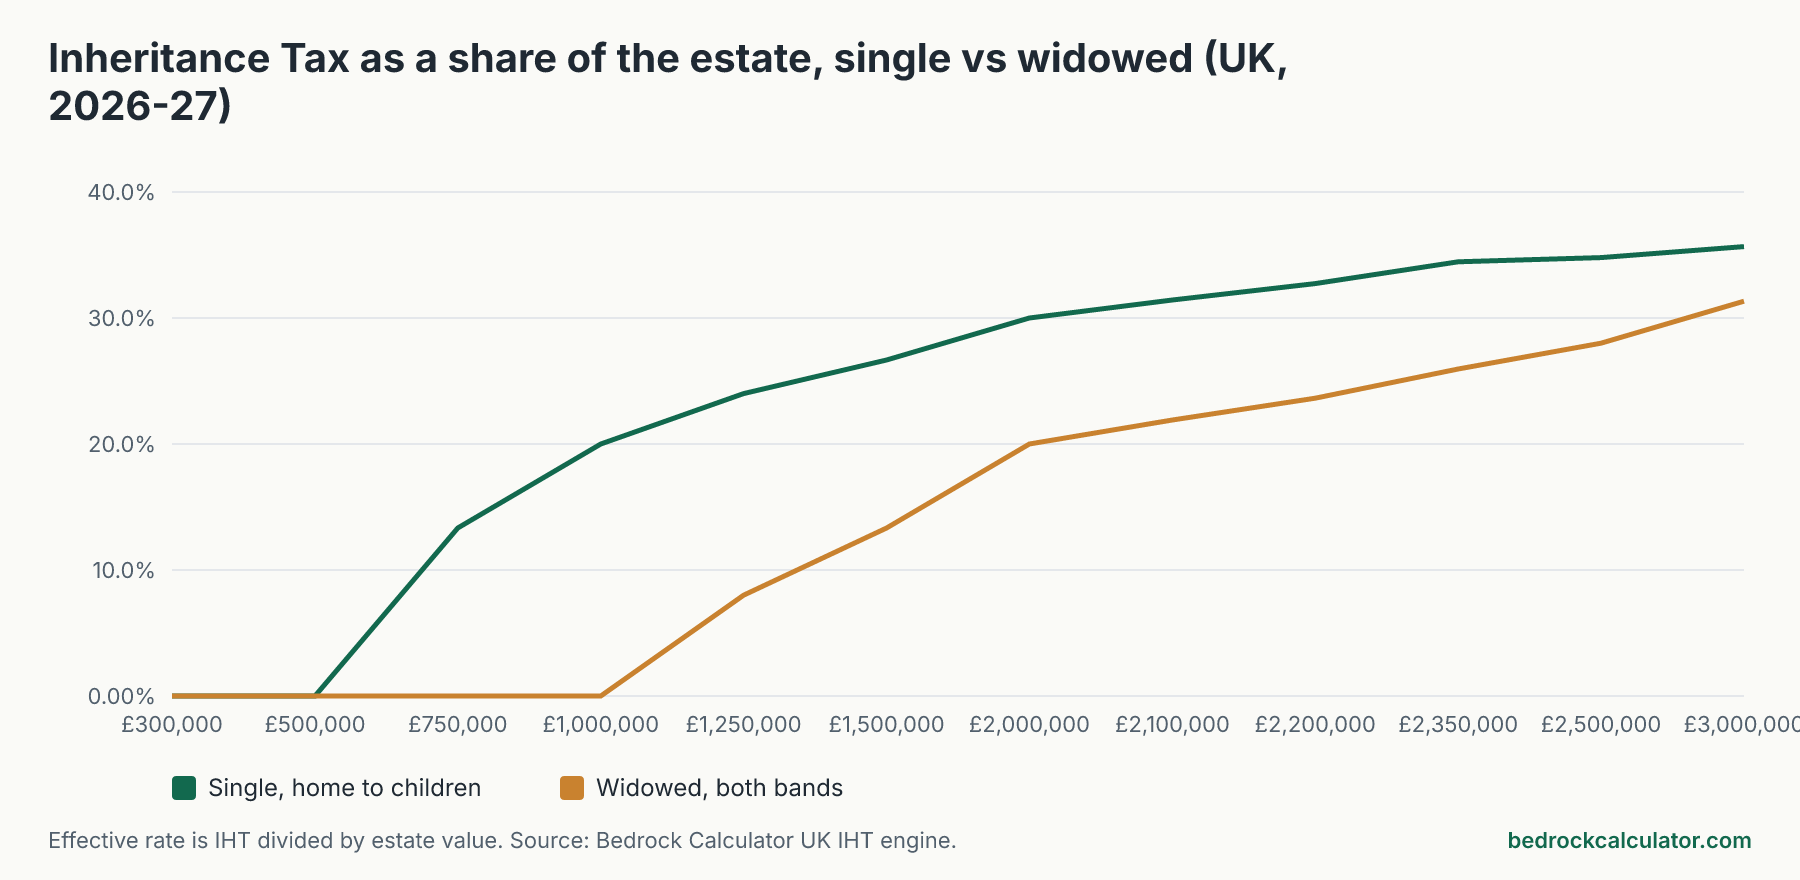
On £1,000,000 a single person leaving a home to their children pays £200,000, which is 20.0% of the estate. Their children receive £800,000.
For a widow or widower with both sets of bands, the same estate sits exactly at the £1,000,000 limit and pays £0. That's why a married couple who leave everything to each other on the first death, then to their children on the second, can usually pass on a £1 million family home and savings without Inheritance Tax.
Estates over £2 million and the residence band taper
The residence band shrinks once the estate passes £2,000,000. It falls by £1 for every £2 above that line, until it's gone. While it's shrinking, each extra pound of estate does two things: it's taxed, and it also pulls another 50p of previously tax-free estate into tax.
For a widowed person with both residence bands, the effect is sharp. Tax rises from £400,000 at £2,000,000 to £610,000 at £2,350,000. That's £210,000 of extra tax on a £350,000 slice of estate, an effective rate of 60.0%. By £2,350,000 the available bands have fallen to £825,000.
By £3,000,000 the estate pays £940,000 even with both spouses' bands, or 31.3% of everything. A single person with the same estate pays £1,070,000.
How families usually reduce the bill
Using the spouse exemption. Anything left to a spouse or civil partner is free of Inheritance Tax, and their unused bands pass to the survivor. The table shows how much that's worth.
Leaving the home to direct descendants. The residence band only applies when the home goes to children or grandchildren, so the wording of the will matters.
Giving earlier. Gifts made more than seven years before death usually fall outside the estate. Gifts within seven years may still be taxed, with taper relief after three years. The calculator doesn't model gifts.
Charity. Leaving at least a tenth of the taxable estate to charity cuts the rate on the rest. You can test that in the Inheritance Tax calculator by entering a charitable gift.
Getting your own figure
Put your own estate value, debts, spouse and charity figures into the Inheritance Tax calculator. If the estate includes shares or a second property that might be sold, the UK Capital Gains Tax calculator shows the tax on a sale during your lifetime, which is often part of the same planning conversation. For a large estate with a business, farm or trust, take professional advice.