How big a tax refund does an RRSP contribution give in each province?
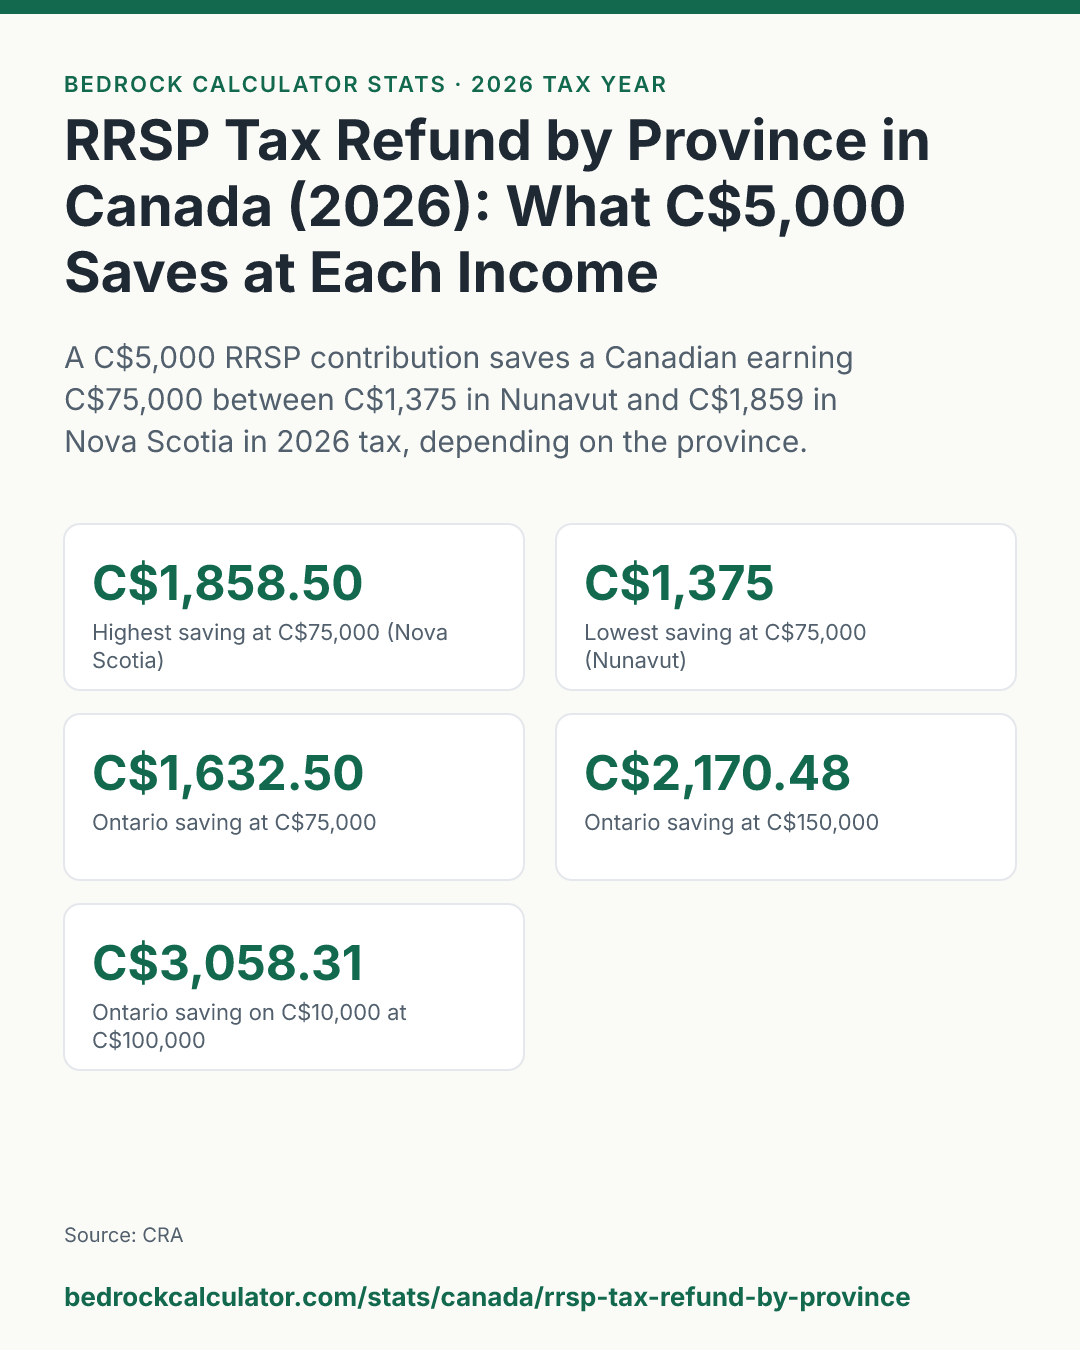
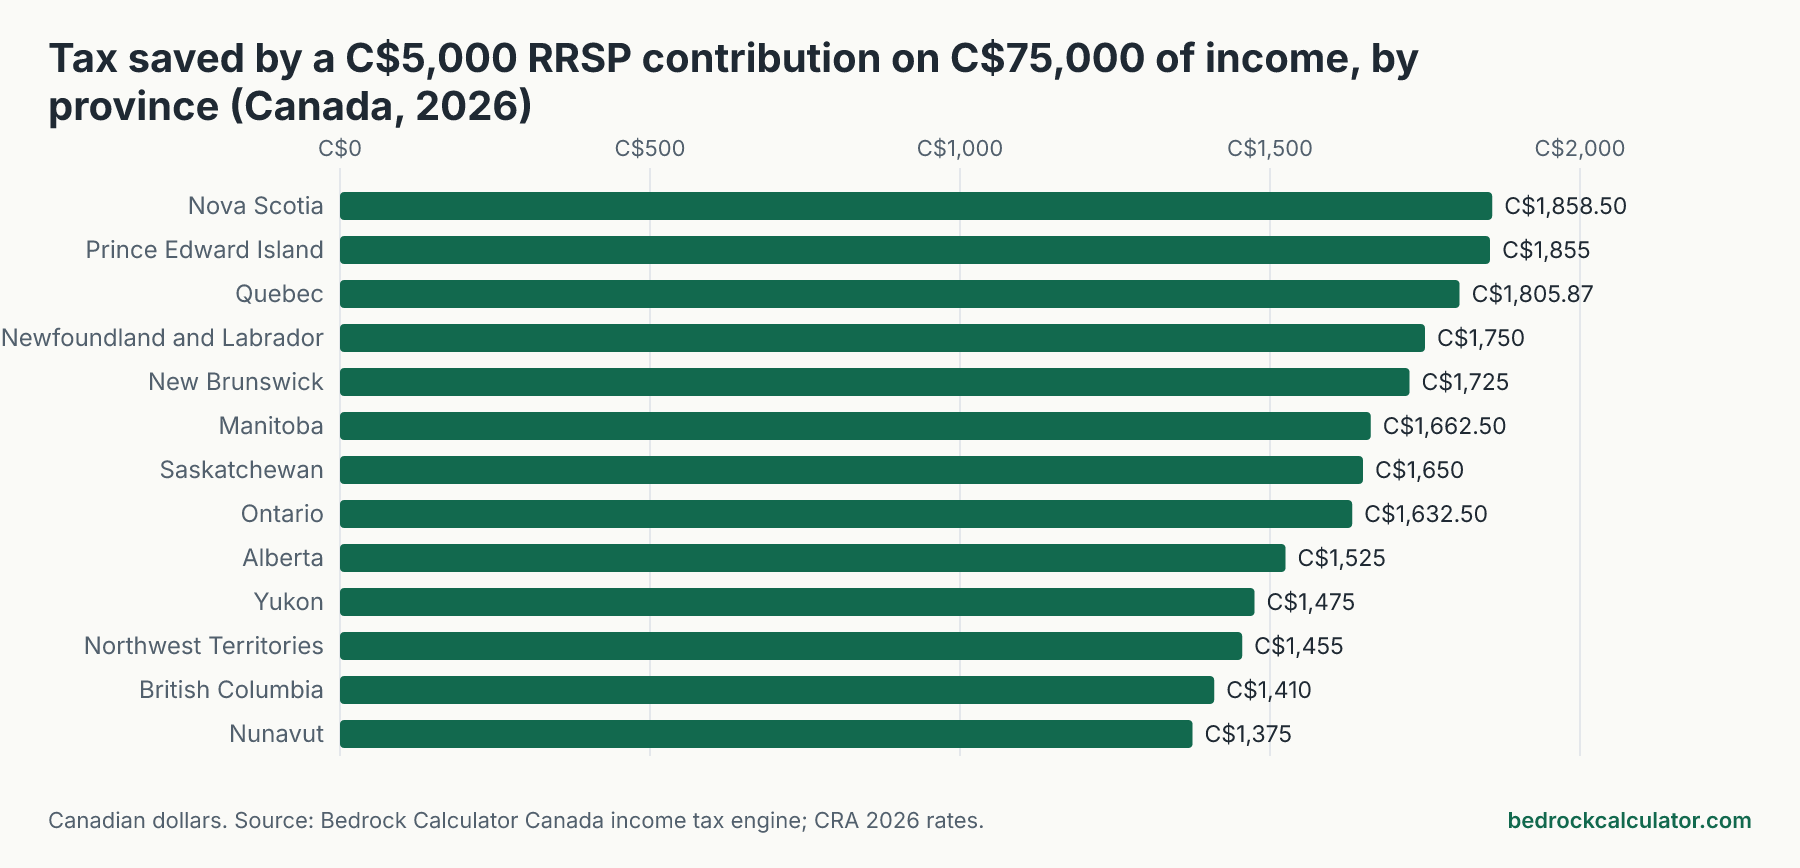
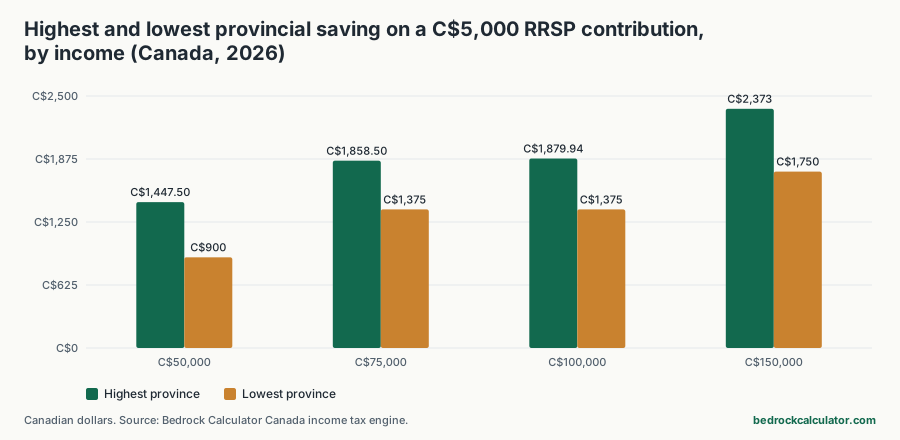
An RRSP contribution comes off your taxable income, so it's worth whatever tax you'd otherwise have paid on that slice of income. That depends on where you live. For someone earning C$75,000 in 2026, a C$5,000 contribution saves C$1,858.50 in Nova Scotia but only C$1,375 in Nunavut, a difference of C$483.50.
In Ontario the same contribution saves C$1,102.50 at C$50,000, C$1,632.50 at C$75,000, C$1,574 at C$100,000 and C$2,170.48 at C$150,000.
How we worked out these numbers
We didn't multiply the contribution by a marginal rate. We ran the Canada income tax calculator on this site twice for every province and territory at each income: once on the full income, and once on the income less C$5,000. The RRSP saving is the difference between the two tax bills.
Doing it that way catches the things a single rate misses. If the deduction crosses a bracket edge, part of it is worth the higher rate and part the lower. In Ontario it also picks up the surtax and the Ontario Health Premium, both of which the calculator applies. In Quebec it includes the abatement that reduces federal tax for Quebec residents.
The calculator uses 2026 federal, provincial and territorial brackets and basic personal amounts from CRA. It treats the income you enter as taxable income, so these figures are for someone whose only deduction is the RRSP contribution.
The saving in every province and territory
Click any column heading to sort. All figures are the 2026 tax saved by a C$5,000 contribution, in Canadian dollars.
Tax saved by a C$5,000 RRSP contribution in 2026, by province and income (Canadian dollars)
Download CSVDrop in 2026 federal plus provincial or territorial income tax when taxable income falls by C$5,000. Basic personal amounts only; Ontario surtax and health premium and the Quebec abatement included.
| Nova Scotia | C$1,447.50 | C$1,858.50 | C$1,879.94 | C$2,175 |
| Prince Edward Island | C$1,373.50 | C$1,855 | C$1,855 | C$2,250 |
| Quebec | C$1,284.50 | C$1,805.87 | C$1,805.88 | C$2,373 |
| Newfoundland and Labrador | C$1,425 | C$1,750 | C$1,815 | C$2,090 |
| New Brunswick | C$1,170 | C$1,725 | C$1,725 | C$2,100 |
| Manitoba | C$1,298.50 | C$1,662.50 | C$1,662.50 | C$2,170 |
| Saskatchewan | C$1,225 | C$1,650 | C$1,650 | C$1,925 |
| Ontario | C$1,102.50 | C$1,632.50 | C$1,574 | C$2,170.48 |
| Alberta | C$1,100 | C$1,525 | C$1,525 | C$1,800 |
| Yukon | C$1,020 | C$1,475 | C$1,475 | C$1,845 |
| Northwest Territories | C$995 | C$1,455 | C$1,455 | C$1,910 |
| British Columbia | C$980 | C$1,410 | C$1,410 | C$2,035 |
| Nunavut | C$900 | C$1,375 | C$1,375 | C$1,750 |
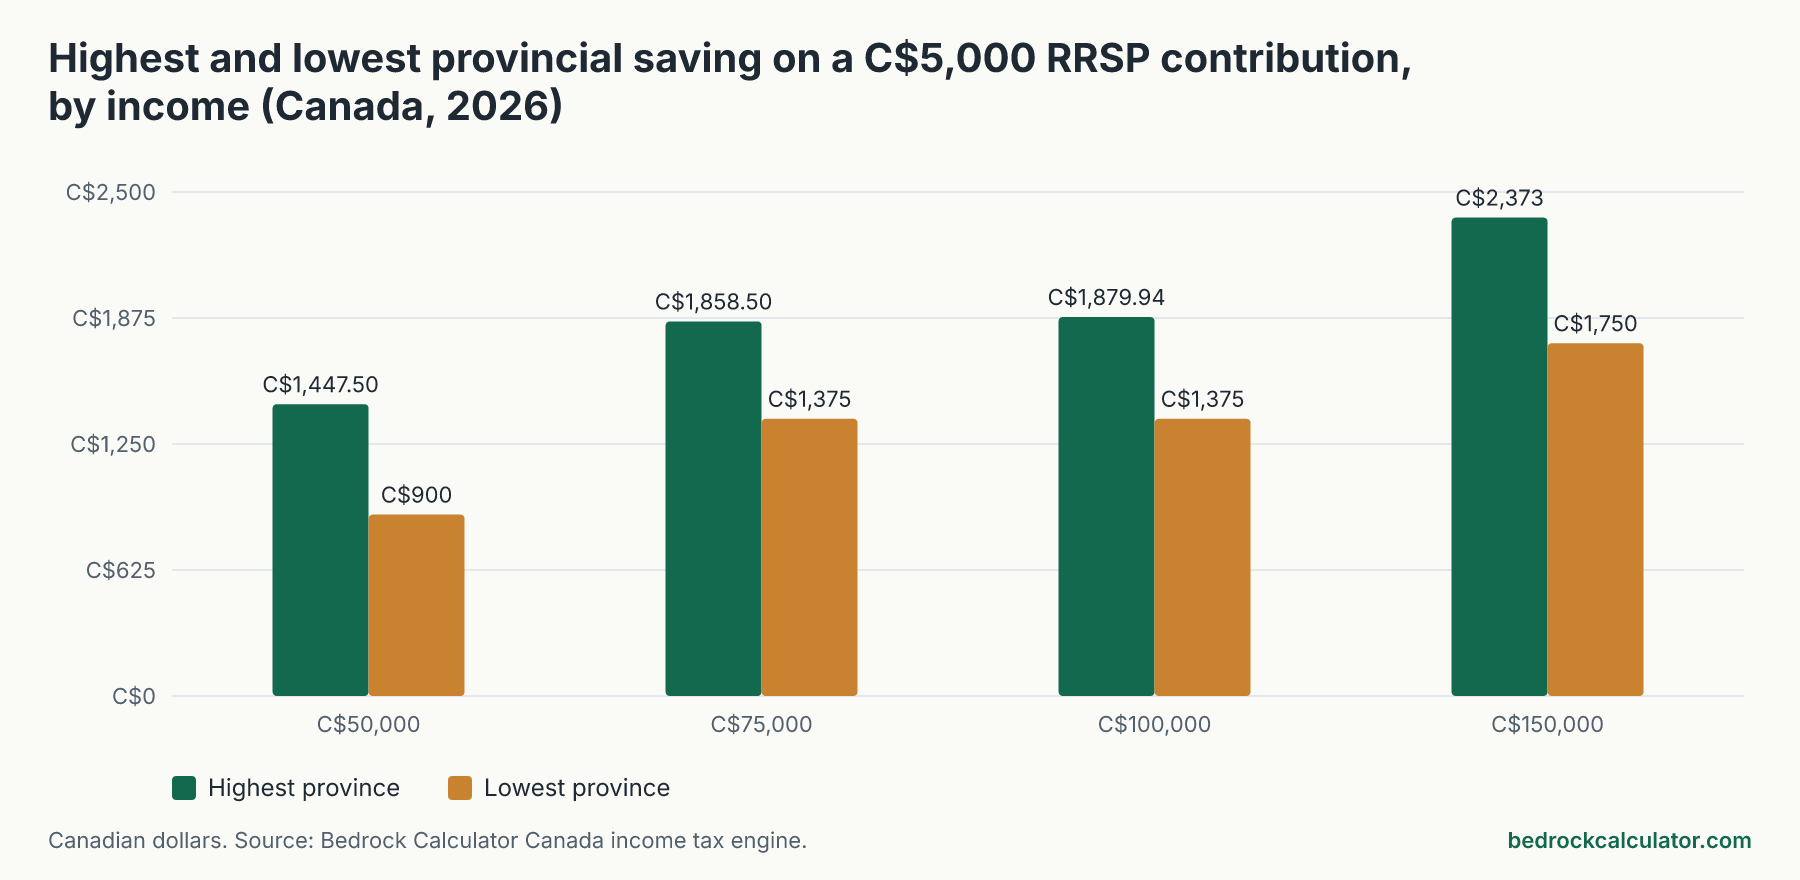
A few patterns stand out. Nunavut gives the smallest saving at every income in the table, because its territorial rates on these incomes are the lowest. Nova Scotia is at or near the top at the lower incomes. At C$150,000 the highest saving is in Quebec, at C$2,373, because Quebec's provincial rates are high even after the federal abatement.
Alberta and British Columbia sit in the lower half at C$75,000, at C$1,525 and C$1,410. Quebec is near the top at C$1,805.87.
Why the refund grows with income, mostly
Canada's federal and provincial brackets both rise with income, so the same contribution comes off a more heavily taxed slice the more you earn. In the lowest-saving province the figure goes from C$900 at C$50,000 to C$1,750 at C$150,000. In the highest-saving province it goes from C$1,447.50 to C$2,373.
It doesn't always rise in a straight line, though. In Ontario the saving at C$75,000 is C$1,632.50, slightly more than the C$1,574 at C$100,000. That's the Ontario Health Premium at work: it steps up over a narrow income range just below C$75,000, so a deduction that pulls income back across that range saves the premium as well as the tax.
Is the refund just your marginal rate?
It's close, but you can be out by a fair amount. The RRSP calculator on this site estimates the saving as your contribution times a combined marginal rate that you type in. For Ontario at C$75,000, the income tax calculator reports a combined marginal rate of 29.65%, which would give C$1,482.50 on C$5,000.
The full before-and-after calculation gives C$1,632.50, because of the health premium step.
The bigger the contribution, the more the two methods can drift apart. In Ontario at C$100,000, a C$10,000 contribution saves C$3,058.31, or 30.6% of what you put in, because the second half of it reaches down into income taxed at a lower combined rate.
A tax saving is not quite the same as a refund
What these figures show is how much less tax you owe for 2026. Whether that arrives as a cheque depends on how much was withheld from your pay during the year. If your employer already reduces withholding because you contribute through a group RRSP at work, you've been getting the saving all year and won't see it again at tax time.
What these figures leave out
The income tax calculator applies the main rules and not every credit. It doesn't model:
- Credits other than the basic personal amount, such as the Canada employment amount, CPP and EI credits, the age amount, tuition, medical expenses and donations.
- Low-income reductions outside Ontario and British Columbia, so tax at modest incomes in Nova Scotia, Newfoundland and Labrador, Prince Edward Island, New Brunswick and Manitoba is somewhat overstated.
- Quebec's own deductions and credits beyond its brackets and basic personal amount.
- Benefits that depend on net income, such as the Canada Child Benefit and the GST/HST credit. An RRSP deduction raises these too, which can make it worth more than the tax saving alone.
The RRSP side has its own limits. These figures assume you have the room: new 2026 room is 18% of your 2025 earned income up to the C$33,810 dollar limit, plus any unused room carried forward, less any pension adjustment from a workplace pension. The TFSA, RRSP and FHSA limits page shows the 2026 numbers.
Run your own numbers
Put your own taxable income and province into the Canada income tax calculator, then try it again less your planned contribution. The difference is your saving. To project what the RRSP grows to by retirement, use the RRSP calculator. If you're weighing an RRSP against a TFSA, our TFSA vs RRSP comparison works through it at different tax rates, and the take-home pay calculator shows the effect on each paycheque.