What are the 2026 TFSA, RRSP and FHSA limits in Canada?
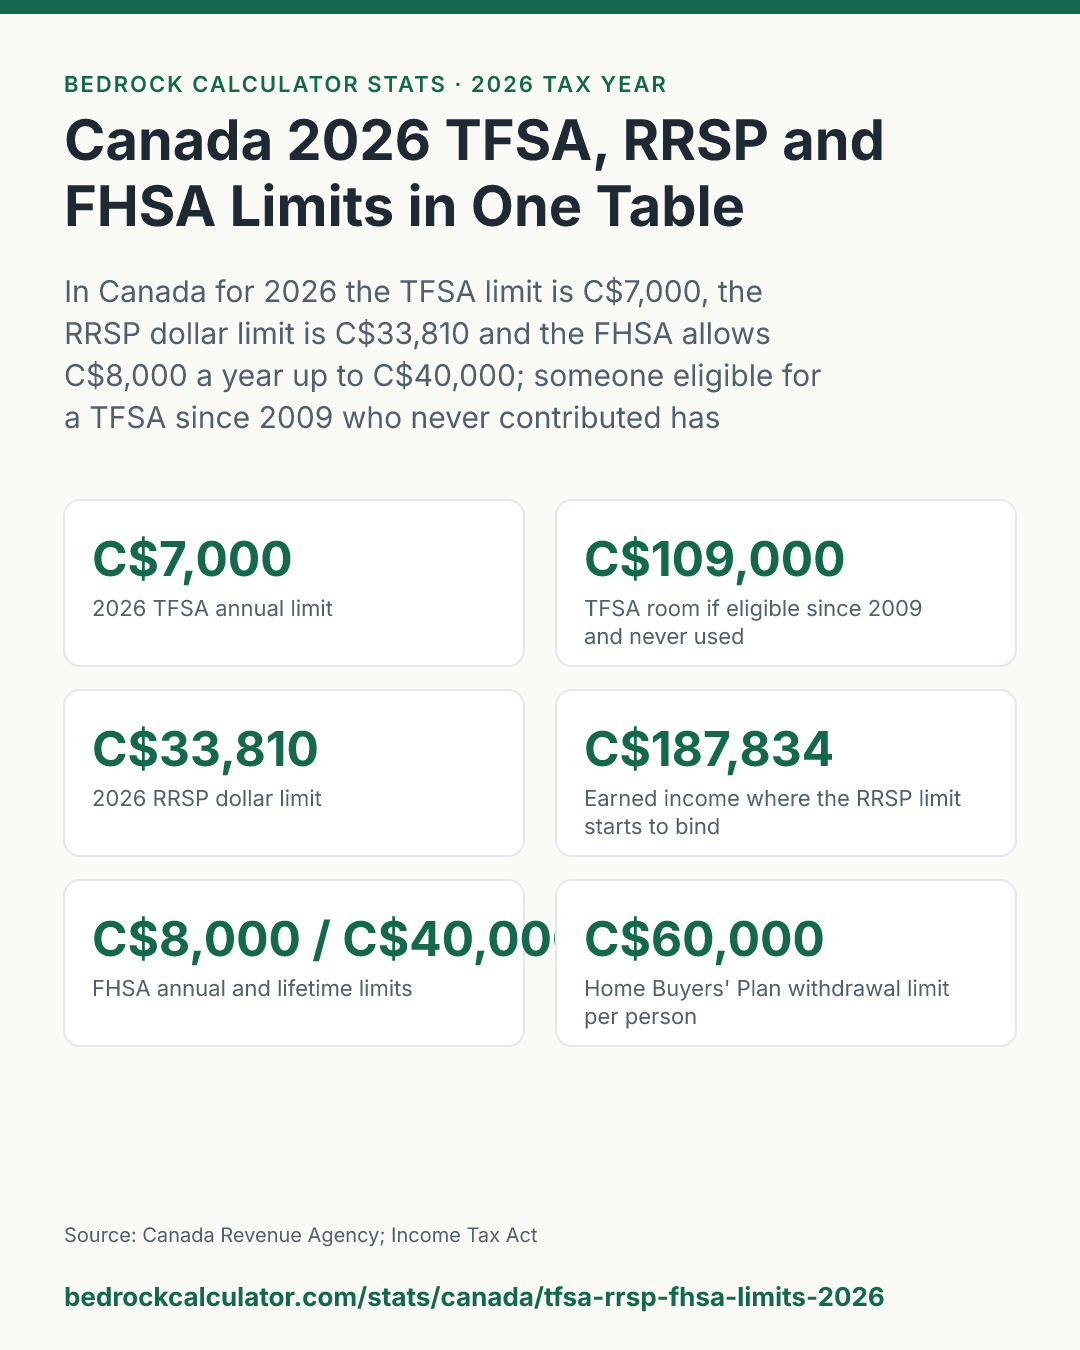
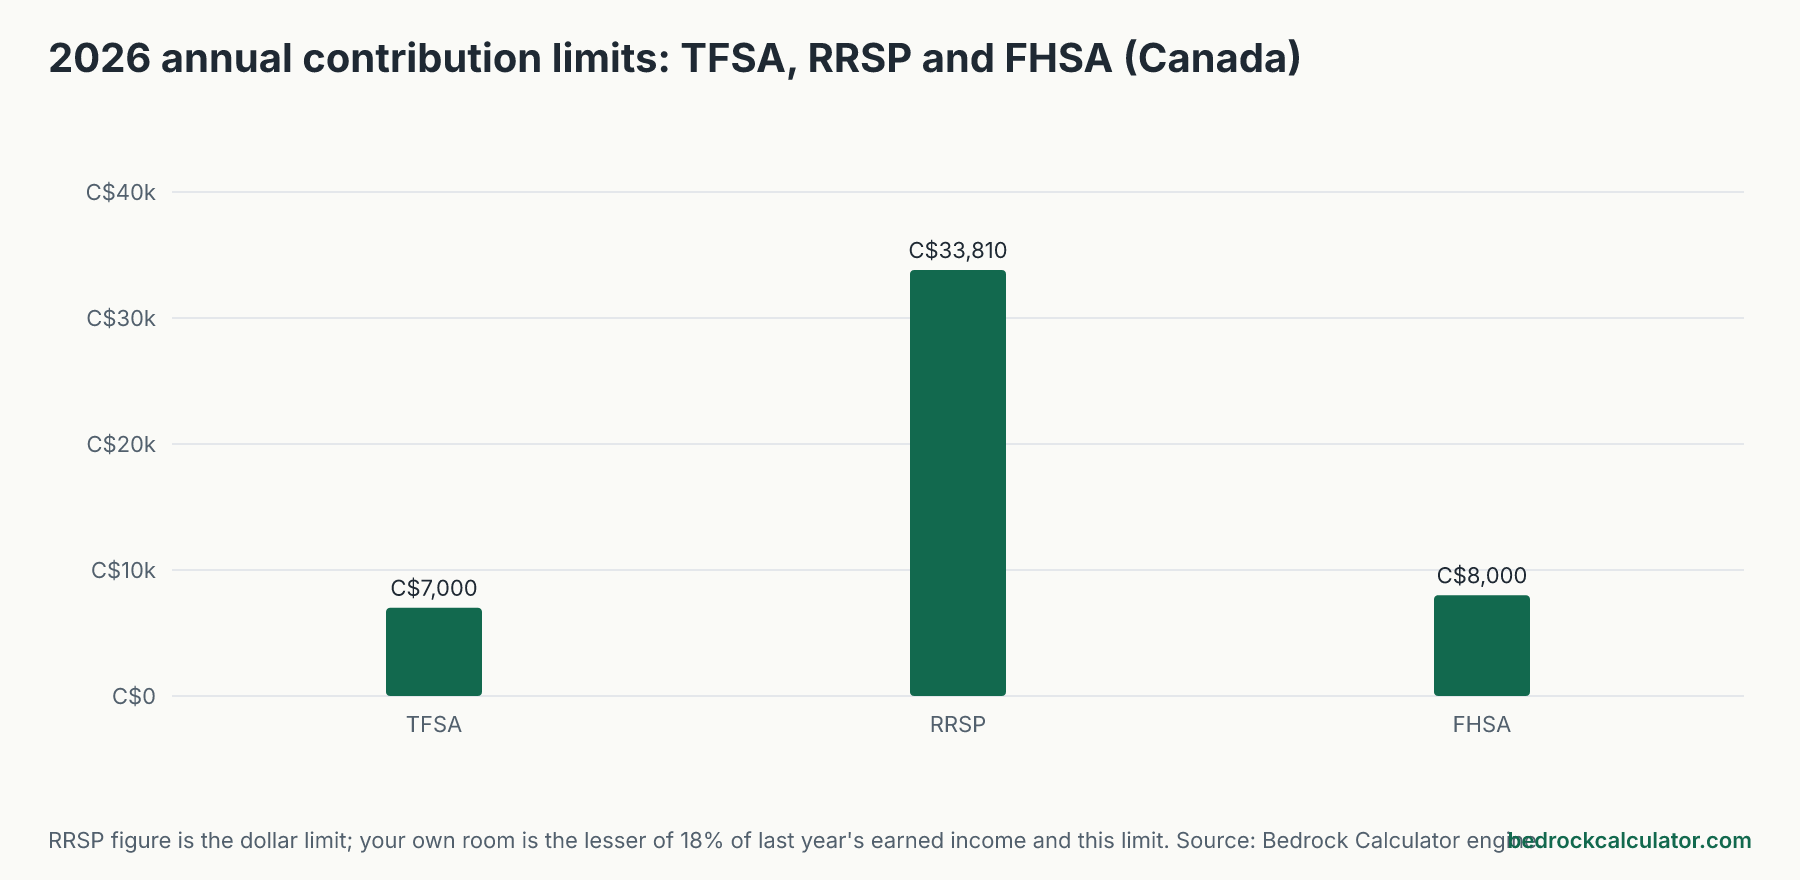
For 2026 in Canada, the TFSA limit is C$7,000, the RRSP dollar limit is C$33,810, and the FHSA lets you put in C$8,000 a year up to a lifetime total of C$40,000. If you were 18 or older when the TFSA started in 2009 and you've never put a dollar in, you have C$109,000 of TFSA room waiting.
The RRSP number is the one people misread most. C$33,810 is a ceiling, not your allowance. Your own new room is 18% of last year's earned income, and the ceiling only matters once that income reaches C$187,834.
Every 2026 limit in one place
Here are the four numbers most Canadian savers need this year, with the rule for what happens to room you don't use. The Home Buyers' Plan isn't an account of its own, but it sets how much RRSP money you can borrow for a first home, so it belongs on the same page.
Canada registered account limits for 2026 (Canadian dollars)
Download CSVAnnual limit, lifetime or cumulative ceiling, and the carry-forward rule for each account. Figures from the Bedrock Calculator engine.
| FHSA | C$8,000 | C$40,000 | At most one year of unused room carries forward, and only once the account is open |
| Home Buyers' Plan (RRSP withdrawal) | n/a | C$60,000 | Per person; repaid to the RRSP over 15 years |
| RRSP | C$33,810 | n/a | 18% of last year's earned income up to the dollar limit; unused room carries forward |
| TFSA | C$7,000 | C$109,000 | All unused room carries forward with no cap; withdrawals are added back the next January |
n/a means the column does not apply to that row.
How we got these numbers
Nothing on this page was typed in by hand. Each figure comes from the tables and calculators this site already runs: the TFSA calculator for annual TFSA limits and cumulative room, the RRSP calculator for the dollar limit and the 18% rule, the FHSA calculator for the annual, carry-forward and lifetime limits, and the first-time home buyer calculator for the Home Buyers' Plan cap. We checked the TFSA and RRSP dollar limits against the CRA's own limits table, and the FHSA and Home Buyers' Plan amounts are written into the Income Tax Act itself.
What this page doesn't cover: pension adjustments that shrink RRSP room for people in a workplace pension, the RRSP over-contribution buffer, and the penalty tax on excess TFSA or FHSA contributions. If you belong to a defined benefit or money purchase pension plan, your RRSP room will be lower than the figures below, and your Notice of Assessment is the only reliable source for it.
TFSA: C$7,000 this year, and more room than most people think
The TFSA dollar limit stays at C$7,000 for 2026. What makes the TFSA unusual is that unused room never expires. Every year's limit since you became eligible piles up, and anything you withdraw is added back to your room on 1 January of the following year.
So the real question is usually "how much room do I have in total?" That depends on the year you turned 18, because room only starts building from 18 or from 2009, whichever came later. If you have never contributed:
- Eligible since 2009: C$109,000
- Turned 18 in 2015: C$78,000
- Turned 18 in 2020: C$45,500
- Turning 18 in 2026: C$7,000
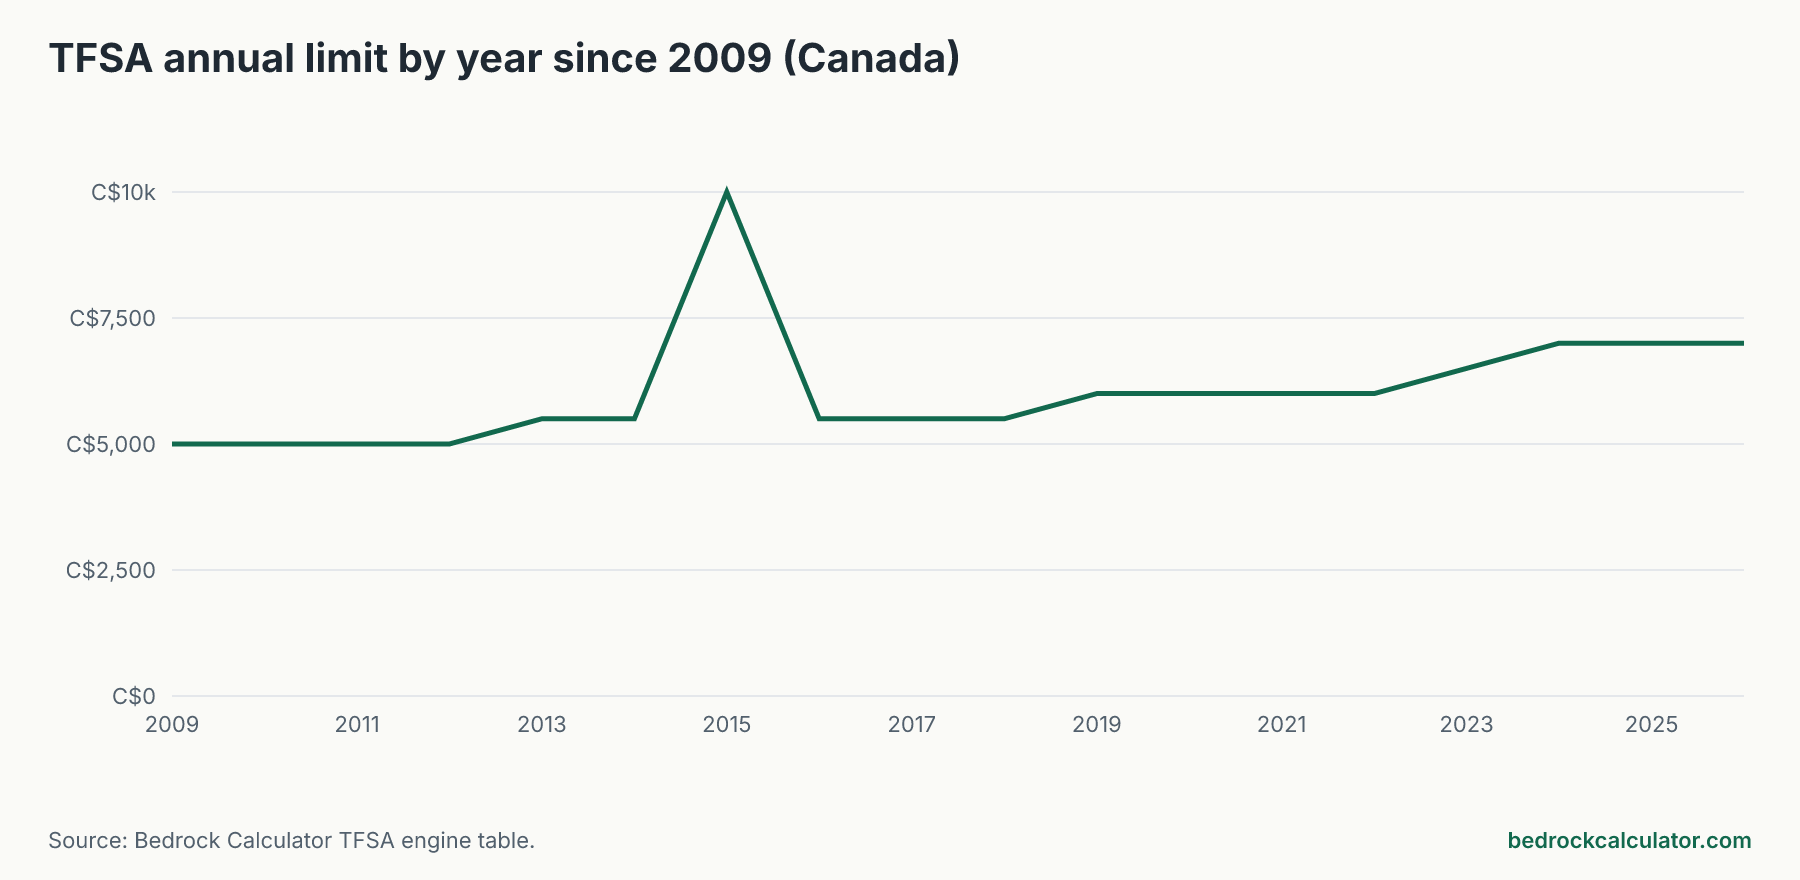
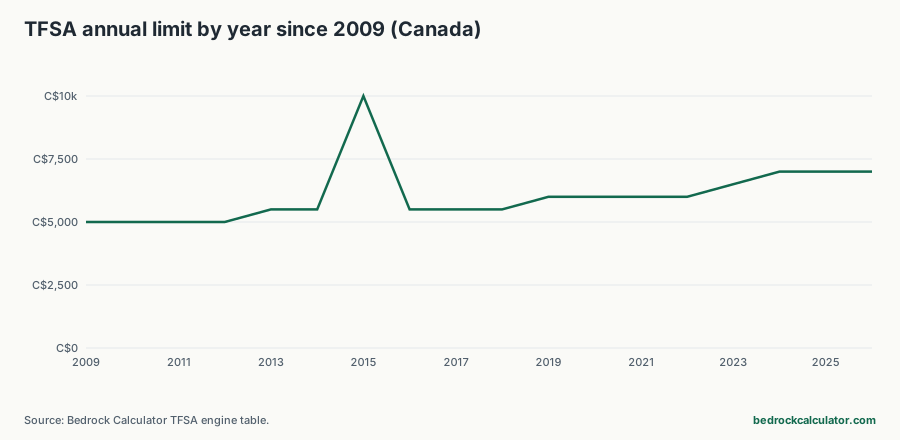
The limit has moved around since the account started. It began at C$5,000, jumped to C$10,000 for 2015 only, then dropped back and has crept up with inflation since.
The full year-by-year list is below, with the running total for someone who has been eligible from the start.
TFSA annual dollar limit by year, 2009 to 2026 (Canadian dollars)
Download CSVCumulative room assumes you were 18 or older in 2009 and never contributed.
| 2009 | C$5,000 | C$5,000 |
| 2010 | C$5,000 | C$10,000 |
| 2011 | C$5,000 | C$15,000 |
| 2012 | C$5,000 | C$20,000 |
| 2013 | C$5,500 | C$25,500 |
| 2014 | C$5,500 | C$31,000 |
| 2015 | C$10,000 | C$41,000 |
| 2016 | C$5,500 | C$46,500 |
| 2017 | C$5,500 | C$52,000 |
| 2018 | C$5,500 | C$57,500 |
| 2019 | C$6,000 | C$63,500 |
| 2020 | C$6,000 | C$69,500 |
| 2021 | C$6,000 | C$75,500 |
| 2022 | C$6,000 | C$81,500 |
| 2023 | C$6,500 | C$88,000 |
| 2024 | C$7,000 | C$95,000 |
| 2025 | C$7,000 | C$102,000 |
| 2026 | C$7,000 | C$109,000 |
One thing to watch: the CRA's view of your room can lag your own records, especially if you moved money between institutions. A direct transfer between TFSAs doesn't use room, but withdrawing and re-depositing in the same year does.
RRSP: why C$33,810 isn't your number
The RRSP dollar limit rose to C$33,810 for 2026, up C$1,320 from C$32,490 in 2025. Your new room for 2026 is the smaller of two figures: 18% of your 2025 earned income, or that dollar limit.
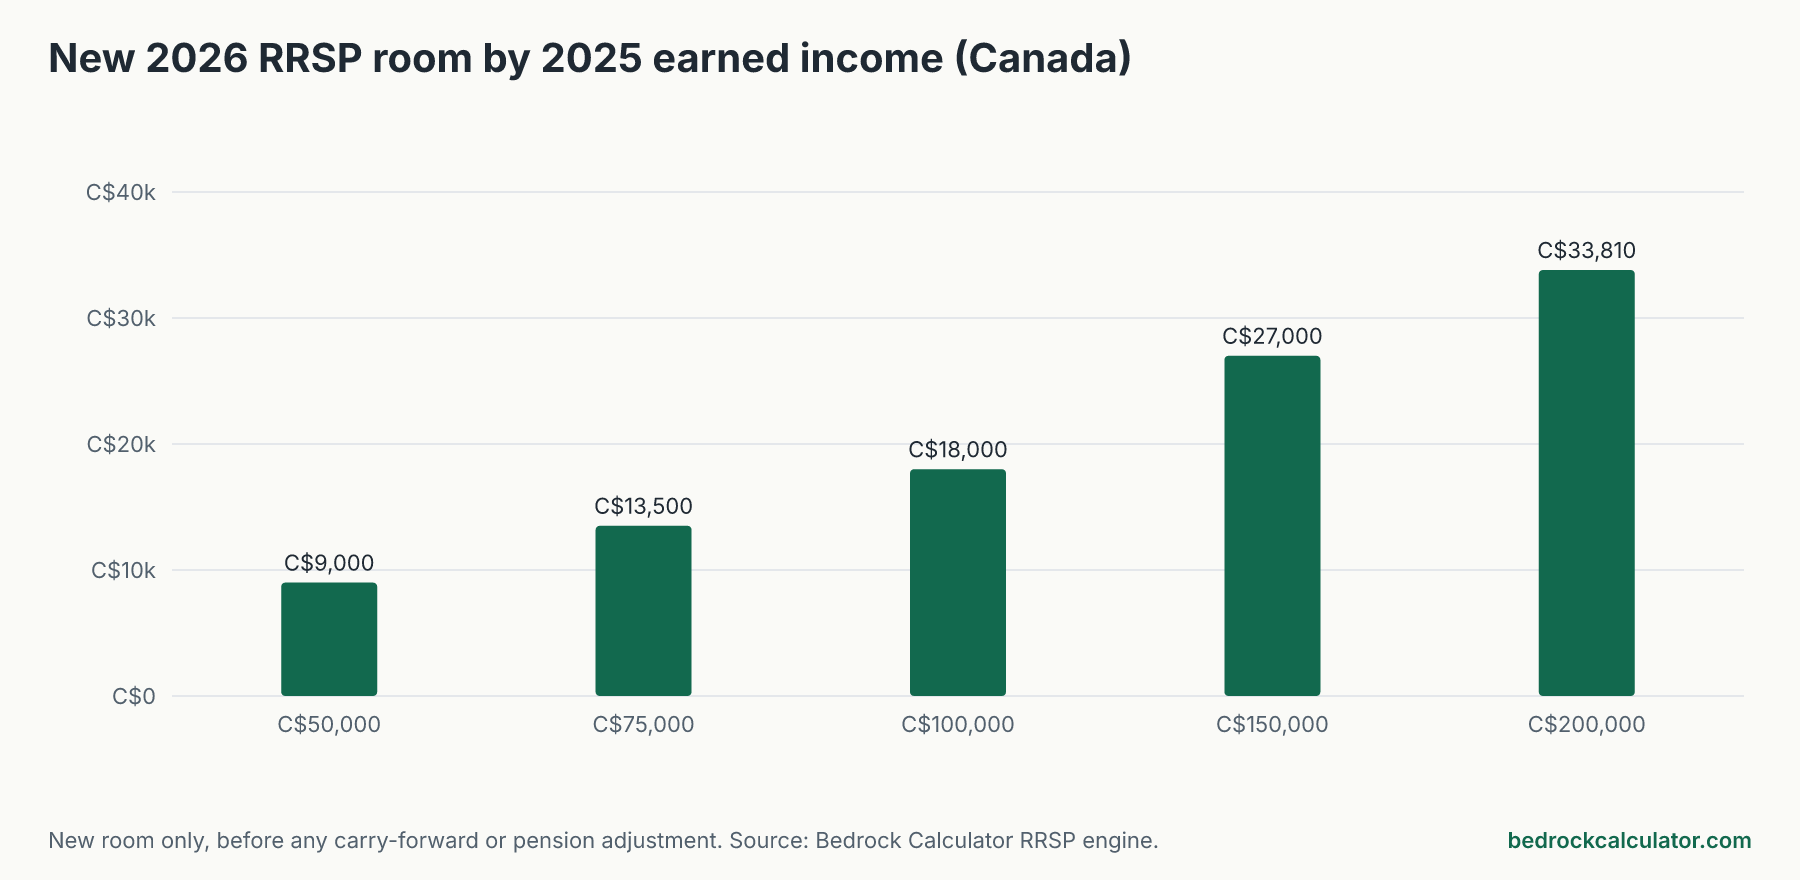
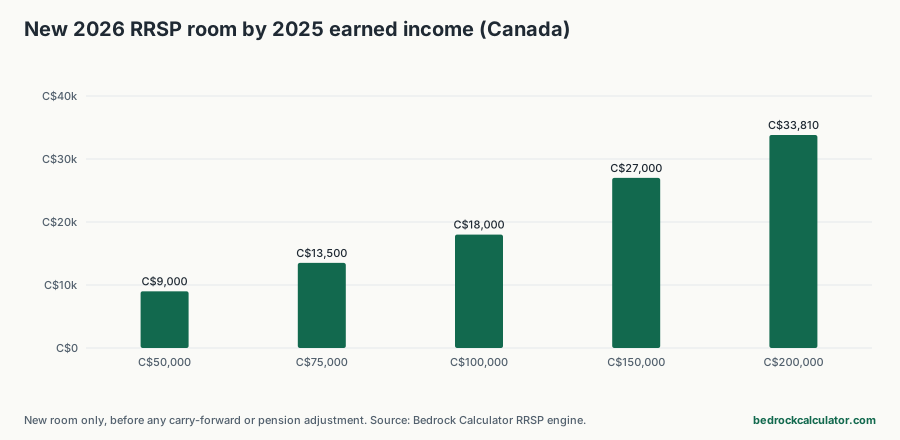
For most people the 18% figure is the one that applies. Someone who earned C$50,000 in 2025 gets C$9,000 of new room. At C$100,000 it's C$18,000, and at C$150,000 it's C$27,000. Only from about C$187,834 of earned income does the dollar limit take over, so at C$200,000 the new room stops at C$33,810.
Like the TFSA, unused RRSP room carries forward with no time limit. Unlike the TFSA, withdrawals don't give room back. Money taken out of an RRSP is taxed as income in the year you take it, and the room it used is gone for good. The exceptions are the Home Buyers' Plan and the Lifelong Learning Plan, which let you borrow from your RRSP and pay it back.
FHSA: C$8,000 a year, C$40,000 in total
The First Home Savings Account combines the best parts of the other two: contributions are deductible like an RRSP, and a qualifying withdrawal to buy a first home is tax-free like a TFSA. The limits are fixed in the Income Tax Act and aren't indexed, so they're the same as last year.
You can put in C$8,000 a year. If you skip a year, up to C$8,000 of unused room carries into the next, so the most you can ever contribute in a single year is C$16,000. The lifetime limit is C$40,000, which takes five years of maximum contributions to fill.
The catch that trips people up: FHSA room only starts building once you open an account. Unlike the TFSA, there's no room accumulating in the background. If you think you might buy a home in the next fifteen years, opening an FHSA now, even with a small deposit, starts the clock on your room.
Home Buyers' Plan: C$60,000 per person
The Home Buyers' Plan lets a first-time buyer withdraw up to C$60,000 from an RRSP without paying tax on it, as long as it's paid back. Repayment is spread over 15 years, so a full withdrawal means C$4,000 a year going back into the RRSP. If you skip a repayment, that year's amount is added to your taxable income.
Because the limit is per person, a couple who both qualify can take C$120,000 between them. You can use the Home Buyers' Plan and an FHSA for the same purchase, which is why so many first-time buyers end up using both.
Which account should get your money first?
The limits only tell you how much you can put in. The order matters more. A rough guide:
- Saving for a first home: the FHSA usually comes first, because you get the deduction going in and pay no tax coming out.
- Higher income now than you expect in retirement: the RRSP tends to win, because you deduct at a high rate and withdraw at a lower one.
- Lower income now, or unsure: the TFSA is the flexible choice, since withdrawals don't count as income and the room comes back.
We've worked through that trade-off with real numbers in our TFSA vs RRSP comparison. To see your own room and growth, start with the TFSA calculator or the RRSP calculator, and check the figures against the room shown on your latest CRA Notice of Assessment.