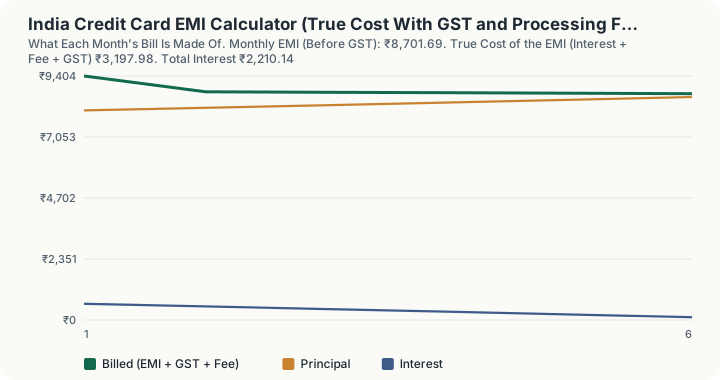
Quick Answer: Converting ₹50,000 on a credit card into a 6-month EMI at 15% a year with a 1% processing fee gives an EMI of ₹8,701.69. Add 18% GST on the interest and the fee and the conversion really costs ₹3,197.98, not the ₹2,210.14 of interest the offer shows. Counting the fee and GST, that works out to an effective cost of about 24.15% a year.
What does this calculator do?
Card issuers in India let you turn a large purchase, or part of your outstanding balance, into equated monthly instalments. The offer usually shows an interest rate and an EMI. What it rarely puts in one place is the full cost: the processing fee, and the 18% GST that is charged on both the interest in every instalment and the fee itself.
This calculator puts those pieces together in rupees. It works out the reducing-balance EMI, adds GST month by month, adds the fee and its GST to the first bill, and gives you the total extra you pay over the purchase price. It also converts all of that into a single effective annual cost, so you can compare a card EMI with a personal loan or with simply paying the bill.
GST applies here because the GST exemption for interest on loans and advances specifically leaves out interest involved in credit card services. Ordinary loan interest is exempt; card interest is not. The 18% rate is the standard GST rate for services, which the September 2025 GST rate changes left in place.
How is this calculated?
- Monthly rate. The annual EMI rate is divided by 12. At 15% that is 1.25% a month.
- EMI. The reducing-balance EMI that clears the amount over the tenure, rounded to the paisa: EMI = P × i(1+i)ⁿ ÷ ((1+i)ⁿ − 1).
- Interest each month. Interest on the remaining balance at the monthly rate, rounded to the paisa. The rest of the EMI repays principal. The last EMI settles any rounding difference.
- GST on interest. 18% of each month's interest, added to that month's bill.
- Processing fee and its GST. The fee is the percentage you enter times the amount, plus any flat fee. GST at 18% is added to it, and both are billed with the first EMI.
- True cost. Total interest + processing fee + GST on interest + GST on the fee.
- Effective annual cost. The calculator finds the monthly rate at which the amount you converted equals the present value of every monthly bill, then compounds it to a yearly figure: (1 + monthly rate)¹² − 1.
True cost = ∑ interest + fee + 0.18 × (∑ interest + fee)
Worked Example
₹50,000 converted for 6 months at 15% a year, with a 1% processing fee.
Step 1: the monthly rate. 15% ÷ 12 = 1.25% a month
Step 2: the EMI. ₹50,000 over 6 months at 1.25% gives an EMI of ₹8,701.69.
Step 3: month 1. Interest is ₹50,000 × 1.25% = ₹625.00, and GST on it is ₹112.50. The processing fee is 1% of ₹50,000 = ₹500, plus ₹90 GST. The first bill for this EMI is ₹8,701.69 + ₹112.50 + ₹500 + ₹90 = ₹9,404.19.
Step 4: the balance falls. ₹8,701.69 − ₹625.00 = ₹8,076.69 repays principal, leaving ₹41,923.31. Month 2's interest is ₹524.04 and the bill is ₹8,796.02.
Step 5: the last month. Interest has fallen to ₹107.43 and the final bill is ₹8,721.03.
Step 6: add it all up. Interest over six months: ₹2,210.14. GST on interest: ₹397.84. Fee: ₹500. GST on fee: ₹90. True cost: ₹3,197.98, so you pay ₹53,197.98 in total for a ₹50,000 purchase.
Step 7: the effective rate. Running those six bills against the ₹50,000 gives an effective cost of about 24.15% a year. The quoted 15% leaves out the fee and the GST, and a fee paid up front on a short loan pushes the true rate up sharply.
Step 8: a longer tenure. The same ₹50,000 over 12 months at 15% has a lower EMI of ₹4,512.92 but costs ₹5,492.87 in total, with an effective cost of about 21.89% a year. Over 3 months the cost is ₹2,071.12, but the effective rate rises to about 27.88% because the fixed fee is spread over a very short loan.
Step 9: a "no-cost" EMI. At 0% interest with a flat ₹199 fee, the EMI is ₹8,333.33 and the only cost is the fee plus ₹35.82 of GST: ₹234.82. That is cheap, but it is not free.
What does this calculator not account for?
- Merchant discounts on no-cost EMIs. On many no-cost EMI offers the interest is offset by an upfront discount from the seller or the card issuer, and GST on that interest can still appear on your bill. The RBI requires the issuer to show the interest and any upfront discount before conversion. Enter what your statement shows; the calculator does not net off a discount.
- Pre-closure charges. Closing the EMI plan early may attract a fee set by your issuer. Not modelled.
- Late payment and finance charges. If you miss a bill, the card's own finance charges and late fees apply on top. Not included.
- Your card's billing dates. The calculator treats each EMI as one month apart from the conversion date. Actual statement dates can shift the first bill.
- Different fee rules. Some issuers cap the processing fee or charge a flat amount. Use the flat fee input for those.
- Credit limit blocking. The converted amount usually stays blocked on your limit and frees up as you repay. Not shown.
What mistakes do people make with this?
- Reading the interest rate as the cost. The quoted rate leaves out GST and the fee. On the default example, they add almost half again to the interest.
- Forgetting GST is on the interest, not the purchase. GST here is 18% of the interest and fee only, not of the item you bought.
- Choosing the shortest tenure to "save interest" without checking the fee. A fixed fee on a 3-month plan can make it the most expensive option per rupee per year, even though the total cost is lower.
- Assuming no-cost means no cost. A processing fee and GST on it still apply, and in some plans the interest and its GST are charged and only offset by a discount.
- Converting when you could pay in full. If you can clear the bill by the due date, the card charges no interest at all.
Frequently Asked Questions
Is GST charged on credit card EMI interest in India?
What is the real cost of a ₹50,000 credit card EMI for 6 months?
Is a no-cost EMI really free?
What is the EMI on ₹1 lakh for 12 months on a credit card?
Can unpaid GST or fees attract interest?
Sources
- Central Board of Indirect Taxes and Customs, Schedule of GST rates for services as approved by the GST Council: exemption for interest on deposits, loans or advances "other than interest involved in credit card services" (exemption list item 8(i)), and 18% for all other services: cbic-gst.gov.in/pdf/Schedule%20of%20GST%20rates%20for%20services.pdf
- Reserve Bank of India, Master Direction, Credit Card and Debit Card, Issuance and Conduct Directions, 2022 (updated 7 March 2024), paragraph 6(b)(iii) on EMI conversion disclosure and paragraph 9(b)(ii) on not capitalising unpaid charges and taxes: rbi.org.in/Scripts/BS_ViewMasDirections.aspx